Pelthos Misses As Zelsuvmi Stalls Sequentially, And The Castle Creek Pivot Raises The Stakes For A Balance Sheet Already Under Strain
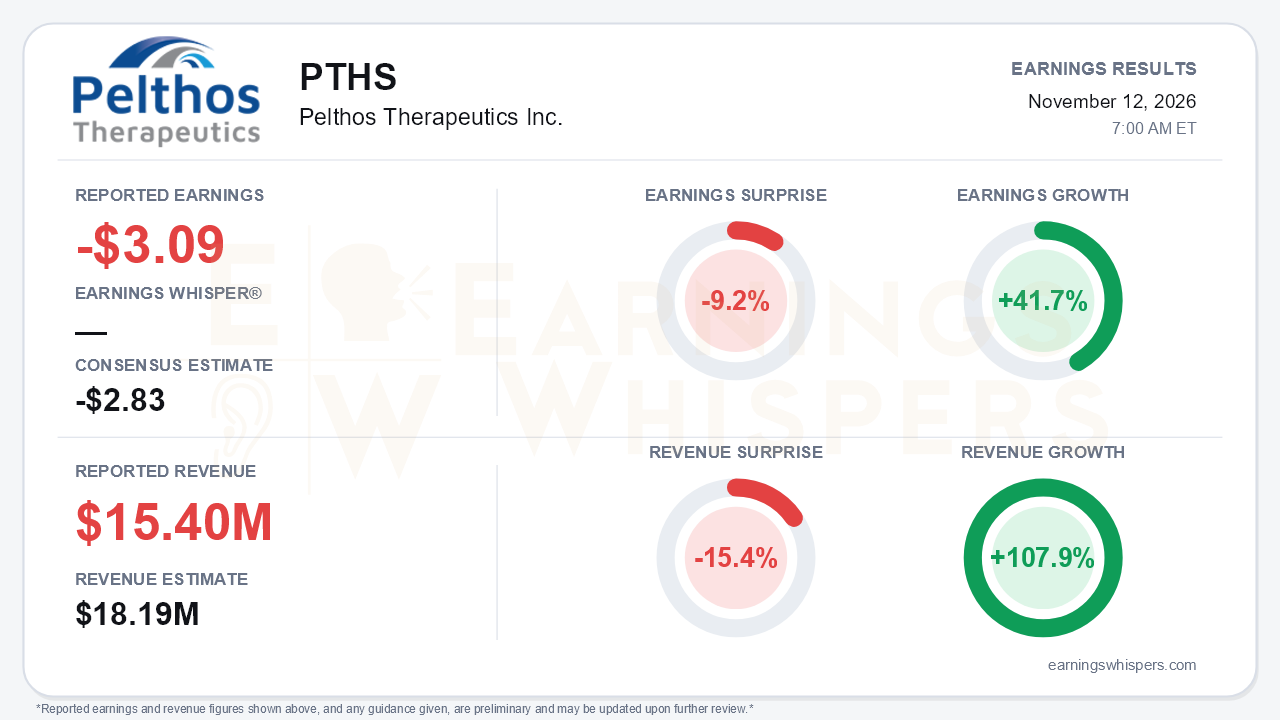
Pelthos Therapeutics (NYSE American: PTHS) reported a third-quarter loss of $3.09 per share, missing the consensus estimate of -$2.83 by 9.2%. Revenue of $15.4 million fell 15.4% short of the $18.19 million consensus. Year-over-year comparisons still look strong: earnings improved 41.7% and revenue grew 107.9%. But those figures reflect easy comparisons against Zelsuvmi's launch quarter. The central development is that the launch curve flattened. Zelsuvmi net product revenue slipped to $15.2 million from $15.4 million in the second quarter, the product's first sequential decline since launch. Revenue had grown 45% sequentially in Q2 and 17% in Q1.
The quality of the quarter needs some unpacking. The GAAP net loss narrowed sharply, to $7.9 million (-$2.04 per share) from $23.4 million in Q2. Much of that improvement came from items unrelated to demand:
- a $4.1 million gain on the fair value of convertible debt, versus a $3.7 million loss in Q2;
- the absence of Q2's $5.3 million milestone expense;
- lower cost of goods sold, after Q2 absorbed a $0.9 million inventory write-off and a larger acquisition step-up.
This explains why the normalized loss of $3.09 per share is wider than the GAAP figure. Adjusted EBITDA is the cleaner read on operations. It was -$5.6 million, essentially unchanged from -$5.7 million in Q2. The genuine operating gains were per-unit COGS down about 39% and cash SG&A holding near $16.9 million. Even so, the earnings-quality picture is one of a stalled loss, not a shrinking one.
The call explained the plateau without fully reassuring on it. Units dispensed rose just 4% sequentially to 12,384, compared with 48% growth in Q2 and 25% in Q1. That came after management had guided in Q2 to quite stable Q3 claims with growth. Net price also moved against the company:
- Gross-to-net deductions rose to 31.5% from 29.6%.
- Management expects them to reach the mid-30s as new coverage takes effect.
- Management said revenue would have been modestly up without the new PBM rebate.
That argument cuts both ways: access is being bought with price. Normalized COGS guidance also softened, moving from mid-single digits to mid-to-high single digits of WAC. Most notably, earlier talk of reaching a profitability crossover around the end of 2026 was not repeated.
The operating case for a reacceleration rests on access. Commercial coverage rose to 127 million lives, roughly 70%, up from the 59% cited on recent calls. The gain came from:
- a major PBM contract effective October 1 with open access and no prior authorization, covering about 24 million lives;
- a regional plan win covering about 3 million lives.
Early indicators are encouraging but modest:
- Unique prescribers climbed to 4,942 from 4,571.
- Units per patient edged up to about 1.3, and refills rose about 22% quarter over quarter.
- October units of 4,231 marked the second-highest month, though only 4% above September.
The Xepi (Q1 2027) and Xeglyze (Q3 2027) launch timelines were held. Together these give management a credible path to renewed growth. Q4, however, is where that path has to show up in revenue.
The Castle Creek merger is the bigger strategic shift, and it is where bears have legitimate ammunition. The deal adds D-Fi, a Phase 3 gene-modified cell therapy for dystrophic epidermolysis bullosa (DEB) with worldwide rights and several FDA designations. Management benchmarked the opportunity against Vyjuvek's $127 million quarterly revenue. But the deal is equity-funded, which brings dilution, and it adds late-stage clinical risk to a company that has not yet reached breakeven. Analysts openly questioned the timing. The transaction is expected to close by the end of Q1 2027, pending Castle Creek stockholder approval.
The balance sheet is tightening:
- Cash fell to $17.7 million from $24.2 million in Q2 and $32 million in Q1.
- Stockholders' equity swung to a $6.2 million deficit from $38.9 million positive at year-end.
- Pelthos drew another $10 million from Horizon, bringing outstanding debt to $40 million.
- The next $10 million tranche requires trailing twelve-month revenue of $70 million. The current run rate of roughly $15 million a quarter has not yet reached that level.
The market had already turned decisively against the stock before the release. Shares fell 66.2% from the $27.80 open after the August report to $9.39. They sit about 60% below the 200-day moving average of $23.64 and just 7.7% above a fresh 52-week low of $8.72, set the day before earnings. Investor sentiment swung from mildly positive (0.15) to firmly negative (-0.53), a genuinely large shift. The Earnings Whispers trend readings are mixed, with momentum positive while AVWAP remains negative. Expectations were therefore already low going into the print. The question is whether this report gives skeptics new reasons to sell or simply confirms what the price already reflected.
The bottom line is that Pelthos delivered a double miss that exposed a Zelsuvmi growth plateau, rising price concessions, and a stalled adjusted EBITDA loss, while layering a dilutive Phase 3 bet onto a thinning balance sheet. Broader PBM access and improving October trends offer a plausible route back to growth. Until Q4 revenue reaccelerates, though, the narrowing GAAP loss flatters the quarter, and the Castle Creek story is asking investors to underwrite more risk at a moment when the core franchise has lost momentum.
Read our earnings preview for Pelthos Therapeutics Inc.: https://www.earningswhispers.com/article/PTHS/22964
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-05 | |
| Nov-04 | |
| Nov-02 | |
| Oct-30 | |
| Oct-06 | |
| Aug-13 | |
| Aug-13 | |
| Aug-12 | |
| Aug-03 | |
| Jul-24 | |
| Jun-30 | |
| May-28 | |
| May-14 |
