NIQ Beats And Raises Again, But A Stock Up 54% Since August Now Leans On An Americas-Led Story While Subscription Growth Keeps Drifting Lower
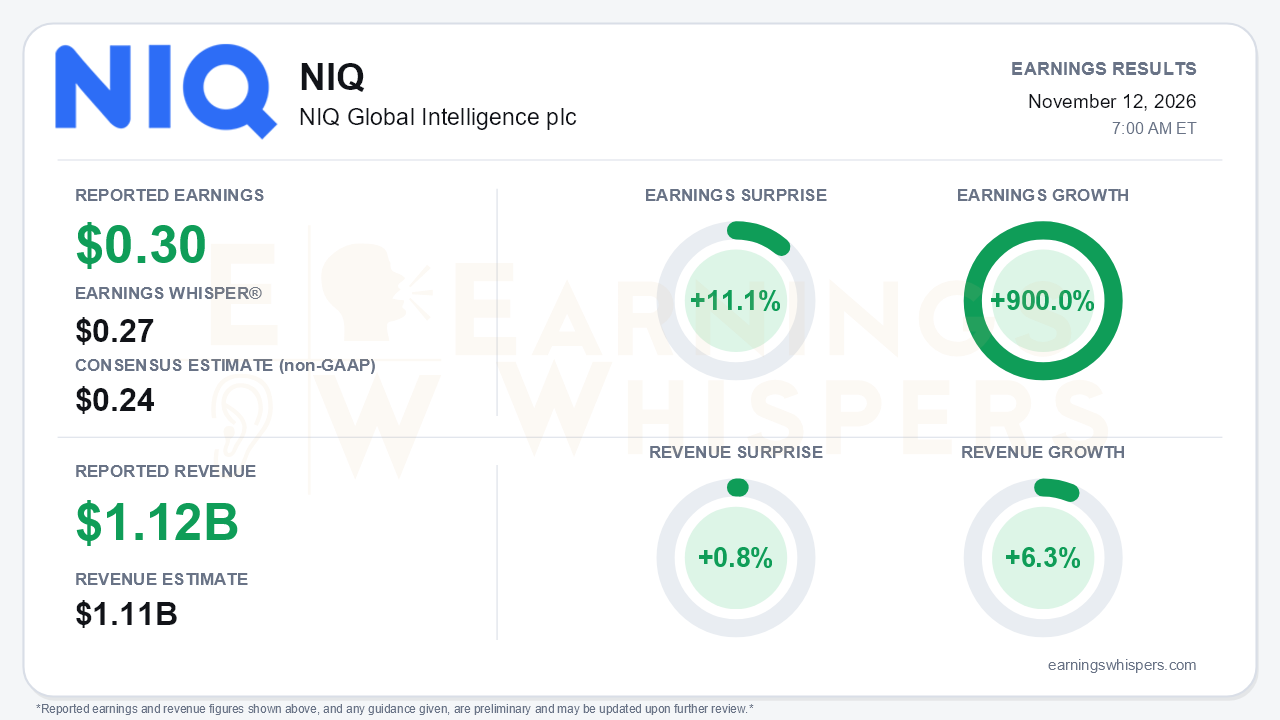
NIQ Global Intelligence delivered its sixth consecutive beat-and-raise. Adjusted EPS of $0.30 topped the $0.24 consensus by 11.1% and cleared the $0.27 Earnings Whisper number. That figure was up 900.0% from $0.03 a year ago, when heavy pre-IPO interest costs depressed the comparison. Revenue of $1.119 billion grew 6.3% and edged past the $1.11 billion consensus by 0.8%. The quarter also brought several firsts: the first positive GAAP EPS since the IPO, net leverage below 3x a quarter ahead of plan, and a first-ever $150 million buyback. The central tension is that profitability, cash returns and the AI narrative are all improving quickly, while the core growth engine outside the Americas, and the subscription base underneath it, is not.
The margin story is real. Adjusted EBITDA rose 17.8% to $263.6 million on 6.3% revenue growth, and margin expanded 230 basis points to 23.6%, up from 23.3% in Q2 and 21.0% in Q1. Cost cuts are flowing through the 2026 restructuring program, which targets $70 million to $80 million of annualized savings. Interest expense fell to $54.3 million from $78.2 million. The GAAP milestone deserves more scrutiny, however. Net income of $35.8 million was helped by roughly $24 million of nonoperating items: an $11.9 million royalty recovery, a $6.0 million bargain purchase gain and a $5.8 million gain on the sale of subsidiaries. Without them, the GAAP profit would have been thin. Cash flow was also softer than the headline suggests. Levered free cash flow of $181.2 million trailed the prior year's $224.4 million because of vendor-payment timing and higher capitalized spending on the Connect platform and AI products. Management expects free cash flow to step down in Q4.
On the top line, organic constant-currency growth held at 5.8%, matching Q2 and up from 5.1% in Q1. Beneath that steady figure, the mix is diverging:
- **Americas:** accelerated to 11.5% from 8.3%, driven by Consumer Panel and eCommerce growth above 20%.
- **Activation:** improved for a third straight quarter, to 7.0%.
- **EMEA:** slowed to 2.9% from 4.9% as Middle East volatility hit ad hoc project work. EMEA Activation revenue fell 4.7%, and segment margin slipped sequentially.
- **APAC:** essentially stalled at 0.2%.
The more structural concern is the subscription base. Annualized Intelligence subscription growth has drifted from 6.6% at Q4 FY25 to 5.5% now, with net dollar retention at 105%. Other usage indicators cited on the call also cooled. Client data-usage growth eased to about 20% from 25% in Q2, and AI-native revenue growth slowed to 28% year to date from 34%.
The guidance picture explains why the outlook can be both "raised" and "in-line." Full-year targets moved higher across the board:
- organic growth of 5.5% to 5.7%;
- adjusted EPS of $1.16 to $1.20, up from $1.08 to $1.12;
- levered free cash flow of $249 million to $257 million.
Those increases largely bank the Q3 outperformance and lower interest and tax assumptions. The implied Q4 organic growth of 5.4% to 5.7% is flat to slightly below Q3, and the fourth quarter laps a large retailer win while carrying a heavier mix of hard-to-forecast ad hoc work. The full-year margin range was narrowed rather than lifted at the midpoint.
The catalyst list is where the call clearly improved the story. NIQ announced a Google agentic-commerce partnership that brings data on more than 265 million products into the Shopping Graph. It is also building a commerce intelligence agent with OpenAI DeployCo, starting with US Beauty. ConnectAI expanded to 10 charter clients, including Mars Snacking and Purina, and management said the proof-of-concept pipeline is now around 100, up from 49 opportunities in Q2. Roughly 60% of top-100 clients now use AI products. For the first time, management put a number on AI's contribution: about 0.1 point of growth in 2026 and 25 to 50 basis points in 2027, with organic growth expected to build through next year. That is a credible, measured framing rather than a hype-driven one. The risks are also explicit. Management flagged possible restructuring charges in 2027 tied to further AI efficiency actions, and Middle East exposure remains a live drag on EMEA.
The market had already priced in much of this good news. Investor sentiment swung from -0.40 after the August report to +0.49, a genuine reversal from skepticism to optimism. Shares rose 53.6% from the $13.71 post-report open to $21.06. That leaves the stock nearly 58% above its 200-day moving average and just 2.1% below the 52-week high of $21.52 set on November 9, so it entered the report near the top of its range. Momentum and AVWAP readings remain positive. Bears have legitimate ammunition in decelerating international growth and subscription trends, and the setup leaves less room for a merely in-line fourth quarter.
The bottom line is that NIQ continues to execute on margins, deleveraging and AI positioning, and the buyback marks a real shift in its capital story. However, a stock priced near its highs now depends on the Americas and new AI revenue offsetting softening EMEA, APAC and subscription trends.
Read our earnings preview for NIQ Global Intelligence plc: https://www.earningswhispers.com/article/NIQ/22889
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 6 hours | |
| 7 hours | |
| 8 hours | |
| 9 hours | |
| Nov-10 | |
| Nov-09 | |
| Nov-04 | |
| Nov-02 | |
| Oct-30 | |
| Oct-29 | |
| Oct-28 | |
| Oct-22 | |
| Oct-21 | |
| Oct-15 |
