SOLV Energy Misses On EPS As Post-IPO Structure Weighs, But A Revenue Beat And Third Guidance Raise Keep The Growth Story Intact
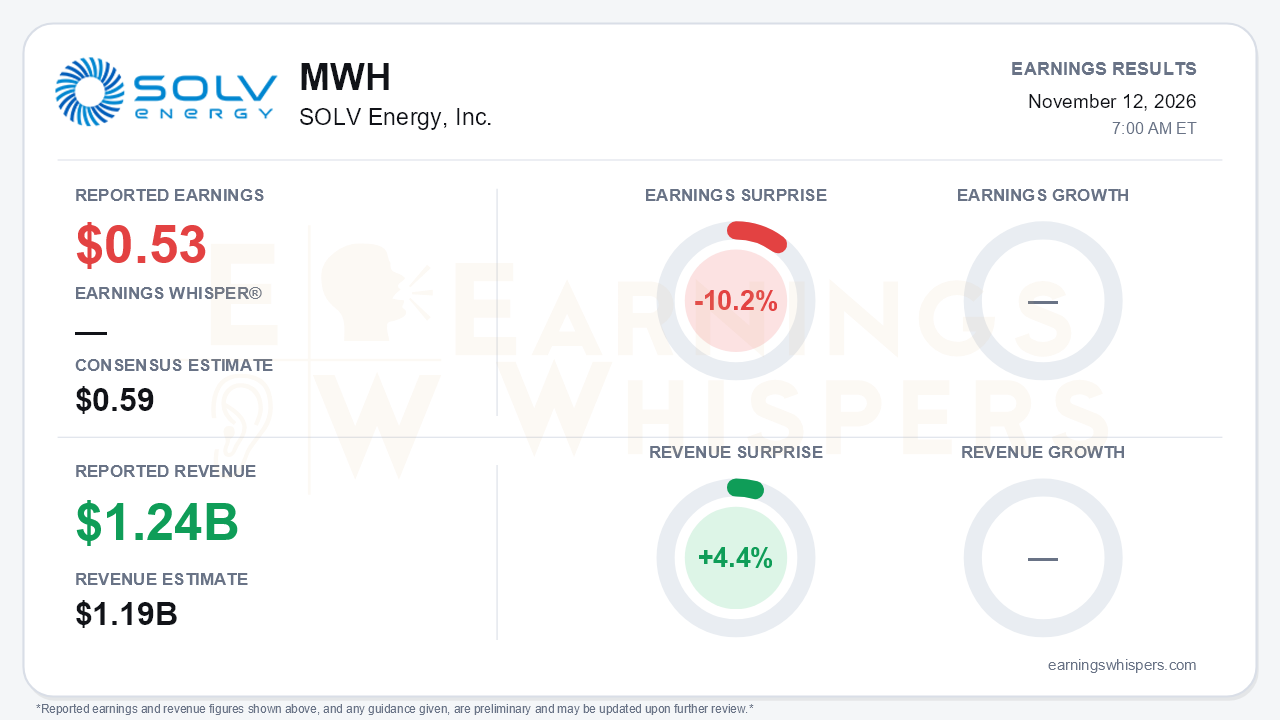
SOLV Energy (NASDAQ: MWH) reported third-quarter earnings of $0.53 per share, missing the $0.59 consensus estimate by 10.2%. Revenue was a record $1.242 billion, 4.4% above the $1.19 billion consensus and up 65% from a year earlier. Management also raised full-year guidance for the third consecutive quarter. That is the central tension. The per-share miss sits on top of a business that is growing faster and earning more in absolute terms than expected.
The miss is mostly about how earnings flow to Class A shareholders, not about weaker operations. Consolidated net income rose to $123 million from $70 million, and operating income jumped to $142 million from $83 million. Interest expense fell to $1.7 million from $13.7 million after the IPO proceeds retired the term debt. Two post-IPO items absorbed much of that gain:
- Income tax expense rose to $21 million from about $0.5 million under the old pass-through structure.
- Non-controlling interests claimed $53 million of net income.
As a result, net income attributable to SOLV was $69.9 million, essentially flat with last year.
The quality of the quarter still deserves scrutiny on two fronts:
- **Year-over-year margins compressed.** Adjusted gross margin fell to 17.3% from 19.7%, and adjusted EBITDA margin fell to 13.9% from 16.1%. Management attributed the decline to contingency releases and a large repair job that flattered 2025, plus the reclassification of incentive compensation into cost of revenue.
- **Working capital is absorbing cash.** Accounts receivable climbed to $649 million from $269 million at year-end, and working capital consumed $146 million year-to-date.
The sequential trend is more encouraging than the year-over-year comparison. Revenue climbed from $677 million in Q1 to $951 million in Q2 and $1.24 billion in Q3. Adjusted EBITDA rose from $93 million to $117 million to $173 million, and the 17.3% adjusted gross margin improved on the 16.5% first-half level. Growth did decelerate, slowing to 65% from 77% in Q2, but that is a moderation from an extraordinary pace, not a break. The pipeline also kept refilling:
- Backlog reached about $9.2 billion, up from $8.9 billion in Q2 and $8.0 billion at year-end, despite heavy revenue burn.
- Storage-linked backlog rose to roughly $3.1 billion from $2.5 billion.
- SOLV booked its largest-ever award, a 1.2 GW project.
- Contracted O&M capacity topped 24 GW, up from 23 GW in Q2.
The CEO described demand as the strongest he has seen in 20 years and signaled meaningful growth in 2027.
The raised outlook frames the forward story:
- Revenue guidance moved to $4.03–4.12 billion.
- Adjusted EBITDA guidance moved to $525–540 million, from $485–505 million last quarter and $400–420 million initially.
- Cumulatively, the EBITDA midpoint has been raised roughly 30% this year.
The guide still implies a seasonal Q4 step-down. Subtracting nine-month results leaves roughly $142–157 million of fourth-quarter adjusted EBITDA, below Q3's $173 million.
On catalysts, the ASB Energy Services acquisition, closed October 30 for roughly $36 million in cash plus stock, adds self-perform substation and battery-storage capability in Texas. Management is also openly exploring gas-firming M&A for hybrid plants. Bears have legitimate ammunition as well:
- Section 232 tariffs and commodity costs are pushing up input prices.
- Election politics and local opposition to data centers create demand uncertainty.
- The ITC safe-harbor horizon looms around 2030.
- The company still discloses material weaknesses in internal controls.
The market setup is more complicated than the surprise implies. Shares have fallen 13.2% since the open following the August report, to $27.58. They peaked at $33.36 on that first post-report day and then slid to a 52-week low of $20.30 on October 23. The stock has since rebounded nearly 36% off that low but entered this report about 4.8% below its 200-day moving average of $28.96.
Investor sentiment became more negative, moving from -0.08 to -0.18. That is a meaningful but not dramatic deterioration, and it leaves expectations subdued heading into an EPS miss. Earnings Whispers trend readings for sequential growth, momentum and AVWAP are positive, consistent with the recent recovery off the October low.
The bottom line is that SOLV's per-share miss reflects its new tax and ownership structure more than any operational stumble. Revenue, backlog, EBITDA and guidance all moved higher, and the call preserved a credible growth story heading into 2027. Investors should watch three things: whether margins hold near current levels, whether receivables growth converts to cash, and whether tariff-driven cost pressure stays manageable.
Read our earnings preview for SOLV Energy, Inc.: https://www.earningswhispers.com/article/MWH/22886
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 7 hours | |
| 8 hours | |
| Nov-04 | |
| Nov-02 | |
| Oct-22 | |
| Aug-19 | |
| Aug-14 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 | |
| Aug-12 | |
| Jul-22 | |
| Jul-21 | |
| Jun-04 |
