MediWound's Penny EPS Beat Is Overshadowed By A 53% Revenue Miss And A Retreat From Its 2026 Revenue Outlook
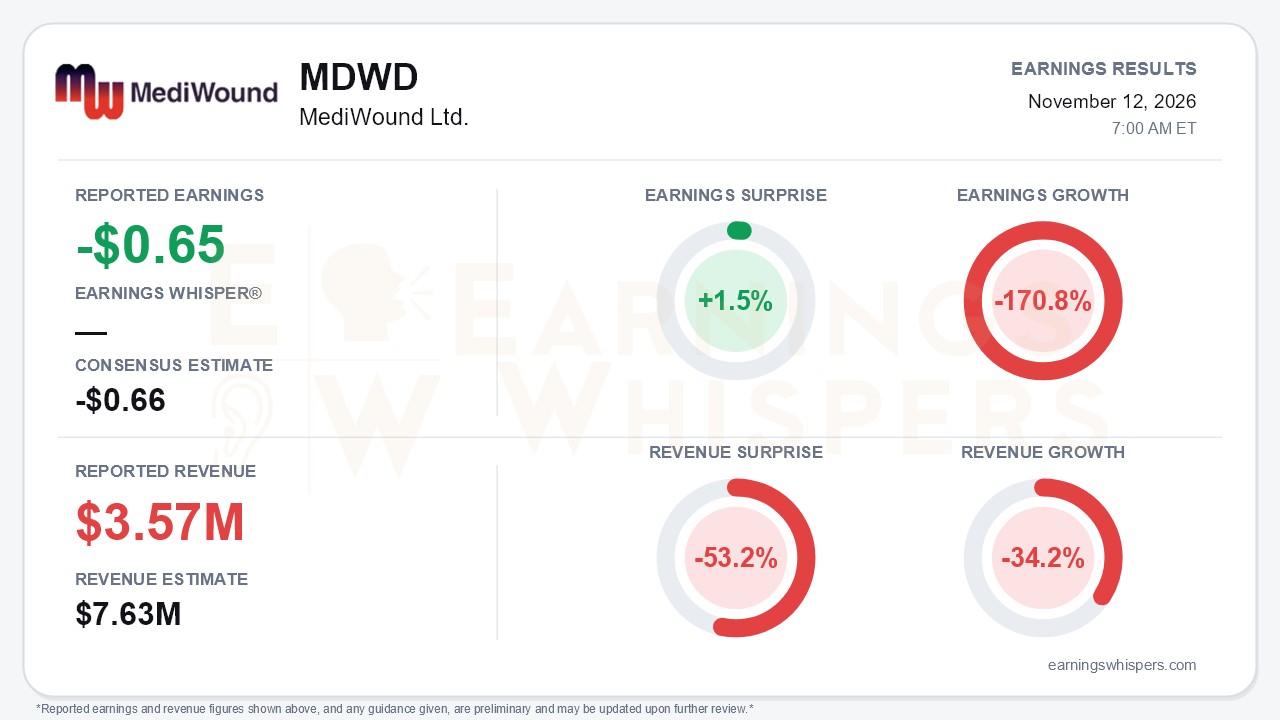
MediWound (NASDAQ: MDWD) technically beat on earnings, posting a loss of $0.65 per share against a consensus loss of $0.66, a 1.5% surprise. The beat is the least important number in the report. Revenue of $3.57 million missed the $7.63 million consensus by 53.2% and fell 34.2% year over year. Earnings deteriorated 170.8% from the year-ago loss. More consequentially, management stopped reaffirming the $24-26 million 2026 revenue outlook it had backed on the prior three calls. That is the central tension of the quarter: the commercial and clinical franchise is executing, but the revenue model that underpinned near-term guidance depends on U.S. government funding the company cannot predict.
The quality of the loss deserves scrutiny. The supplied figure reflects diluted EPS. The basic IFRS loss was $0.46 per share, versus $0.24 a year ago. The gap stems from warrant accounting rather than operations. The year-over-year deterioration, however, is real at the operating line:
- Operating loss widened to $8.5 million from $6.5 million.
- Adjusted EBITDA loss grew to $7.4 million from $5.4 million.
- R&D nearly doubled to $6.2 million as the EscharEx Phase III VALUE trial ramped.
- Net loss also widened because non-cash warrant revaluation income shrank, to roughly $2.5 million from $4.2 million.
The revenue decline came almost entirely from lower U.S. government development-services revenue. Through nine months, revenue totals just $8.1 million versus $15.1 million last year. Hitting the old guide would have required an implausible fourth quarter of roughly $16-18 million.
Beneath the top-line damage, several operating trends improved:
- **Gross margin** jumped to 28.5% from 10.9% in Q2 and 16.5% a year ago, driven by a richer mix of high-margin royalty revenue.
- **U.S. NexoBrid demand** hit records. Partner Vericel reported its strongest NexoBrid quarter since launch, with record revenue, ordering centers and hospital orders. More than 80 centers have now ordered, and about 70 have reordered. More new centers were added in the first nine months of 2026 than in all of 2025, suggesting the repeat-user base is maturing rather than relying on trial orders.
- **BARDA procurement** under Vericel's contract began in Q3 and is expected to run through the first quarter of 2027.
- **Department of War funding** for a room-temperature-stable NexoBrid rose by $3.3 million, lifting the program budget to $21.8 million.
- **Manufacturing compliance** held up. The current plant passed routine FDA and Israeli MoH/EMA-proxy GMP inspections.
The call preserved a credible clinical story. VALUE remains on track for its interim sample-size reassessment and full enrollment by the end of Q1 2027. The DSMB flagged no safety concerns, and top-line data is now framed for mid-2027. The expanded NexoBrid facility is on schedule to complete EMA-recommended modifications this quarter, with commercial supply expected in the second half of 2027.
Bears still have legitimate ammunition:
- **Guidance exposure.** The 2027 outlook of $32-35 million also leans substantially on the same uncertain U.S. facility funding, so the guidance problem is not confined to this year.
- **Clinical delays and risk.** The diabetic foot ulcer Phase II and pressure-ulcer studies, previously slated for Q4 2026, have not started; management now points to the 'next few weeks.' The VALUE interim reassessment could also enlarge the trial, adding time and cost.
- **Capacity constraints.** NexoBrid supply remains capacity-limited until the expanded facility is approved.
- **Cash burn.** Cash and deposits fell to $28.4 million from $36 million at mid-year and $53.6 million at year-end 2025, on $28.3 million of nine-month burn.
The November offering raised $17.25 million gross, plus $1.1 million from post-quarter warrant and option exercises. Management says this provides flexibility through and beyond the VALUE readout. Still, the raise was dilutive and arrived precisely as the revenue bridge weakened.
Investor sentiment had already soured heading into the report, sliding from essentially neutral (0.02) to -0.20. That is a meaningful move into negative territory. Price action was more resilient. Shares closed at $13.82 on the eve of the report, down only 1.7% since the open after the August release. The stock has rebounded about 17% from a 52-week low of $11.80 set on October 26 and sits about 5.5% below its inter-earnings high of $14.63. It remains 8.5% below its 200-day moving average of $15.11, however, so the recovery has not yet repaired the longer-term trend. The Earnings Whispers trend readings are largely neutral, with only AVWAP positive, which fits a stock in recovery mode rather than one with established momentum.
The bottom line is that MediWound's quarter splits cleanly in two. The franchise-building pieces are moving in the right direction: NexoBrid adoption, margin mix, government contracts, plant compliance and VALUE enrollment. The near-term financial story, meanwhile, has become far less dependable, with revenue guidance now hostage to an unsecured U.S. funding decision and the balance sheet requiring fresh equity. Investors are now essentially underwriting the mid-2027 VALUE readout and the 2H27 capacity expansion, not 2026 revenue. With sentiment already negative and shares still below their 200-day average, the market appears to have priced in some of that shift, but the guidance retreat removes a key pillar of support until funding clarity or clinical data arrives.
Read our earnings preview for MediWound Ltd.: https://www.earningswhispers.com/article/MDWD/22885
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 8 hours | |
| 10 hours | |
| 10 hours | |
| Nov-09 | |
| Nov-05 | |
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Oct-29 | |
| Sep-22 | |
| Sep-22 | |
| Sep-14 | |
| Sep-02 | |
| Aug-25 |
