Figure Technology Beats On Volume And Margin, But Take-Rate Compression And Kiavi Dilution Complicate The Story
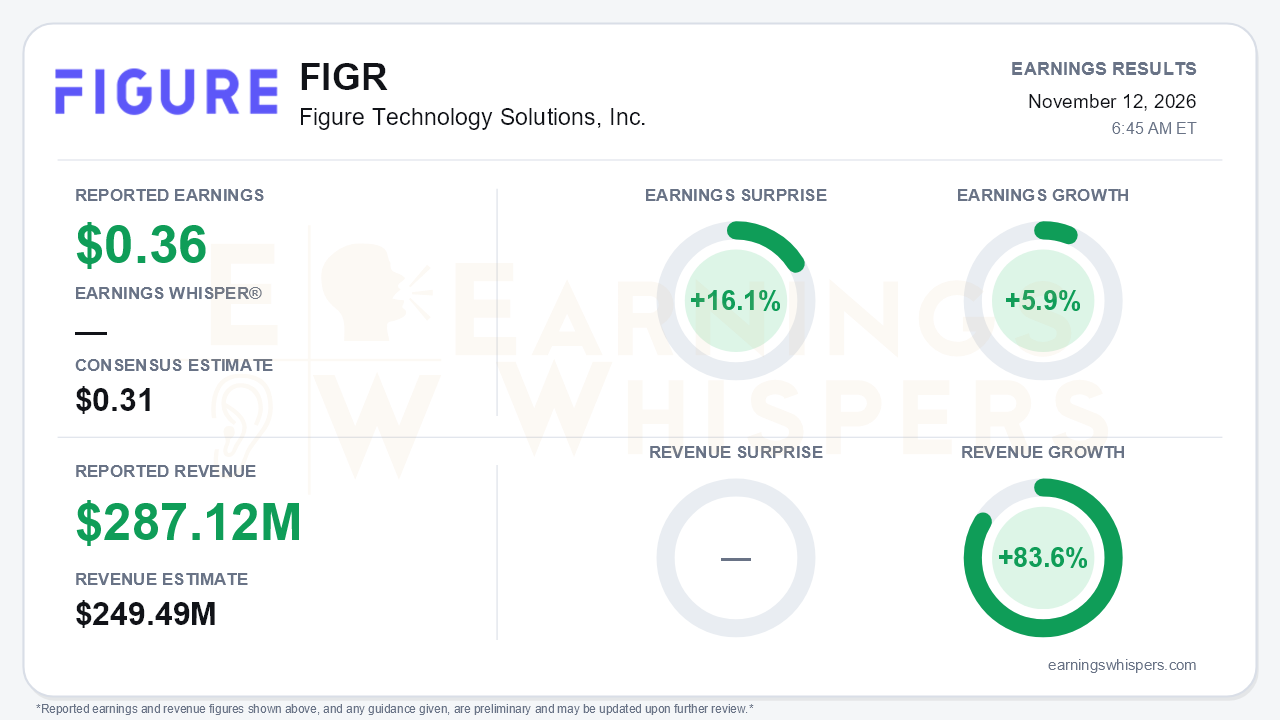
Figure Technology Solutions delivered another quarter that cleared expectations by a wide margin. Third-quarter diluted earnings of $0.36 per share topped the $0.31 consensus by 16.1%, and revenue of $287.12 million beat the $249.49 million estimate by 15.1%. Revenue grew 83.6% year over year, while earnings grew just 5.9%. That gap is the first clue that this quarter is more complicated than the beat suggests. Volume and adjusted profitability are excellent. The monetization of that volume is eroding, and management is changing how it measures it. That is the central tension.
The soft EPS growth partly reflects comparisons that are hard to read. GAAP net income was flat at $89 million because the year-ago quarter included a one-time $31 million tax benefit. Pretax income actually rose to $102 million from $58 million. Diluted share count also expanded to roughly 247 million from 130 million after the IPO, so per-share growth looks muted despite a sharply larger profit base. Adjusted EBITDA jumped 91% to $164 million, up from $119 million in Q2. Adjusted EBITDA margin rose to 58%, extending a climb from 50% in Q1 and 55% in Q2.
The revenue mix shows the capital-light pivot working. Ecosystem and technology fees roughly tripled to $110 million, while gain on sale of loans actually slipped to $58 million from $63 million. Loan Marketplace volume reached $5.8 billion, up 135%, including $677 million from one month of Kiavi. Standalone volume of $5.1 billion landed in the upper half of guidance. Figure Connect reached 72% of standalone volume, already past the roughly 70% medium-term target management set only a quarter ago. Partner count climbed to 612 standalone, or 894 including Kiavi, from 489 in Q2.
The cost of that growth is take rate. Gross take rate fell to 3.9% from 5.2%, and net take rate fell to 3.5% from 4.4%. The standalone net take rate of 3.7% did edge up from Q2 and beat the low end of guidance. Even so, management is now shifting disclosure away from net take rate toward gross take rate:
- Connect HELOC is guided at 2.9%–3.4%.
- RTL is guided at 1.5%–2%.
- Combined fourth-quarter gross take rate is guided at 3.1%–3.4%.
That compares with the 3.5%–4% net range investors had been anchored to. Management attributed the decline to large partners reaching lower pricing tiers and to banks keeping some loans on their own balance sheets. It also deferred contribution-margin detail to the next call. Bears have legitimate ammunition when a metric is reframed just as it weakens.
The fourth-quarter outlook adds a second layer of caution. Volume guidance of $6.2–$6.7 billion looks strong, but it includes a full quarter of Kiavi at an ~$8 billion annual run rate. Management also flagged a 10%–15% seasonal decline, so standalone volume likely dips sequentially. Kiavi ran at or below a 40% EBITDA margin before the deal and brings $18–$23 million of incremental fourth-quarter expenses. As a result, management expects margins to fall in Q4, pushing back the path to its 60% target, and it gave no Kiavi EBITDA guidance. Other risks include rising rates weighing on partner consumer funnels and the executive chairman's time split with the new Navra venture.
The call still preserved a credible growth story. Kiavi closed early, with $30 million of $35 million in cost synergies already actioned, and adds a $200 billion-plus RTL and DSCR market. Other catalysts include:
- **Kiavi upsell pipeline:** 12 partners have been onboarded to Kiavi products, with 30-plus in the pipeline. Management labeled 2027 "the year of the upsell."
- **Capital markets:** Sixth Street committed to forward flow, and New York Life and Nationwide joined as new AAA buyers.
- **Prime:** matched offers grew to $588 million.
- **Capital return:** the buyback authorization doubled to $400 million, executing immediately, backed by $1.59 billion in cash.
Investors should note, however, that non-current debt has climbed to nearly $1 billion.
The market had been punishing the stock regardless. Shares fell 24.7% since the open after the August report and touched a 52-week low of $19.54 on November 5. They sit 26% below the 200-day moving average and about 42% under the $41.50 inter-earnings high set in late August. Investor sentiment improved from slightly negative to modestly positive, a meaningful but not euphoric shift. Earnings Whispers trend readings are mixed, with momentum positive but AVWAP still negative.
The bottom line is that Figure's growth engine is running hot, with volume, partner, and Connect metrics all exceeding the targets management set just months ago. The quality of the beat deserves scrutiny, though: take rates are compressing and the reporting framework is shifting. Q4 margins will step down with Kiavi, so the stock's depressed level reflects real doubts about monetization rather than simple neglect.
Read our earnings preview for Figure Technology Solutions, Inc.: https://www.earningswhispers.com/article/FIGR/22875
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 7 hours | |
| 7 hours | |
| Nov-04 | |
| Oct-30 | |
| Oct-26 | |
| Oct-22 | |
| Oct-22 | |
| Oct-19 | |
| Oct-07 | |
| Oct-06 | |
| Oct-06 | |
| Sep-10 | |
| Sep-09 | |
| Sep-03 |
