Suburban Propane Misses On Earnings As Tax Credits, Not Propane, Drive The Improvement
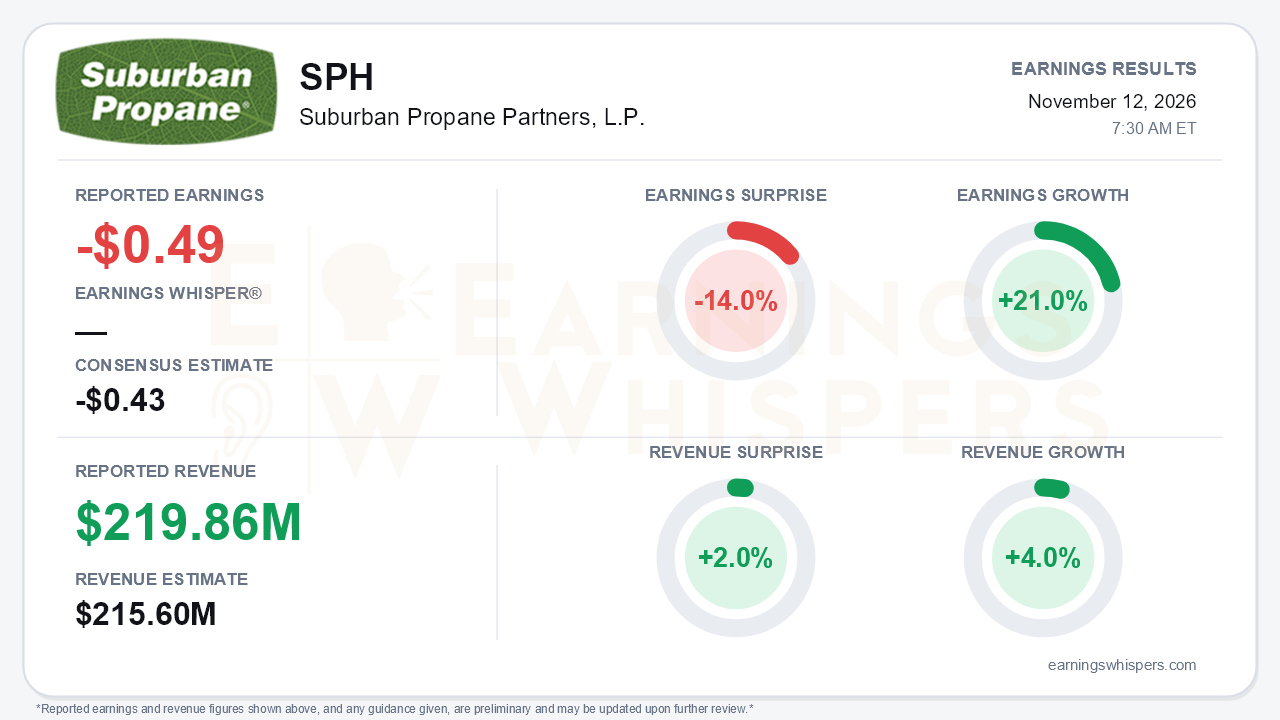
Suburban Propane Partners reported a fiscal fourth-quarter loss of $0.49 per unit, short of the -$0.43 consensus by 14.0%, even as revenue of $219.86 million beat the $215.6 million estimate by 2.0% and grew 4.0% year over year. Earnings improved 21.0% from a year ago, so the seasonal loss narrowed but not by as much as analysts expected. The GAAP picture is worse. The partnership's net loss widened to $56.8 million, or $0.85 per unit, from $35.1 million, or $0.53. That reflects a $23.1 million impairment on an early-stage energy technology investment and a $7.9 million goodwill write-down in the natural gas and electricity marketing business, which management tied to New York regulation. The central tension is that nearly all of the year's improvement came from renewable natural gas tax credits and RNG volumes. The core propane franchise was essentially flat.
The segment detail makes that clear. Fourth-quarter Adjusted EBITDA rose to $7.3 million from $0.7 million, but that figure included $7.8 million of production tax credits. The PTC benefit alone exceeded the quarter's entire Adjusted EBITDA. Propane segment Adjusted EBITDA slipped to $22.0 million from $22.9 million in the quarter and was flat for the year at $365.9 million. RNG segment EBITDA swung to $8.6 million from a $2.6 million loss. Corporate costs climbed to $23.7 million from $20.2 million. For fiscal 2026, Adjusted EBITDA rose 2.2% to $284.0 million, and total gross margin rose 3.8% excluding mark-to-market gains. The drivers were a $0.05-per-gallon gain in propane unit margins, slightly higher volumes and $12.4 million of PTCs. Combined operating and G&A expenses rose 3.9%, absorbing most of the margin gain. The quality of the improvement deserves scrutiny. It is real, but it rests heavily on credits whose value depends on government policy.
The call explained why that RNG contribution jumped. The Department of Energy's September 2026 update to the 45Z model materially improved carbon-intensity scoring for dairy manure RNG. That lifted recognized PTCs from $1.1 million in the third quarter to $12.4 million for the year, including a $4.4 million catch-up in the fourth quarter. The upstate New York digester entered service in July and generated $11.3 million of investment tax credits. About $3 million of credits were monetized in fiscal 2026, and management expects to monetize the remainder in fiscal 2027. RNG injection rose about 37% in the fourth quarter after being flat in the third. Low Carbon Fuel Standard prices climbed from the mid-$50s to near $90, and management expects them to hold. Propane demand, by contrast, stayed muted. Retail gallons rose just 1% for the year after quarterly results of +4.2%, flat, -1.8% and flat. Colder weather in the East was offset by a West that ran 23% warmer than normal and by a near-record warm spring.
The forward setup has notable positives. Leverage improved to 4.13x from 4.57x in the first quarter. The partnership refinanced $350 million of 2027 notes into 2035 paper. Fiscal 2027 capital spending is guided down to $60–70 million from $85.7 million as the RNG build-out wraps up. That freed-up cash supported the first distribution increase in several years, a 7.7% raise to $1.40 annualized, with coverage at 2.13x. Management's tone was more confident, and it referenced potential for further distribution upside. Bears have legitimate ammunition, though:
- **Propane costs:** Wholesale prices spiked to above $1.30 per gallon in early November and now sit near $1.05, roughly 70% above last year. That pressures heating-season demand through conservation and adds to working-capital needs.
- **Limited RNG growth:** Management signaled no further RNG platform expansion, so growth must come from optimizing existing assets.
- **Policy dependence:** The most dynamic part of the earnings story rests on tax credits and environmental attribute markets that can change with regulation.
Investor expectations had already soured before the report. Earnings Whispers sentiment swung from 0.29 to -0.30 by November 10, a substantial reversal from mildly positive to mildly negative. The stock has gone nowhere on balance, up only 1.3% from the $17.49 open after the August report to $17.71. That path included a slide to a 52-week low of $16.25 on October 1 and a rebound to $18.24 on October 27. Shares sit about 9% above that low but remain 5.1% below the 200-day moving average of $18.66. The internal trend readings are mostly neutral, with AVWAP the lone positive, consistent with a stock that has stabilized without regaining its longer-term footing.
The bottom line is that Suburban delivered a cleaner balance sheet, a higher distribution and a sharply better RNG economic profile. It missed earnings expectations, posted a wider GAAP loss on impairments and showed a propane business that is treading water. With capex rolling off and coverage above 2x, the distribution looks well supported. Sustained earnings growth, however, now depends on tax-credit monetization, LCFS pricing and a heating season that must contend with sharply higher propane costs.
Read our earnings preview for Suburban Propane Partners, L.P.: https://www.earningswhispers.com/article/SPH/22895
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 6 hours | |
| Nov-04 | |
| Oct-22 | |
| Oct-21 | |
| Sep-10 | |
| Aug-25 | |
| Aug-06 | |
| Aug-03 | |
| Jul-23 | |
| Jul-22 | |
| Jun-30 | |
| Jun-23 | |
| May-07 | |
| Apr-23 |
