Nuwellis Cuts Costs And Files Pediatric 510(K), But Flat Sales, Slowing Console Placements And Dilution Remain The Core Problem
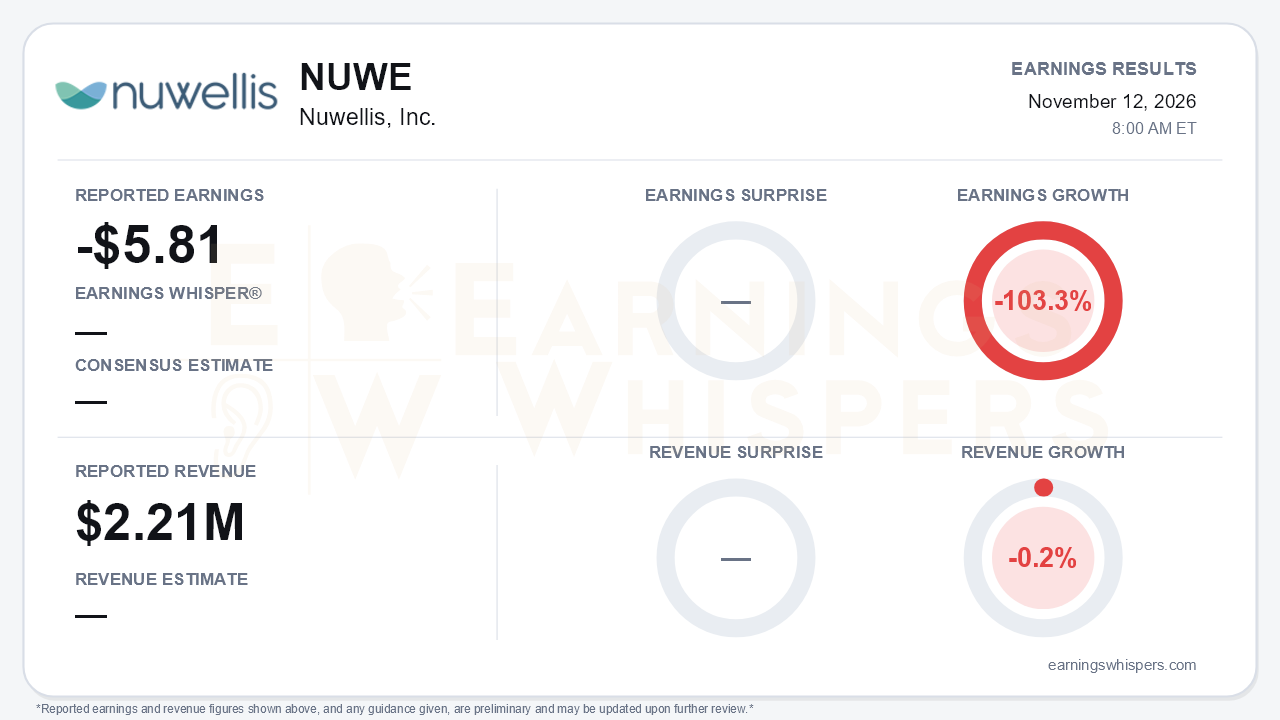
Nuwellis (NASDAQ: NUWE) reported a third-quarter loss of $5.81 per share on revenue of $2.21 million. Earnings fell 103.3% year over year, and revenue slipped 0.2%. No consensus estimate or Earnings Whisper was available, so there is no beat or miss to judge. The earnings comparison is distorted. The prior-year quarter showed net income of about $0.5 million, or $177.16 per share, because of a $3.2 million noncash gain on warrant liabilities. This quarter's $2.0 million net loss is therefore a swing back to red rather than a true deterioration. The quarter's central tension is that Nuwellis materially improved its cost structure and regulatory pipeline while top-line momentum stalled.
The operating line tells the cleaner story. Loss from operations narrowed 24% to $2.1 million from $2.7 million. Gross margin expanded to 69.5% from 65.2% a year earlier, helped by higher average selling prices and the contract manufacturing model. Total operating expenses fell to $3.6 million from $4.1 million a year earlier. The sequential trend is more striking: about $6.0 million in Q1, $4.7 million in Q2 and $3.6 million now. That matches the company's earlier plan to roughly halve monthly burn by the fourth quarter. The quality of the margin story still deserves scrutiny. Gross margin fell back from 76% in Q2, and year-to-date operating cash burn of $9.3 million actually exceeded the $7.8 million used in the prior-year period.
Revenue is where the bears have legitimate ammunition. Year-over-year growth has decelerated from 26% in Q1 to 14% in Q2 to essentially zero in Q3. Year-to-date growth cooled to 13% from 20% at the half-year mark. Management attributed the flat quarter to a $0.4 million backorder fulfilled in the prior-year period, and it pointed to 20% pediatric growth (26% year-to-date) as evidence of underlying momentum. Sales did rise 12% sequentially. The console trend is harder to explain away, however. Nuwellis sold eight Aquadex consoles in Q3, down from 15 in Q1, nine in Q2 and 12 a year ago. The 88% year-to-date increase to 32 units, which led the press release, was built largely in the first quarter. Management's thesis is that console placements seed recurring circuit revenue. If so, slowing placements matter for future quarters, not just this one. Management gave no formal guidance and did not restate the "consistent double-digit revenue growth" objective it voiced on the Q2 call. No analysts asked questions.
The forward-looking developments were constructive and mostly delivered on schedule. Nuwellis submitted its 510(k) on November 5 to lower the Aquadex pediatric weight threshold from 20 kilograms to 5 kilograms, meeting the fourth-quarter timeline it promised in Q2. The ULTRA-Peds registry, covering 91 patients with 87% survival, was accepted for publication in Pediatric Nephrology, adding clinical support. The company also used its existing sales force to add two products: a co-promotion deal for Atrility's AtriAmp cardiac rhythm monitor and exclusive U.S. rights to the pediatric Zorro-Flow urine collection system, which is expected to launch in Q1 2027. Smart View now carries a Q1 2027 launch target and Pressure IQ an H1 2027 target. Clarity Prime is moving the other way. It was a mid-2026 relaunch, then a 2027 launch, and is now described only as continuing to advance, with no date.
The balance sheet improved, but the financing behind it is the real risk. Cash rose to $8.3 million from $3.9 million in Q2 and $2.2 million in Q1. The increase was funded by a $3.4 million registered direct offering, $3.3 million in warrant exercises and $1.4 million from the at-the-market program. Even so, management puts the runway only through Q2 2027, which implies more capital raises. The dilution is already severe: shares outstanding rose to roughly 541,000 from about 5,300 at the end of 2025. The market has priced this in. Shares opened at $1.38 after the August report, against a 200-day moving average of $214.90, a gap that reflects a punishing, dilution-heavy repricing over the past year. No current sentiment reading or post-report price data was available to judge the immediate reaction.
The bottom line is that Nuwellis executed well on what it controls, including cost cuts, margin gains versus last year, a timely 510(k) filing and capital-light portfolio additions. It has not yet shown that the commercial engine can grow on its own. Flat revenue, declining quarterly console placements, a dropped growth objective and a runway that ends mid-2027 leave the investment case dependent on pediatric label expansion and new product launches arriving before the next financing round further dilutes shareholders.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-10 | |
| Nov-05 | |
| Nov-04 | |
| Oct-27 | |
| Oct-08 | |
| Oct-01 | |
| Sep-17 | |
| Sep-17 | |
| Sep-16 | |
| Sep-09 | |
| Aug-25 | |
| Aug-13 | |
| Aug-13 |
