LiqTech Edges EPS Estimate But Misses Badly On Revenue, Leaving Its Guidance On A Steep Fourth-Quarter Ramp
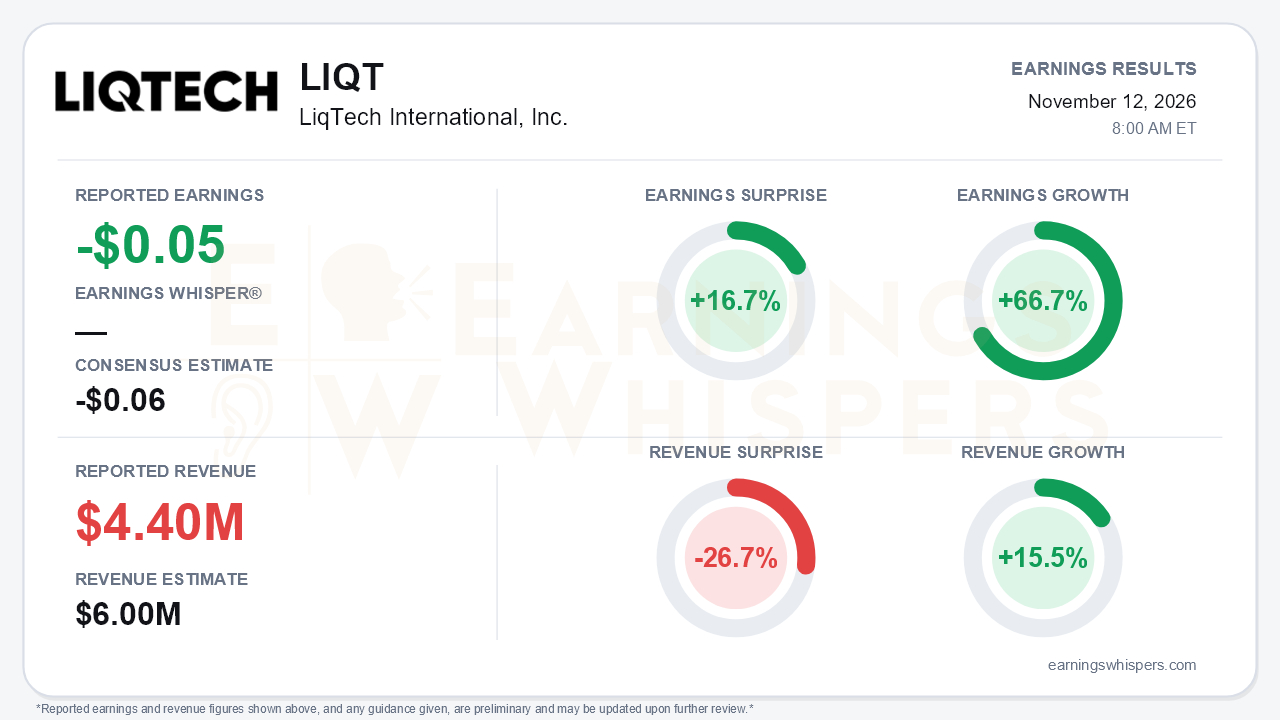
LiqTech International (NASDAQ: LIQT) posted a third-quarter loss of $0.05 per share, a penny better than the -$0.06 consensus. That is a 16.7% earnings surprise and a 66.7% year-over-year improvement in per-share results. The top line tells a less comfortable story. Revenue of $4.4 million rose 15.5% from a year ago but missed the $6.0 million consensus by 26.7%, and it was flat with the second quarter. The company reaffirmed full-year revenue guidance of $20 million to $23 million. That is the central tension: management is holding a target that requires a dramatic fourth-quarter acceleration from a business that has not yet shown it can grow sequentially.
The quality of the EPS beat deserves scrutiny. The per-share improvement is almost entirely a function of dilution. Weighted-average shares rose to 38.2 million from 14.9 million a year earlier. Meanwhile, the GAAP net loss attributable to LiqTech widened to $1.84 million from $1.43 million. Adjusted EBITDA also deteriorated year over year, to -$1.1 million from -$0.5 million. Gross margin fell to 12.3% from 19.6%, which the company attributed to a mix shift toward lower-margin Marine systems and weaker capacity utilization than in a prior-year quarter boosted by safety-stock production. Selling expenses nearly doubled (+93.7%) as LiqTech built out its commercial team and U.S. Service Center. Over nine months, revenue is actually down, at $12.9 million versus $13.4 million in the same period last year.
The sequential picture is where the bull case lives. Gross margin improved from 8.4% in the second quarter and 9.5% in the first. The net loss narrowed to $1.8 million from $3.1 million, and adjusted EBITDA improved from -$1.6 million. Operating expenses fell 13.4% quarter over quarter, though part of that came from moving the annual general meeting into the fourth quarter, a cost that has been deferred rather than eliminated. Other expense dropped to $55,000 from roughly $720,000 in the second quarter after the company retired its debt.
At the segment level, results were mixed:
- **DPF:** revenue rose to $1.1 million, the raw-material constraint is resolved, and year-to-date orders are up 30%.
- **Marine:** revenue reached $0.9 million, up from $0.7 million in the second quarter and $0.5 million a year earlier, helped by a third iCER delivery and a new two-unit order from an existing scrubber customer.
- **Commercial pool:** revenue slid to $0.8 million from a record $1.5 million in the second quarter.
- **Plastics:** revenue softened to $0.7 million, although management says fourth-quarter orders are stronger.
The forward setup hinges on execution. LiqTech needs roughly $7.1 million in fourth-quarter revenue to reach the low end of guidance and about $10.1 million for the high end. That is 60% to 130% above the third-quarter run rate. The high end also depends on Water for Energy orders that have not been signed. Several factors support the ramp:
- Two completed scrubber systems slipped into the quarter on customer acceptance timing.
- The $2.1 million steel-industry QureFlow order is being recognized on a percent-of-completion basis.
- The first EGR system and the Freeport QF-6 system are both slated for fourth-quarter delivery.
Management indicated that EBITDA breakeven sits around $8 million to $10 million in quarterly revenue and could be reached in the fourth quarter. It also floated 30% to 40% growth for 2027, explicitly labeled as a preliminary view rather than formal guidance. Bears have legitimate ammunition. Current guidance already reflects a cut from the original $23 million to $27 million range, earlier targets such as positive full-year adjusted EBITDA are effectively out of reach, management will not disclose backlog size, and CFO/COO David Kowalczyk departs November 30. Cash fell to $13.9 million from $15.7 million. That decline includes repaying the May bridge loan, so it overstates operating burn somewhat, but the company remains loss-making.
Investor sentiment improved meaningfully heading into the report, rising from -0.63 to -0.16. Sentiment is still negative, but it is far less pessimistic than after the August report. The stock has not followed. Shares closed at $0.31 before the release, down 54.9% from the $0.69 open after the prior report and 72.3% below the 200-day moving average of $1.12. The stock set a 52-week low of $0.25 on November 5. It sits 62% below its September inter-earnings high of $0.82 and only modestly above that low. Earnings Whispers momentum and AVWAP trend readings remain negative.
The bottom line is that LiqTech delivered a cosmetic EPS beat and genuine sequential margin and cost progress, but the revenue miss and the flat quarter-over-quarter top line leave the reaffirmed guidance resting on an unusually back-end-loaded fourth quarter. Sequential improvement and a debt-free balance sheet keep a credible path to breakeven alive. However, with dilution, leadership turnover, undisclosed backlog and a deeply depressed share price, the fourth quarter is now a show-me period in which delivery timing will matter more than pipeline promises.
Read our earnings preview for LiqTech International, Inc.: https://www.earningswhispers.com/article/LIQT/22996
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 5 hours | |
| Nov-11 | |
| Nov-10 | |
| Nov-06 | |
| Nov-05 | |
| Oct-20 | |
| Oct-06 | |
| Sep-17 | |
| Sep-01 | |
| Aug-12 | |
| Aug-12 | |
| Aug-11 | |
| Aug-11 | |
| Aug-10 |
