Fermi Trades A Dead $6.5 Billion Lease For A Larger But Unsigned Hyperscaler Deal As Shares Sit Near Lows
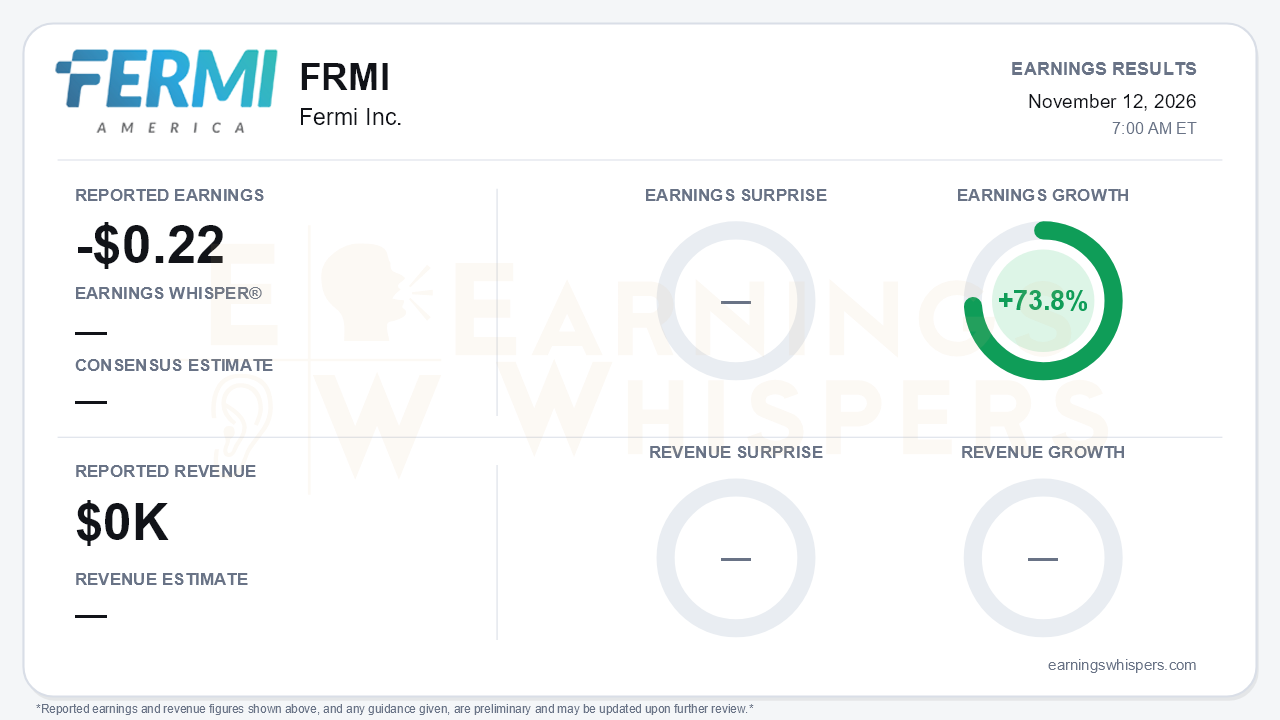
Fermi's third-quarter numbers matter less than the tenant swap underneath them. The pre-revenue power and data center developer reported a loss of $0.22 per share, compared with $0.84 a year earlier, which Earnings Whispers calculates as 73.8% earnings growth. There was no consensus estimate to measure against. The real news is that Fermi's first binding tenant is gone. TensorWave's 650 MW lease, framed last quarter as worth roughly $6.5 billion over a 15-year initial term, has been terminated. It was replaced by a larger-sounding but still pre-definitive 600 MW arrangement with an unnamed investment-grade hyperscaler. That is the central tension: a better counterparty, a less certain contract.
The quality of the narrower loss deserves scrutiny. The year-ago quarter carried $309.0 million of other expense tied to fair-value remeasurements and a share-based charitable contribution. Remove that distortion and the operating picture moved the other way. General and administrative expense jumped to $142.2 million from $37.8 million. That total included $65.8 million of non-cash stock compensation and $21.5 million of advisory fees paid in stock.
The balance sheet has also changed character:
- Net debt rose to $958.4 million from $109.8 million at year-end.
- Capital invested in property, plant and equipment reached $759.5 million year to date, lifting the net balance to about $1.67 billion.
- Cash and restricted cash fell to $315.5 million.
Fermi is now a leveraged development story, and every quarter without a signed lease costs real money. The call put third-quarter operating cash burn at $54.5 million, versus roughly $7 million in the first quarter, plus about $25 million in amendment fees to turbine lenders.
The call did preserve a credible commercial narrative. The hyperscaler committed to a $200 million prepayment, with the wire due November 13, the day after the report. It also signed a $15 million early construction agreement and is finalizing a roughly $90 million purchase of steel Fermi had pre-bought. Site mobilization is targeted for December 1. Management pulled first power forward to late Q2 or early Q3 2027, ahead of the TensorWave rent start previously guided for late Q3 or early Q4 2027.
Capex discipline is visible. Spending stepped down from $441 million in Q1 to $185 million in Q2 and $133 million in Q3. Management's tone was notably more confident. It argued the pipeline of investment-grade hyperscalers could fill the full 2.2 GW of current capacity, with a strategy of anchoring the campus with four or five such customers.
Bears have legitimate ammunition, however.
- **Weaker deal economics.** The new deal uses a Powered Land Plus model, in which the customer funds its own data centers. That structure produces materially less revenue per MW than the turnkey TensorWave structure; per the call, turnkey earns about 2.4 times the revenue for about 3 times the capital.
- **Thin disclosure.** No lease economics, capex split or yields were disclosed, and the customer remains unnamed.
- **Missing references.** The Hillcore 2.6 GW alliance and last quarter's 4.8 GW figure went unmentioned.
- **Worse backdrop.** The macro environment has deteriorated, with an ERCOT large-load connection freeze, a Texas air-permit pause, state moratoria and tighter high-yield credit.
- **Texas Tech deadline.** The land lease requires a 200 MW lease and notice to proceed by December 31, 2026, and meeting it still depends on converting the hyperscaler agreement into a definitive lease.
One genuine positive here is the amended turbine facility. It removed the November 10 lease deadline and the lenders' right to market the turbines, easing an overhang that could otherwise have forced a distressed outcome.
The market had already rendered a harsh verdict before the report. Shares opened at $7.10 after the August release and closed at $1.81 on November 11, a 74.5% decline. The stock hit a 52-week low of $1.44 on November 5 and sits about 71% below its 200-day moving average of $6.17. The rebound of roughly 26% off that low suggests some investors anticipated a replacement tenant. Even so, the stock remains near the bottom of its inter-earnings range, about 75% below the August 13 high.
Investor sentiment swung from slightly positive at 0.0756 to clearly negative at -0.3945. That is a meaningful deterioration, consistent with the TensorWave collapse and financing worries. The trend readings are mixed, with momentum positive while AVWAP remains negative, reflecting a stock trying to stabilize after a severe drawdown.
The setup is more complicated than the narrower loss implies. Fermi arguably upgraded its customer quality and gained an upfront cash cushion. In exchange, it gave up a signed contract with defined revenue for a promise with undisclosed terms and lower per-MW economics. Near-term proof points are unusually concrete:
- receipt of the $200 million wire;
- a December 1 mobilization;
- a definitive lease before the Texas Tech deadline.
The bottom line is that Fermi's quarter was about counterparty risk, not earnings. The headline improvement in the loss is largely a year-ago accounting artifact, while cash burn and leverage have climbed. A hyperscaler writing a $200 million check is a real validation of Project Matador's speed-to-power pitch. Until it becomes a signed lease with disclosed economics, though, the stock's collapse and souring sentiment reflect a market that has learned not to count tenants before the paper is final.
Read our earnings preview for Fermi Inc.: https://www.earningswhispers.com/article/FRMI/22877
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-05 | |
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Oct-21 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-12 |
