EnerSys Edges Consensus But Misses The Whisper As Orders Surge And Material Handling Slips Again
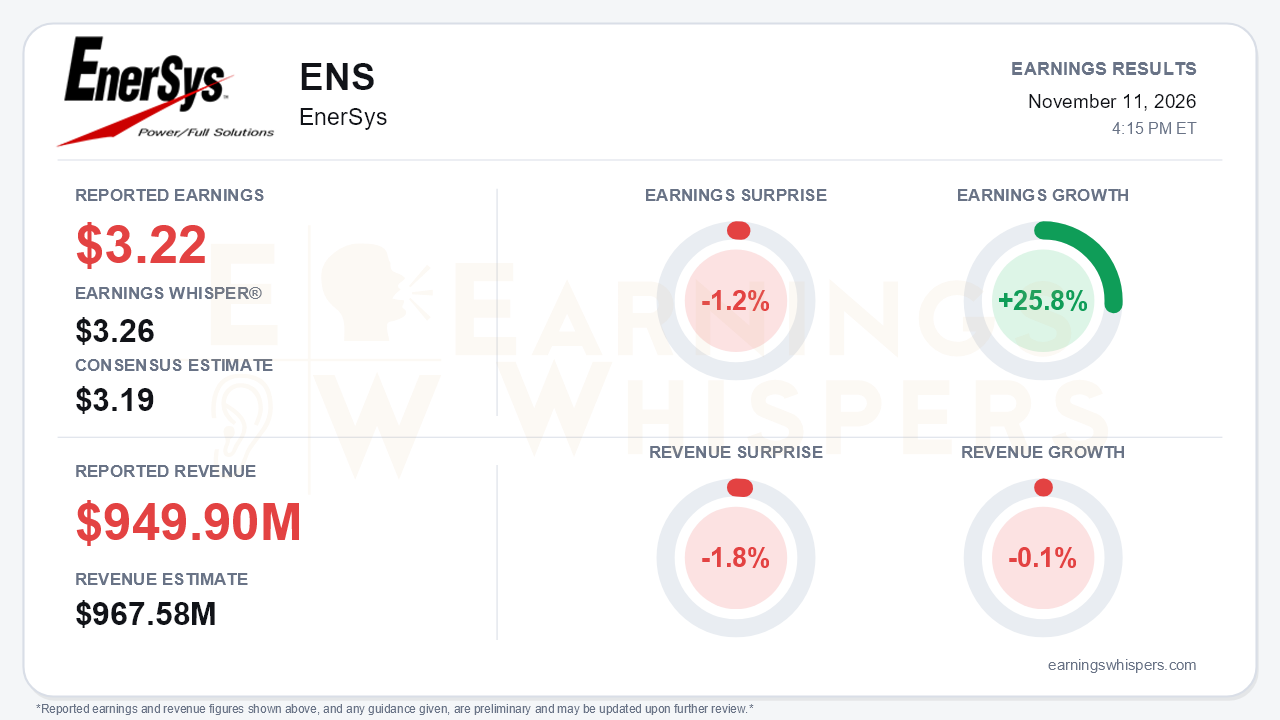
EnerSys (NYSE: ENS) delivered a quarter in which orders are improving while near-term revenue weakens. Adjusted EPS of $3.22 topped the $3.19 consensus but fell short of the $3.26 Earnings Whisper number, a 1.2% miss against the expectation that mattered more to investors. Revenue of $949.9 million missed consensus by 1.8% and was essentially flat year over year (-0.1%). It also landed below the company's own $955-$995 million guidance range, which management attributed to foreign currency translation. Earnings grew 25.8%, but revenue growth decelerated from roughly 5% in the first quarter to zero. Orders, backlog and new defense business all improved, yet the revenue line has stalled and the outlook steps down. That is the central tension.
The quality of the earnings growth deserves scrutiny. GAAP EPS rose to $2.42 from $1.80, and gross margin expanded 80 basis points to 29.9%. However, the IRC 45X manufacturing credit supplied $44.4 million of gross profit, up from $39.6 million. Excluding 45X, gross margin improved only 30 basis points to 25.2%. Below gross profit, operating expenses fell to $148.2 million from $164.1 million, a meaningful contributor to the earnings gain. Buybacks also helped: diluted shares fell to roughly 37.0 million from 38.0 million after $130 million of repurchases in the quarter. On the call, management cited adjusted EPS of $3.26 excluding a small tariff-refund charge, which matches the whisper. Investors, though, received the reported $3.22. Cash generation was a genuine positive. Year-to-date free cash flow reached $348 million, up $183 million, and net leverage fell to 0.8x from 1.3x.
The segment picture shows a portfolio pulling in opposite directions:
- **Precision Power Solutions:** sales grew 21% to $104 million, and adjusted operating margin rose to 21.9% from 18.2% in the first quarter, on soldier power and munitions demand.
- **Network and Infrastructure Solutions:** sales grew 3% against a tough comparison, with double-digit data center growth. Adjusted margin improved sequentially to 11.2% from 10.5%.
- **Industrial Mobility Solutions:** sales fell 7.8%, worse than the roughly 3% decline in the first quarter, and adjusted operating earnings dropped 13.4%.
The material handling recovery has now slipped again. Earlier calls pointed to full-year IMS growth. Management now expects a return to growth only by fiscal year-end, with recovery arriving in the fourth quarter.
The call nonetheless preserved a credible growth story built on forward indicators:
- Orders rose 21% year over year versus 7% in the prior quarter.
- Book-to-bill improved to 1.09.
- Backlog jumped 36% after being roughly flat a quarter earlier.
- PPS orders tripled.
- Transportation orders rose 60%.
- A $50 million multi-year European soldier power order was secured.
New products are also reaching customers. EnerSys booked its first DataSafe Noir lithium order, against a pipeline of about 80 opportunities, and recorded first revenue from its second-generation material handling lithium battery. The proposed roughly $320 million Ultralife acquisition, expected to close in the fourth fiscal quarter, would deepen the defense platform. Management cites $15-$20 million of run-rate synergies and EPS accretion within about 18 months.
Bears still have legitimate ammunition. Third-quarter guidance calls for sales of $935-$975 million and adjusted EPS of $3.05-$3.15. Earnings Whispers characterizes that guidance as in line, but both ranges sit below the second-quarter guide. Per the call analysis, the midpoint implies roughly 12% EPS growth versus about 21% for the second-quarter guide. The CFO flagged margin pressure from several sources:
- tough PPS and NIS comparisons after unusually strong prior periods;
- an IMS mix shift toward lower-margin transportation;
- freight and commodity inflation that may take a quarter to recapture.
Data center order growth cooled to the mid-teens from about 80% in the first quarter. Management also raised the risk that greenfield data center construction could slow after the midterm elections. In addition, the company stopped guiding 45X separately, which reduces visibility into how much of the earnings base depends on the credit.
The market has already turned decisively. Shares are down 30% since opening at $211 after the August report and now trade near $147.65, about 22.7% below the 200-day moving average of $191.03. Investor sentiment collapsed from a solidly positive 0.46 to roughly neutral at -0.04, one of the larger swings the scale allows. Price and AVWAP trend readings remain negative. That suggests the slower revenue trajectory was partly anticipated, and that a modest beat against consensus was not enough to restore lost confidence.
The bottom line is that EnerSys is building a stronger order book, a growing defense franchise and a cleaner balance sheet, but those gains have not yet reached revenue. A repeated delay in material handling and a sequentially softer outlook left the whisper-level bar unmet. Investors now need backlog conversion and evidence that the IMS recovery actually arrives in the fourth quarter before the improving forward indicators can offset a stalled top line.
Read our earnings preview for EnerSys: https://www.earningswhispers.com/article/ENS/22830
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Nov-11 | |
| Nov-11 | |
| Nov-11 | |
| Nov-11 | |
| Nov-03 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-21 | |
| Oct-14 | |
| Oct-01 | |
| Sep-29 | |
| Sep-29 | |
| Aug-31 |
