Lucid Diagnostics Matches The Whisper But Misses On Revenue As Medicare Payments Reset The Story, And Dilution Raises The Price Of Admission
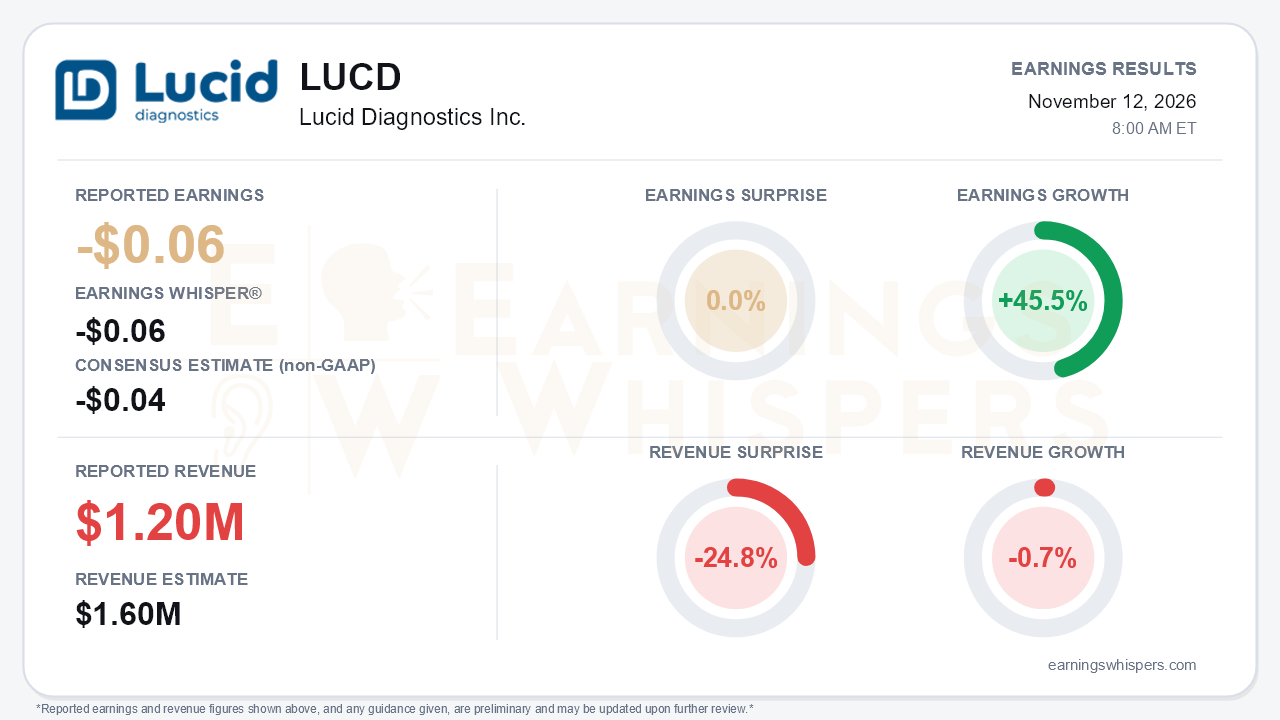
Lucid Diagnostics' third quarter was weak on paper and transformational in substance. The company reported a non-GAAP loss of $0.06 per share, exactly matching the Earnings Whisper number but wider than the -$0.04 consensus. Revenue of $1.2 million missed the $1.6 million consensus by 24.8% and slipped 0.7% from a year ago. Yet the numbers that matter most arrived after the quarter closed. Medicare began paying for EsoGuard in October at the full $1,938.01 Clinical Laboratory Fee Schedule rate, and October test volume set a record of more than 1,800. That is the central tension. The reported quarter belongs to the old Lucid, but the investment debate now belongs to a company whose biggest external constraint has been substantially lifted, and whose shareholders are paying heavily to fund the transition.
The quality of the quarter deserves scrutiny. Per-share earnings improved 45.5% year over year, but the non-GAAP adjusted loss widened slightly in dollar terms, to $10.6 million from $10.3 million. The per-share gain came largely from a share count that rose to roughly 191 million from 108 million. The GAAP loss of $0.03 per share looks even better, but it was flattered by a $5.5 million non-cash gain on the fair value of convertible debt. On the cost side, the news was more encouraging. Non-GAAP operating expenses fell to $11.8 million from $12.3 million in the second quarter, even as sales and marketing spending rose year over year to support the commercial push. Revenue declined sequentially from $1.5 million, which management attributed to timing. Direct-contract tests dropped to 60 from 517, masking a steady test base of 2,871.
The call made a credible case that the business has inflected. After management said in three consecutive quarters that a MolDX draft LCD was imminent, Lucid sidestepped the wait. It submitted claims to Novitas, the Medicare contractor covering its Texas lab, through claim-by-claim adjudication, and those claims have been paid weekly since October. More than 300 Medicare tests in October alone equal about 70% of the roughly 450 performed in all of the third quarter. Payer quality is also improving:
- The average allowable per successful claim rose to $1,701 from $1,424.
- The share of adjudicated claims with an allowable amount climbed to 39% from 28%.
- Year-to-date revenue per test reached $446, versus $383 in fiscal 2025.
An accounting shift amplifies the change. Novitas claims can now be recognized at report delivery rather than on a cash basis, so improving volume should flow into reported revenue faster than before.
The supporting catalysts are broadening as well. The AGA's draft Barrett's esophagus guidelines name EsoGuard and EsoCheck as an endoscopy alternative with high certainty of evidence. The Concert policy is expected to reach five client health plans by year-end, up from three. The first two VA programs are live, and new CPT and ICD-10 codes should ease billing. Bears still have legitimate ammunition, however:
- Medicare coverage rests on claim-by-claim adjudication rather than a formal LCD, which remains stuck in a CMS backlog.
- Management offered no quantitative fourth-quarter or 2027 guidance, cautioned about holiday seasonality, and declined to extrapolate October's run rate.
- Medicare represented only about 16% of volume in the third quarter, against a target of 50% or more.
Financing is the sharpest cost of the turnaround. Cash fell to $18.0 million from $33.4 million in the second quarter before the $15 million Series C closed on October 21, leaving pro forma cash of about $33 million. That is roughly three quarters of runway at the $10 million to $11.6 million quarterly burn discussed on the call. The raise also reset the conversion price on about $22 million of notes from $1.00 to roughly $0.35 and carries a 20% PIK dividend. Fully diluted shares now stand near 330 million.
The market has priced that dilution aggressively. Shares fell 61.1% from the $0.98 opening after the August report to $0.38 heading into this release, sitting about 62% below the $0.99 200-day moving average. The stock hit a 52-week low of $0.30 on October 22, the day after the Series C closed, and has since recovered about 26% off that level. Investor sentiment improved only marginally, from -0.83 to -0.80, and remains deeply negative. The Earnings Whisper trend readings reflect the same split, with sequential growth positive while price and AVWAP trends remain negative.
The bottom line is that Lucid delivered a soft quarter and a revenue miss, but it also cleared the reimbursement hurdle that has defined the story for more than a year. The next two quarters will show whether October's record volume and full-rate Medicare payments convert into visibly accelerating revenue. That conversion has to arrive before the cash runway and the steadily expanding share count erode what remains of the upside for existing shareholders.
Read our earnings preview for Lucid Diagnostics Inc.: https://www.earningswhispers.com/article/LUCD/22882
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Oct-30 | |
| Oct-29 | |
| Oct-22 | |
| Sep-22 | |
| Aug-14 | |
| Aug-13 | |
| Aug-13 | |
| Aug-12 | |
| Aug-05 |
