Cellebrite's Profit Beat-And-Raise Masks Another Revenue Trim As Recovery Stays Margin-Led
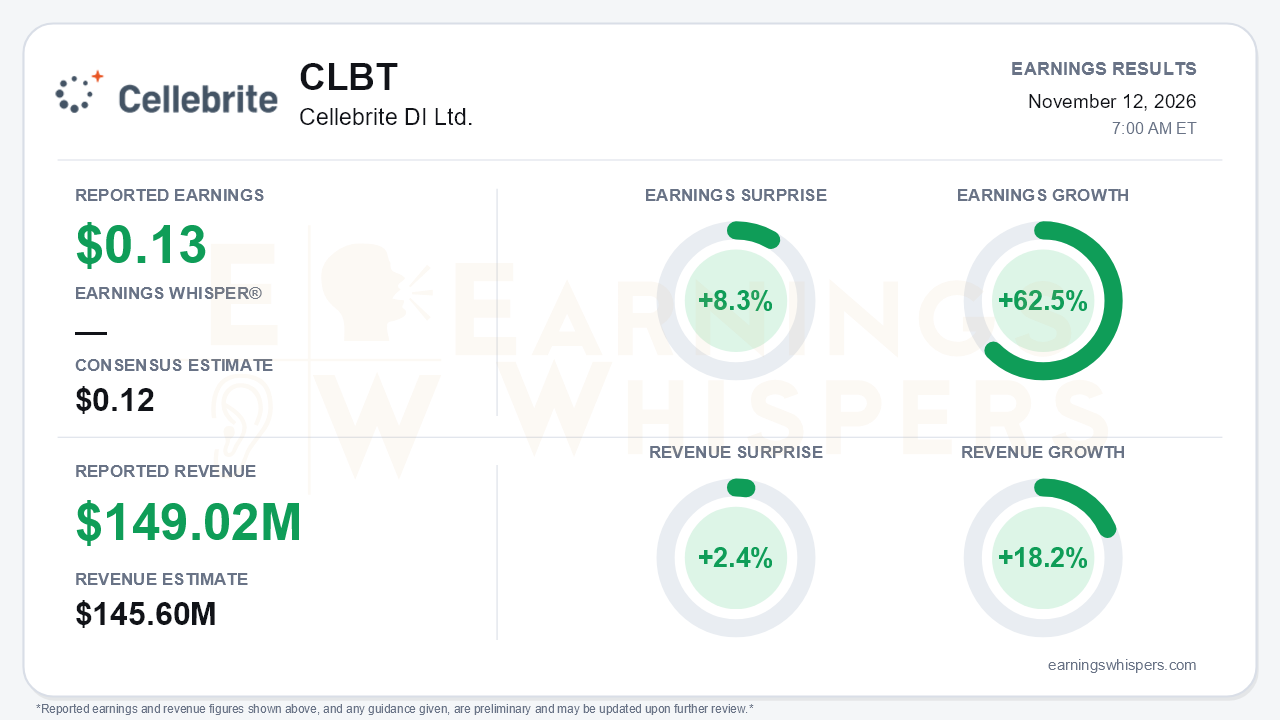
Cellebrite DI Ltd. delivered the clean quarter investors needed after August's guidance cut and CEO change, though it did not fully reset the growth story. The company reported earnings of $0.13 per share on revenue of $149.02 million. EPS topped the $0.12 consensus by 8.3% and revenue beat the $145.6 million estimate by 2.4%. Earnings grew 62.5% year over year and revenue rose 18.2%. On the company's own terms, ARR of $528.5 million (+20%), revenue and adjusted EBITDA of $53.6 million all landed above the ranges management set on the Q2 call. Management then raised full-year adjusted EBITDA guidance for the second time this year. Yet the revenue outlook was trimmed again, and the ARR target was merely held. That is the central tension: this is an execution and profitability recovery, not a re-acceleration of the top-line outlook.
The quality of the beat is mostly genuine, but it deserves some scrutiny. The normalized $0.13 figure sits between GAAP diluted EPS of $0.10 and the company's non-GAAP $0.17. The gap reflects $15.4 million in share-based compensation and a jump in intangible amortization to $7.2 million from $0.9 million, largely tied to acquired assets. That amortization also explains why GAAP gross margin slipped to 81.2% from 83.9%, while non-GAAP gross margin held at 85.7%. The operating leverage is real. Sales and marketing spending actually fell year over year, while R&D rose about 29%, and adjusted EBITDA margin expanded to 36.0% from 29.9%. Third-quarter free cash flow of $51.8 million (34.8% margin) was strong, but it was helped by a $33.4 million build in deferred revenue. Nine-month free cash flow margin of 20.4% is actually below last year's 22.3%. The reiterated ~30% full-year target therefore leans heavily on a seasonally large fourth quarter.
The call showed improvement in several areas that had worried investors:
- **U.S. Federal:** Growth kept re-accelerating, from flat in 2025 to mid-teens in Q2 and 18% in Q3. Cellebrite also closed its largest Guardian win to date, its first large FedRAMP deal.
- **International:** EMEA grew 22% and APAC 31%.
- **Insights conversion:** Conversion reached roughly 75% of the installed base, up from 65% at Q2.
- **Genesis:** The agentic AI product reached $2 million of ARR, up from about $400,000 at the end of Q2. Management called it the best launch in company history and said it is being funded with incremental budget.
Management's tone shifted from Q2's contrite posture to confident, if measured.
The softer details explain why the top line didn't move higher. Full-year revenue guidance fell to $553-$558 million, from $555-$561 million in Q2 and $565-$571 million originally. Management attributed the cut to more ratable cloud and AI revenue and less hardware. The ARR range of $550-$560 million is unchanged but remains well below the original $567-$573 million, and management now has more confidence in the low end. Other weak spots include:
- **Americas:** Growth slowed to 17% from 19%.
- **Pathfinder:** Deals slipped into Q4 on hardware sourcing constraints.
- **Insights:** The final tranche of conversions should deliver lighter uplift.
- **Corellium:** The business disappointed, with limited new sales, higher churn and delayed renewals. Its contribution is below the 1-2 point ARR boost flagged in Q2, and the CFIUS review remains unresolved.
The Q4 revenue guide of $145-$150 million implies a flat-to-lower sequential quarter, and the 32%-33% EBITDA margin guide implies some compression from Q3.
The forward catalyst list is longer than the risk list, but it is mostly a 2027 story:
- U.S. redomiciliation targeted for the first half of 2027, aimed at reducing foreign-entity sales friction and opening index eligibility
- An on-prem Genesis version before year end
- A 2027 AI-native Genesis platform with tiered and consumption pricing
- Next-generation unlock and drone hardware
- A new strategy executive with an M&A focus
Bears have legitimate ammunition on Genesis monetization. Management acknowledged that consumption pricing is not yet fully accepted in law-enforcement procurement, and the funding source is uncertain. Shekel strength also remains a currency headwind.
The market setup is more complicated than the surprise implies. Shares hit a 52-week low of $9.58 on the day of the August report. They then rallied 23.1% from the post-report open to $12.70, finishing just 1.5% below the inter-earnings high heading into this release. Much of the recovery was therefore priced before the quarter printed. Even so, the stock remained about 4.2% below its $13.26 200-day moving average. Investor sentiment moved the other way: it was already negative and weakened further, from -0.17 to -0.29. Price has recovered faster than conviction, and the trend readings are mixed, with sequential growth improving while momentum lags.
The bottom line is that Cellebrite convincingly answered the execution question, with a broad beat, rising federal momentum, a second EBITDA raise and early Genesis traction. However, it left the growth question open. Another revenue trim, a low-end lean on ARR, Corellium's stumbles and a margin-heavy guidance mix mean the next leg depends on Genesis and the 2027 platform turning momentum into durable ARR acceleration.
Read our earnings preview for Cellebrite DI Ltd.: https://www.earningswhispers.com/article/CLBT/22868
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-09 | |
| Nov-05 | |
| Nov-04 | |
| Oct-20 | |
| Oct-06 | |
| Oct-02 | |
| Sep-28 | |
| Sep-23 | |
| Sep-17 | |
| Sep-14 | |
| Sep-14 | |
| Sep-08 | |
| Sep-04 |
