Star Equity Misses As Pro Forma Earnings Power Erodes, Leaving Backlog Gains And Asset Sales To Carry The 2027 Story
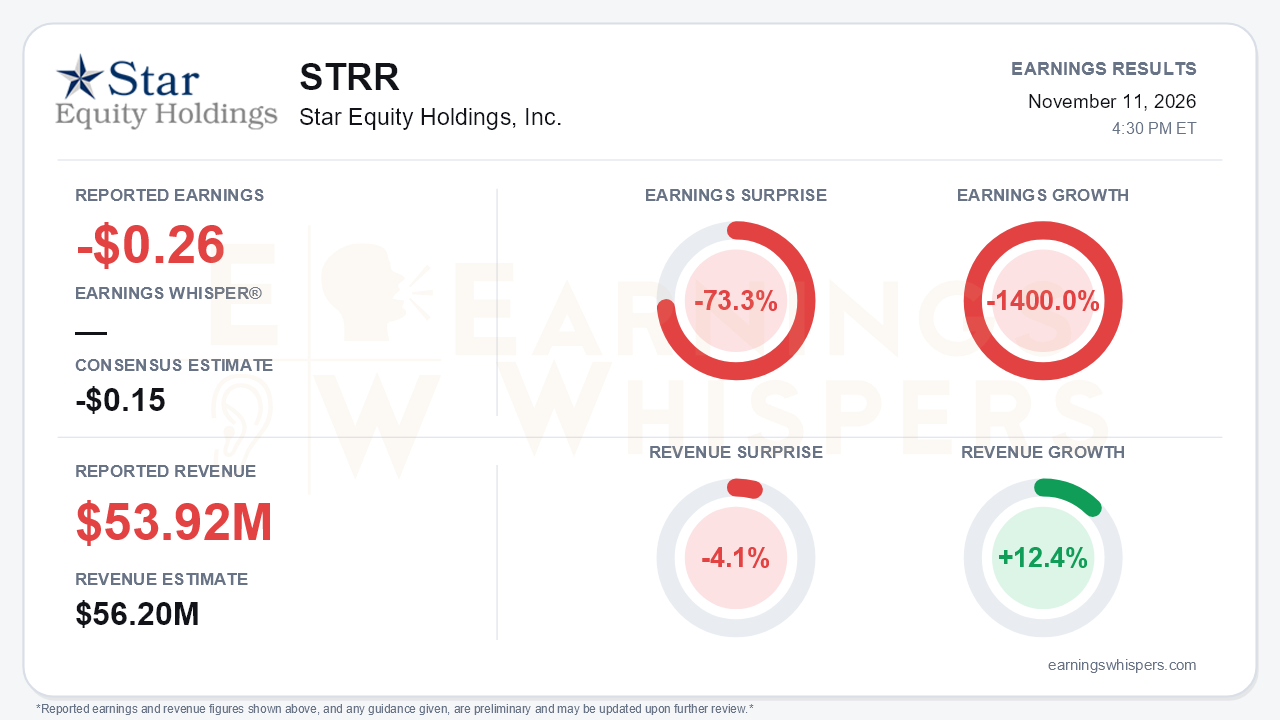
Star Equity Holdings (NASDAQ: STRR) delivered a third quarter that looks better on the surface than it does underneath. The diversified holding company reported an adjusted loss of $0.26 per share, missing the consensus estimate of a $0.15 loss by 73.3%. That compares with adjusted earnings of $0.08 a year earlier, a 1400.0% year-over-year decline that turned last year's small profit into a deeper loss. Revenue of $53.92 million rose 12.4% but missed the $56.2 million consensus by 4.1%. On a GAAP basis, the net loss attributable to common shareholders widened to $0.60 per share from $0.56. The central tension is that leading indicators are firming, while the earnings base the company built through its merger is shrinking, and the profit recovery keeps moving further into the future.
The quality of the revenue growth deserves scrutiny. The 12.4% increase reflects acquired Building Solutions and Energy Services operations that were in the year-ago results for only part of the quarter. Measured against a full-quarter pro forma base, prior-year revenue was $62.1 million, so the combined company is running below that level. Reported adjusted EBITDA edged up to $1.5 million from $1.3 million, but pro forma third-quarter 2025 adjusted EBITDA was $3.1 million. Year-to-date consolidated adjusted EBITDA is just $2.1 million. The capital structure adds pressure: preferred dividends now cost $615,000 a quarter, against $67,000 a year ago.
The weakness was broad. Business Services revenue fell 9% to $33.8 million after the loss of a contracting-only client. That reverses growth of 2% in Q2 and nearly 10% in Q1. Gross profit held up better, down only 2%, helped by 4% growth in the Americas. Division adjusted EBITDA still dropped to $1.0 million from $1.7 million as growth investment rose to $1.4 million, and the trailing 12-month EBITDA margin slid to 4.4% from 7.9% a year ago. Building Solutions was hit harder. Revenue fell to $16.3 million and adjusted EBITDA to $0.7 million, versus pro forma figures of $21.4 million and $2.6 million. Management cited soft residential and multifamily construction, and a large KBS project slipped to 2027 on permitting issues, although the company received a non-refundable deposit. Energy Services was the steadiest unit, with gross profit up 17% to $1.8 million. Even there, revenue growth slowed to 1% from 19% in Q2.
The call did preserve a credible set of forward indicators:
- Building Solutions backlog rose to $11.4 million, up from $10.6 million in Q2 and $8.0 million in Q1.
- Trailing book-to-bill improved to 0.86 from 0.72 two quarters ago, and new orders topped $17 million for a second straight quarter.
- Rolling four-quarter RPO new-logo contract value climbed to $12.9 million from $8.3 million.
- Operating cash flow turned positive at $0.9 million against $0.3 million of capex.
- Pro forma corporate costs fell on merger synergies.
The company also announced two bolt-on acquisitions: a Vernal, Utah machine shop and Cornerstone RPO, which adds U.S. enterprise relationships. It is pursuing sale-leasebacks expected to bring in more than $9 million in gross proceeds.
Bears have legitimate ammunition, however:
- Third-quarter adjusted EBITDA of $1.5 million is far from the roughly $8-10 million second-half consensus that management said earlier in the year it was comfortable with, and no numeric targets were reaffirmed.
- Management's tone has shifted toward 2027 and 'cautious optimism', including a hope for $20 million in quarterly orders by spring 2027.
- The Harte Hanks merger is now expected to close at the end of 2026 or in early 2027, rather than in the fourth quarter.
- Cash has fallen to $7.8 million from $13.4 million at year-end 2025, even as the company keeps buying back stock and making acquisitions.
- Management expects EMEA to stay soft and described housing as weak heading into 2027.
Investor sentiment improved ahead of the report, rising to -0.26 from -0.40, but it remains firmly negative. Price action has been harsher. Shares were at $8.79 before the release, down 18.3% from the opening price after the August report and 14.4% below the 200-day moving average of $10.26. The Earnings Whispers price and AVWAP trend readings remain negative. The sequential growth reading is positive, which fits the improving backlog and cash flow more than the reported profitability.
The bottom line is that Star Equity's quarter was a miss on both lines. Reported growth rested on acquisitions, while pro forma earnings power deteriorated in its two largest divisions. Rising backlog, better book-to-bill, new RPO wins, positive cash flow, and pending real estate proceeds give the 2027 recovery story some substance. Until those indicators translate into EBITDA, and the KBS project and Harte Hanks merger stop slipping, the burden of proof remains with management.
Read our earnings preview for Star Equity Holdings, Inc.: https://www.earningswhispers.com/article/STRR/22856
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-11 | |
| Nov-11 | |
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Oct-26 | |
| Oct-14 | |
| Sep-24 | |
| Sep-17 | |
| Aug-21 | |
| Aug-14 | |
| Aug-14 | |
| Aug-14 |
