SuperCom's Top Line Accelerates As Margins Crack: Q3 Revenue Growth Hits 20%, But EPS Falls A Third On FX, Expansion Costs And Dilution
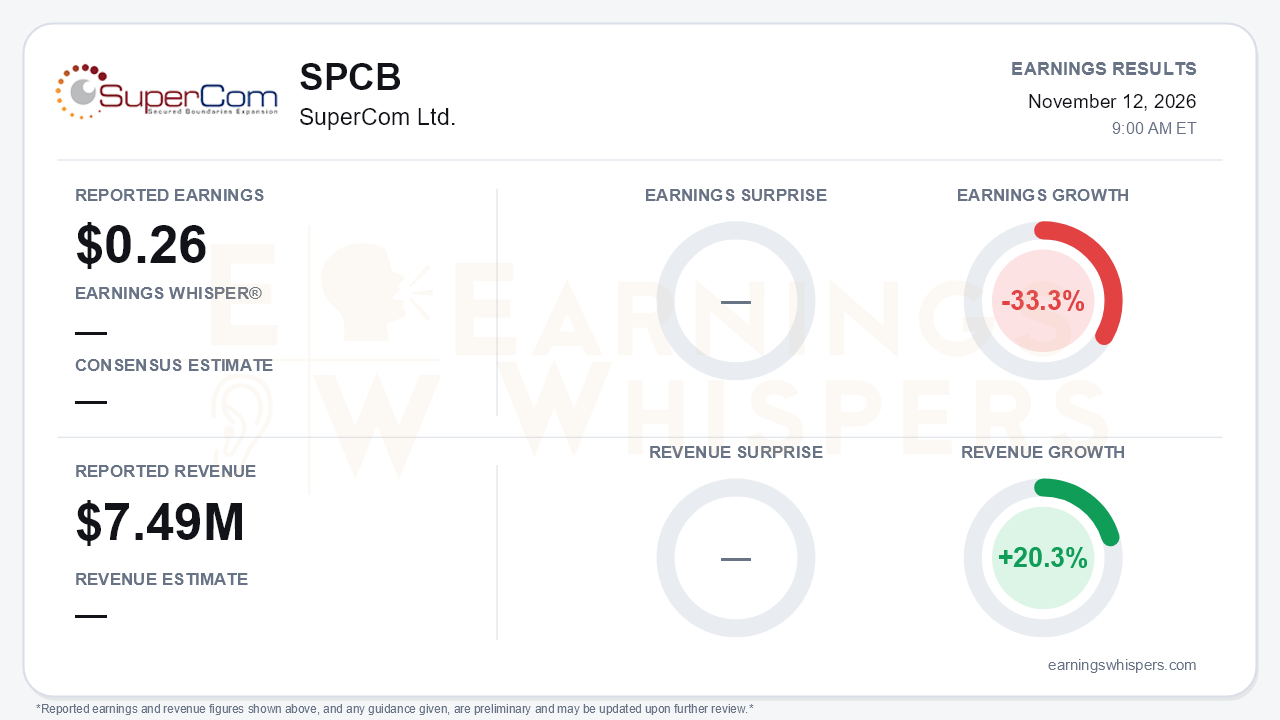
SuperCom delivered its fastest top-line growth of the year in the third quarter while posting its weakest profitability. Earnings Whispers puts adjusted earnings at $0.26 per share, down 33.3% from a year ago, on revenue of $7.49 million, up 20.3%. The company's own non-GAAP figure was $0.30. There is no consensus estimate or Earnings Whisper number, so the quarter cannot be judged as a beat or a miss. It has to be judged on its trajectory. Here the central tension is plain: year-over-year revenue growth accelerated from 8% in Q1 to 13.3% in Q2 to roughly 20% now, while nearly every profitability measure moved the other way.
The quality of the quarter deserves scrutiny.
- **Gross margin:** fell to about 49.8%, from 60% in Q2, about 63% in Q1 and 60.8% a year ago. Cost of revenues rose more than 50% against 20% revenue growth, and gross profit actually declined slightly year over year.
- **Operating expenses:** rose 28%. Selling and marketing jumped 70% on headcount additions that management tied to future growth.
- **Currency:** the shekel strengthened about 10% against the dollar. Combined with the higher spending, that produced a GAAP operating loss of $0.3 million versus $0.9 million of operating income in Q2, and a pretax loss of $0.6 million.
- **GAAP net income:** the reported $54,000 profit exists only because of a $670,000 income tax benefit.
- **Non-GAAP results:** non-GAAP net income was flat at $1.9 million, but only after adding back a $1.35 million foreign-currency loss. Per-share results fell further because the July equity raise expanded the share count.
- **EBITDA:** rose 20% year over year to $2.6 million but dropped sharply from $4.0 million in Q2. EBITDA margin fell to roughly 34% from about 49%.
Management's operating-leverage narrative did not show up in this quarter's numbers.
The demand picture is stronger than the margin picture.
- **U.S. contracts:** cumulative electronic monitoring wins since mid-2024 climbed from more than 45 to more than 50.
- **New states:** the count rose from 19 to 21 with Illinois and Indiana. Kansas, Michigan and a second Ohio contract also came in.
- **Texas:** five contracts since December 2025, every one displacing an incumbent. Another Texas award followed after quarter-end.
- **Recurring revenue:** U.S. quarterly recurring EM revenue rose about 255%, per the release.
That displacement record is the most persuasive evidence that SuperCom's technology wins on merit. Still, the call quietly removed some of the scaffolding investors had come to rely on. The Q2 call cited roughly 290% U.S. ARR growth, and this quarter offered no comparable ARR figure. The "record quarter" framing disappeared. As in prior calls, there was no formal guidance. Revenue also slipped sequentially from $8.1 million, a reminder that European ordering and recognition remain lumpy.
The balance sheet tells a story of capital-intensive growth.
- **Cash:** $12.9 million, up from $7.4 million in Q2. Measured against year-end, however, cash plus bank deposits rose less than $1 million despite $7.5 million in fresh equity.
- **Working capital and deployment:** long-term trade receivables grew to $12.9 million from $9.6 million, inventories rose by more than half, and other non-current assets jumped to $10.4 million from $2.5 million. That pattern is consistent with funding device deployments ahead of revenue.
- **Debt:** long-term borrowings sit near $19.8 million.
The upside case rests on the pipeline. The Swedish national contract carries a $17 million base and a budget of up to $75 million, a large England tender exceeds £150 million, and new orders from a European Ministry of Justice topped $3 million. Bears have legitimate ammunition, though. Each new contract appears to consume capital before it contributes margin, and the shekel exposure is structural rather than one-time for an Israel-based cost base.
SafeGenie is the new narrative wrinkle. The AI-agent security suite builds on Safend's endpoint base of 500,000 to 1 million endpoints, which currently generates roughly $1 million in revenue. Management floated revenue potential of up to about 50 times that base. That is an aspiration, not a forecast, and it arrives with demo requests and initial deployments only being prepared. Management positions it as complementary to electronic monitoring, but investors should weigh the risk of distraction for a small company already stretching to staff its U.S. expansion.
Market context is thin for this report. Shares opened at $10.71 after the August report, above a 200-day moving average now at $9.75. Current pricing and sentiment readings were not available, so it is unclear how much of the margin deterioration investors have already absorbed. What has changed is the burden of proof. The stock no longer gets credit simply for contract counts. It needs evidence that gross margin recovers toward the 60% range as deployments mature.
The bottom line is that SuperCom's growth engine is accelerating, but this quarter it ran less efficiently. Faster revenue growth, a widening U.S. footprint and repeated incumbent displacements support a credible expansion story. A 10-point gross-margin drop, a GAAP operating loss masked by a tax benefit, and dilution-driven EPS erosion argue that the company is paying heavily for that growth. Until margins and a quantified ARR trajectory reappear, the quarter reads as strong on demand and weak on economics.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-06 | |
| Oct-21 | |
| Oct-13 | |
| Oct-09 | |
| Sep-22 | |
| Sep-08 | |
| Sep-08 | |
| Aug-26 | |
| Aug-20 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 |
