OR Royalties Beats On Gold-Price Leverage, But Flat Ounces, Sequential Slide And Barnat Overhang Temper The Quarter
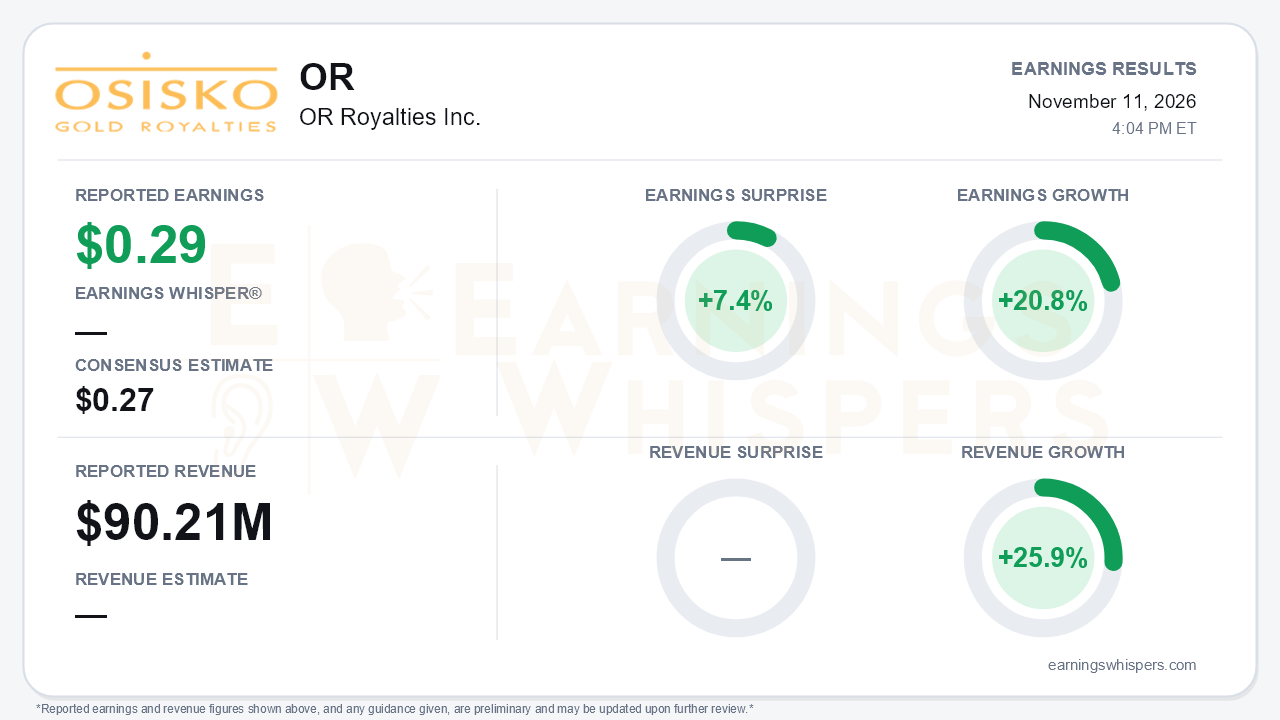
OR Royalties delivered a clean headline beat for the third quarter. Adjusted earnings came in at $0.29 per share, 7.4% above the $0.27 consensus and up 20.8% year over year. Revenue of $90.21 million rose 25.9%. The central takeaway, though, is that the growth came almost entirely from price rather than volume. Gold equivalent ounces earned were essentially flat at 20,237 versus 20,326 a year ago, while realized gold rose about 25%. CEO Jason Attew framed it as "what the model looks like when it works," and the 96.8% cash margin does convert nearly every incremental dollar of metal price into cash. But a quarter driven by price on flat ounces is a different kind of beat than one driven by production growth.
The quality of the quarter deserves scrutiny on several fronts.
- **GAAP earnings fell.** Net earnings dropped 33% to $0.30 per share. That decline is largely optical, because Q3 2025 included a $54.4 million non-cash gain on the deemed disposal of an associate.
- **Growth is decelerating.** Year-over-year revenue growth of 26% compares with 56% for the nine months, as the gold-price comparison toughens.
- **Revenue is sliding sequentially.** Revenue has fallen from a record $102.8 million in Q1 to $97.8 million in Q2 and $90.2 million in Q3.
- **Costs below the margin line are rising.** Depletion increased and finance costs climbed to $3.6 million from $0.9 million. That reflects the debt taken on to fund roughly $422 million of year-to-date acquisitions, mostly the Gold Fields portfolio.
- **The balance sheet has shifted.** The company ended 2025 with $142 million in net cash and now carries $151.5 million in net debt, up from $139 million at Q2.
The source materials also conflict on some figures. The call analysis cites Q3 operating cash flow of $67.6 million and realized gold of $4,204 per ounce. The release reports $77.6 million of operating cash flow and a $4,304 realized price. Both point to a sequential cooling from Q2, but the release figures are the reported numbers.
On the call, the operating story split cleanly in two.
**What improved:**
- The development pipeline is converting to production. Dalgaranga, Cuiú Cuiú and Amulsar all poured first gold in 2026, lifting producing assets to 25 from 23 at the Q2 call.
- Amulsar stream deliveries were pulled toward Q4 2027 or Q1 2028, versus the 2028 timing framed last quarter.
**What deteriorated:**
- **Barnat pit wall.** The disruption at Canadian Malartic is expected to cost roughly 3,000-4,000 GEOs in 2026, but up to about 7,500 GEOs per year in 2027 and 2028. That is a meaningful drag on the cornerstone asset that bears had reason to underestimate.
- **San Gabriel.** Management conceded the ramp is "a lot slower than we expected," with an 18-24 month timeline.
- **Timing slips.** Island Gold's shaft commissioning moved a quarter to mid-2027, and Amulsar's first gold slipped to October.
- **CSA shipment.** A shipment missed quarter-end cutoff for a second consecutive quarter, deferring silver and copper ounces into Q4.
There is also a timing discrepancy on Cuiú Cuiú. The release guides first royalty payments to Q4 2026 or Q1 2027, while the call analysis points to mid-2027.
The forward catalysts are substantive.
- **Windfall.** The project received its principal Québec environmental approval, and Gold Fields expects a final investment decision by February 2027. Windfall is projected at roughly 300,000 ounces a year, and OR holds a 2.0%-3.0% NSR.
- **Eagle.** Boroo's agreement to acquire the Eagle mine offers upside on a 5% NSR that, per the call, is carried at zero.
- **Q4 cash.** About $65 million of non-operating inflows should arrive: the $35 million Cascabel buyback and a $30 million Galiano deferred payment. That should begin reversing the net-debt build.
- **Guidance.** Management reaffirmed the 80,000-90,000 GEO range, tracking to about the midpoint, along with its 2030 outlook. Hitting the midpoint requires roughly 21,300 Q4 GEOs, about 5% above Q3, which the CSA deferral and new mines should help.
One strategic limitation surfaced as well. Management acknowledged it is unlikely to compete in $1 billion-plus upfront stream auctions against larger, lower-cost-of-capital peers.
Investor sentiment moved meaningfully. It swung from a mildly negative -0.18 at the prior report to a positive +0.25, a shift that suggests expectations rebuilt heading into this print. Shares are up 11.0% since opening at $32.06 after the August report, now at $35.60. Even so, the stock sits about 2.1% below its 200-day moving average of $36.36, so the rally has not fully repaired the longer-term trend. The Earnings Whispers trend readings are modestly constructive, with AVWAP positive and price trend neutral.
The bottom line is that OR Royalties beat because gold did the heavy lifting on a nearly frictionless margin structure, not because the portfolio grew ounces. Pipeline conversion, the Windfall approval and Q4 cash inflows preserve a credible growth story. However, the extended Barnat impact through 2028, slower ramps and a sequential decline in revenue give bears legitimate ammunition. With sentiment now positive and shares pressing toward the 200-day average, the setup leans more on gold prices and execution than the headline surprise implies.
Read our earnings preview for OR Royalties Inc.: https://www.earningswhispers.com/article/OR/22835
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| Nov-11 | |
| Nov-11 | |
| Nov-11 | |
| Nov-03 | |
| Oct-07 | |
| Sep-30 | |
| Sep-23 | |
| Sep-23 | |
| Aug-26 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-16 | |
| Jul-08 |
