Cohen & Company Misses Badly As $17.6 Million In SPAC Marks Erase Q3 Profitability; Founder-CEO Return Raises The Stakes
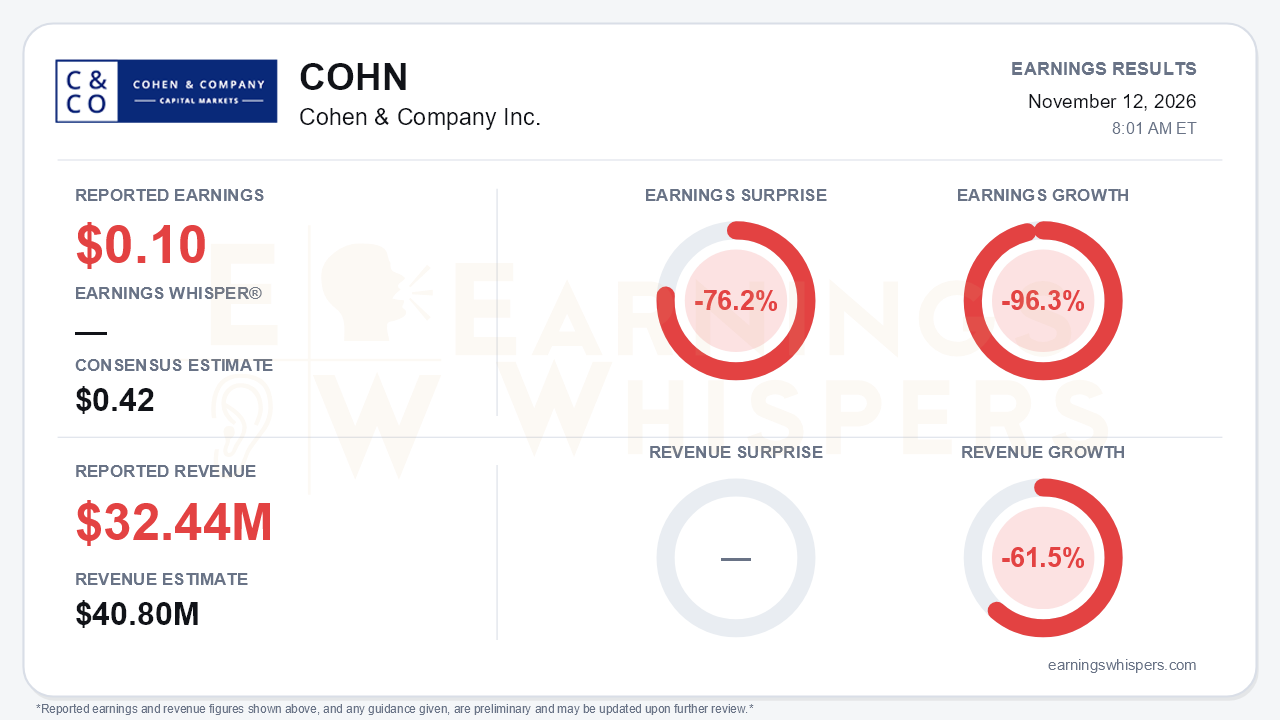
Cohen & Company's third quarter was defined by a swing in mark-to-market results on the securities its investment bank receives as fees, and that swing swamped everything else. Adjusted pre-tax income came in at $0.10 per share, far below the $0.42 consensus, a 76.2% miss. Earnings fell 96.3% from a year ago. Revenue of $32.44 million missed the $40.8 million estimate by 20.5% and fell 61.5% year over year. The central tension is that origination activity at Cohen & Company Capital Markets (CCM) remained healthy, but the value of what CCM is paid with deteriorated sharply. Investors were reminded how much of this earnings stream depends on SPAC and de-SPAC valuations.
The quality of the quarter deserves scrutiny in both directions. Investment banking and new issue revenue fell to $12.7 million, down from $54.1 million in Q2 and $68.6 million a year ago. That line absorbed $17.6 million of mark-to-market losses after $26.0 million of gains the prior quarter, a roughly $44 million reversal. Yet CCM underwrote six SPAC IPOs and a closed-end fund, raising $1.8 billion, and advised on eight de-SPACs. The GAAP picture is flattered rather than impaired. Net income attributable to the company rose to $6.7 million from $3.6 million in Q2, but pre-tax income was just $24,000. The increase came almost entirely from a $6.5 million deferred tax benefit tied to a valuation allowance release. Fully diluted GAAP EPS fell to $0.12 from $0.94. Variable compensation flexed down by $27 million sequentially, but non-compensation costs stayed near $8.7 million, held up by rising clearing and execution expense. As a result, operating income shrank to $2.6 million from $12.4 million.
Beneath the headline, the call delivered a more cautious read on demand than last quarter. The CFO said deals are closing more slowly than they were two quarters ago, a notable shift from Q2 commentary that pacing was similar. Management also characterized the SPAC IPO market as slow. Recurring businesses offered limited ballast:
- Net trading slipped to $12.5 million from $13.9 million, as weakness in SPAC equity, corporate, agency and structured notes desks offset mortgage strength.
- Asset management revenue continued a steady slide, from $2.7 million in Q4 2025 to $1.7 million.
The genuine bright spot was the gestation repo book. It climbed to a record $4.5 billion from $4.1 billion in Q2 and $3.9 billion in Q1. A $5.5 million principal gain on the Silvia (SVIA) position also helped, though that is market-driven rather than recurring.
The forward story now rests heavily on Daniel Cohen's return as CEO, following the abrupt resignation of Lester Brafman. Cohen laid out an aspirational target of more than $500 million in revenue over three to five years. That compares with $159.8 million through the first nine months of 2026. Management cited several initiatives behind that ambition:
- new at-the-market offering and private credit advisory practices, neither yet producing meaningful revenue;
- senior hires in energy transition and space technology;
- a novel pre-IPO AI investment vehicle it plans to replicate;
- a push to revitalize trading.
Nearer-term, management expects the Elroy Air combination with sponsored SPAC Inflection Point Acquisition Corp. 7 to close in Q4, which it framed as a significant revenue event. It also pointed to a pipeline of 45 underwritten SPACs carrying back-end fees, 13 with signed business combination agreements. There is no formal guidance, however, and the vision is unquantified on timing and margins. Bears have legitimate ammunition:
- leadership turnover;
- ongoing ATM issuance of 325,739 shares year to date;
- corporate debt rising to $31.4 million;
- continued dependence on volatile founder-share and warrant valuations.
The market had already been leaning bearish. Shares opened at $13.93 after the August report and stood at $11.00 the day before this release, a 21.0% decline. The stock sits about 19% below its 200-day moving average of $13.63. It peaked at $15.85 on the day of the last report, then slid to a 52-week low of $8.93 on October 23 before recovering roughly 23% off that trough. Investor sentiment, already negative, deteriorated further from -0.44 to -0.60. That suggests expectations were low, but not low enough to make this miss a non-event. The AVWAP trend reading remains negative, consistent with sellers retaining control since August.
The bottom line is that Cohen & Company's banking franchise is still generating deal flow and its repo and balance sheet metrics are improving, with enterprise equity up to $117.5 million and the $0.25 dividend maintained. Earnings power, though, proved highly exposed to SPAC valuation swings, and the reported GAAP profit owes more to a tax benefit than to operations. The founder-CEO's ambitious targets and a Q4 de-SPAC close give bulls a narrative. The burden of proof now shifts to converting the pipeline into revenue that holds its value at quarter end.
Read our earnings preview for Cohen & Company Inc.: https://www.earningswhispers.com/article/COHN/23080
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-10 | |
| Nov-09 | |
| Nov-05 | |
| Oct-27 | |
| Oct-05 | |
| Sep-24 | |
| Sep-23 | |
| Sep-21 | |
| Sep-17 | |
| Sep-02 | |
| Aug-18 | |
| Aug-10 |
