Nexxen Delivers A Margin Inflection, But Slowing Top-Line Growth And A Reaffirmed Guide Temper The Story
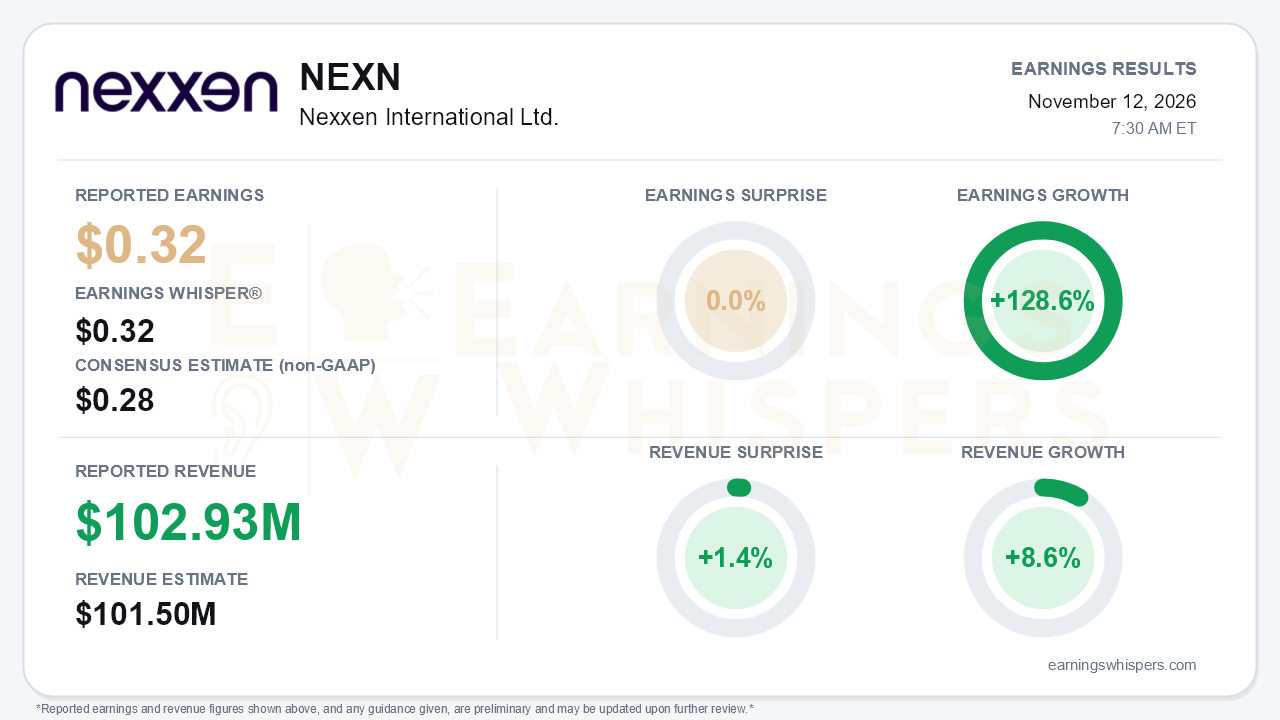
Nexxen International (NASDAQ: NEXN) reported third-quarter non-IFRS earnings of $0.32 per share, exactly matching the Earnings Whisper number and ahead of the $0.28 consensus estimate. Revenue of $102.93 million topped expectations by 1.4% and rose 8.6% from a year ago, while earnings grew 128.6% on Earnings Whispers' normalized basis. The company's own non-IFRS comparison shows $0.32 versus $0.20 a year earlier. The quarter marks a clear profitability inflection: Adjusted EBITDA returned to growth after a weak first half. That comes alongside a top line that has slowed for a third straight quarter and full-year guidance that was only reaffirmed after three raises. That is the central tension.
The earnings quality is better than a typical cost-driven beat. Adjusted EBITDA rose 22% to $34.5 million, and margin on a Contribution ex-TAC basis reached 34%, up from 30% a year ago. The sequential trend is sharper still, climbing from 19% in Q1 to 28% in Q2. IFRS results improved as well. Diluted EPS was $0.18 versus $0.07, and operating profit rose 75% to $12.7 million as R&D and G&A spending fell year over year. Still, the nine-month picture shows how much ground the second half has to recover. Year-to-date IFRS diluted EPS is down 36%, and Adjusted EBITDA is down 4%. Cash rose to $152.9 million with no long-term debt, helped by $46.1 million in quarterly operating cash flow.
Beneath the headline, the business is changing shape quickly. CTV revenue grew 39% to a record $34.1 million, accelerating from 12% in Q1 and 33% in Q2. CTV now makes up 35% of programmatic revenue, up from 27% a year ago. Contribution ex-TAC from enterprise customers grew more than 40%, versus more than 25% in Q2, and data products climbed 73%. The headline growth rates, however, keep stepping down:
- Contribution ex-TAC growth slowed from 13% in Q1 to 11% in Q2 to 8% in Q3.
- Programmatic revenue growth decelerated from 14% to 12% to 9%.
- Mobile growth cooled to 9% from 23% in Q2.
- Desktop's decline deepened to 29%.
- Linear TV, health and travel were soft.
The growth engines are real, but they are not yet large enough to offset erosion in legacy channels.
Management leaned hard into the fourth quarter. It said October was likely its best top-line month ever, and it expects all-time records in Contribution ex-TAC, programmatic revenue and CTV. On the call, it guided Q4 Adjusted EBITDA margin above 40% and reiterated a roughly 34% margin target for 2027. The catalyst list is substantive:
- Disney and Sling TV supply onboarded but not yet in reported numbers.
- Standardized Smart TV home screen inventory across V, TCL and TiVo, with Q4 expected to be the first quarter of notable home screen revenue.
- DIRECTV pause-ad access.
- Eight agency and holding-company partners testing its agentic AI tools.
Bears have legitimate ammunition, though. The implied Q4 range is wide, roughly 8% to 22% year over year, and management attributed that to macro and geopolitical volatility. Midterm political spending aided Q3 and early Q4, although management does not expect it to be a meaningful headwind in 2027. The economics of agentic AI remain undefined, which leaves open questions about pricing and take rates.
Capital allocation also shifted. Nexxen made no buybacks in Q2 or Q3, prioritizing flexibility for bolt-on acquisitions, with mobile in-app the top priority. It extended its $40 million authorization and expects to resume repurchases in the second half of Q4. It also completed a $15 million follow-on investment in V, bringing its stake to $60 million. After four years without an acquisition, the M&A pivot adds execution risk to an otherwise straightforward cash-return story.
The market setup is more complicated than the in-line print implies. Shares spiked to a 52-week high of $11.30 the day after the August report. They then gave back most of that move, sliding to an inter-earnings low of $8.16 on November 6, and entered this report at $9.05. That is 10.8% below the post-August opening price and nearly 20% off the high, though still about 8.6% above the 200-day moving average. Investor sentiment slipped from slightly positive to slightly negative, a modest shift that suggests caution rather than capitulation. The Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while AVWAP remains negative, consistent with a stock that has struggled since its summer peak.
The bottom line is that Nexxen delivered the margin recovery investors were waiting for and a CTV business that is clearly accelerating, but the reaffirmed guide and a third straight quarter of slower headline growth keep the debate alive. Q4 now carries the burden of proof. A result toward the top of the implied range, with margins above 40%, would validate the mix-shift thesis. A result near the bottom would suggest the profitability gains are outrunning revenue momentum.
Read our earnings preview for Nexxen International Ltd.: https://www.earningswhispers.com/article/NEXN/22888
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 9 hours | |
| 13 hours | |
| Nov-10 | |
| Nov-04 | |
| Oct-29 | |
| Oct-23 | |
| Oct-12 | |
| Sep-22 | |
| Sep-15 | |
| Sep-09 | |
| Aug-20 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 | |
| Aug-10 |
