Teekay Tankers Crushes Estimates As Q4 Spot Rates Top $200,000 A Day, But Sequential Dip And Rising Order Book Temper The Record Setup
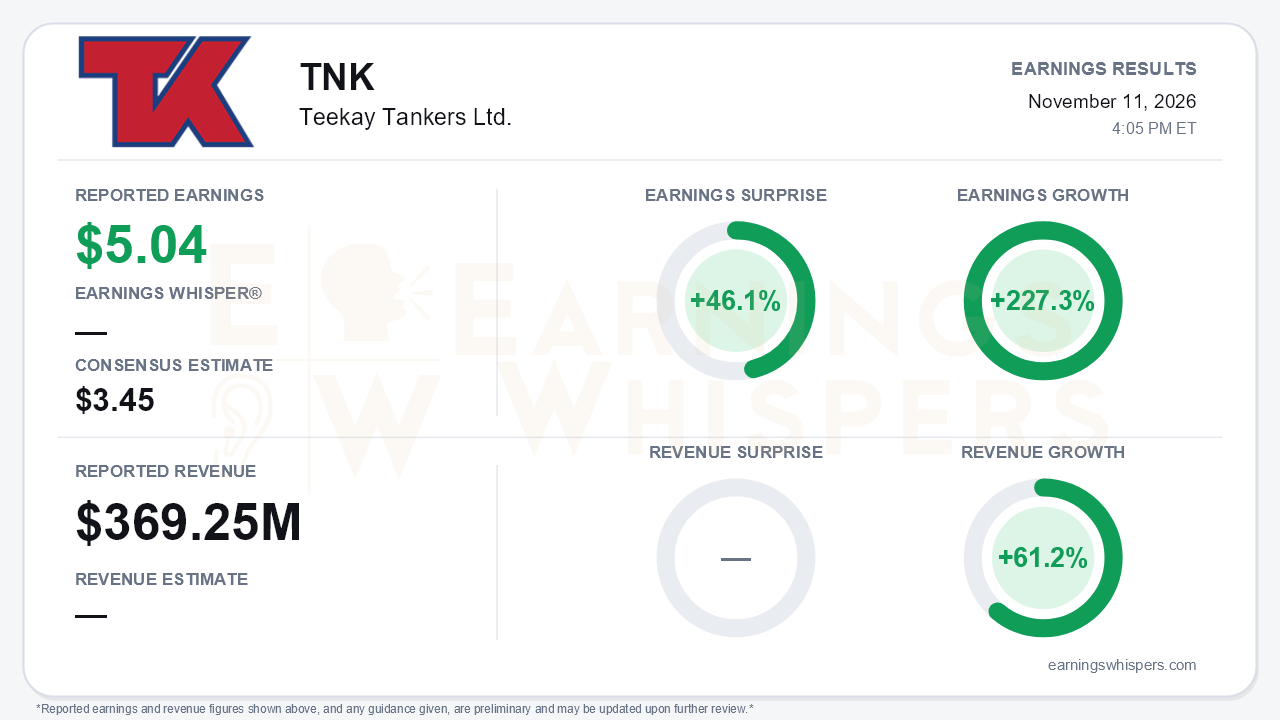
Teekay Tankers delivered a decisive beat for the September quarter, reporting earnings of $5.04 per share against a consensus estimate of $3.45, a 46.1% surprise. Earnings grew 227.3% year over year on revenue of $369.25 million, up 61.2%. The headline beat is less important than what management said about the current quarter. Mid-size spot rates in the fourth quarter to date are averaging well over $200,000 per day, a new record, and the company says it is on track for record fourth-quarter and full-year 2026 earnings. That is the central development. Q3 was a modest step back from a record Q2, but Q4 is shaping up as a step-change higher.
The quality of the quarter deserves some nuance. The $5.04 figure is an adjusted number. Adjusted net income was $176 million, down from Q2's record $194 million, or $5.56 per share. GAAP net income fell to $195 million from $226 million. The average mid-size time-charter equivalent eased to about $87,000 per day from roughly $91,000.
Segment rates moved in the same direction:
- Aframax/LR2 spot earnings slipped to $67,600 per day from $74,100.
- Suezmax spot earnings dipped to $106,400 from $109,200.
Earnings growth therefore decelerated sequentially even as the year-over-year comparison exploded. The adjusted EPS run rate went from $2.80 in Q4 2025 to $3.69, then $5.56, and now $5.04. Still, the Q3 outcome came in ahead of what the company had booked when it reported Q2. At that time, Q3 Suezmax bookings stood at $104,800 per day and Aframax at $59,900, so realized rates improved through the quarter rather than fading.
The cumulative numbers underline how strong 2026 has been. Nine-month adjusted net income of roughly $500 million already matches the full-year 2023 record. Year-to-date free cash flow is nearly $15 per share. Cash has climbed from $853 million at the end of 2025 to over $1.2 billion as of Q2, and the company remains debt-free. The board declared the fixed $0.25 quarterly dividend, payable December 4. More notably, management pulled forward its special dividend consideration to February 2027, alongside full-year results, rather than May. Given the cash pile and the Q4 rate environment, that timing shift is a meaningful signal for income-focused holders.
The more substantive change on the call was strategic posture. On the Q1 call, management conceded it was buying more slowly than hoped. It now describes running the "whole playbook" of buying, selling and possibly chartering, and says the fleet is at the low end of its desired size.
The order book expanded from two vessels to six, adding:
- two Chinese-built LR2s;
- two Korean-built Suezmaxes, with options for two more.
All four new orders deliver in 2030. The company also bought a 2020-built MR for about $49 million, re-entering product tankers after roughly a decade, and expects to sell more older tonnage over the next year. On demand, management pointed to several supports:
- crude trade volumes are back above pre-war levels;
- Chinese imports are near 10 million barrels per day;
- Red Sea rerouting via Suez/SUMED adds about 30 days of voyage length;
- inventory restocking is a medium-term tailwind.
Bears have legitimate ammunition, however. Freight rates have already moderated from September and October peaks as refining margins retreat from records. Much of the current strength rests on geopolitical inefficiency, and a US-Iran resolution would unwind ton-mile support. The order book now stands at about 25% of the mid-size fleet, with deliveries accelerating over the next three years. That supply wave arrives just as TNK commits capital to newbuilds and to an MR segment outside its core franchise, which introduces execution and scale risk.
Investors appear to be weighing those risks. Earnings Whispers sentiment, already slightly negative heading into the report, weakened further from -0.08 to -0.18. That is a notable but not dramatic souring, despite a record-rate narrative. The price action has been more constructive. Shares have gained 16.9% since the open following the July report, to $88.96, and sit about 10.9% above the 200-day moving average of $80.23. The trend readings are less enthusiastic: price trend is neutral and AVWAP is negative. That suggests momentum has cooled even as the stock holds well above its longer-term average.
The bottom line is that Teekay Tankers' Q3 beat was solid but backward-looking. The quarter itself marked a sequential slowdown from the Q2 record. Q4-to-date rates above $200,000 per day, a $1.2 billion-plus debt-free balance sheet and an accelerated special dividend decision make the near-term earnings case compelling. The harder question is durability. Rates are already off their peaks, a large order book is building, and the market is visibly hedging against a geopolitical normalization that would erode the ton-mile tailwind.
Read our earnings preview for Teekay Tankers Ltd.: https://www.earningswhispers.com/article/TNK/22837
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-11 | |
| Nov-11 | |
| Nov-11 | |
| Nov-11 | |
| Nov-11 | |
| Nov-03 | |
| Oct-27 | |
| Sep-03 | |
| Aug-28 | |
| Aug-14 | |
| Aug-10 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 |
