Teekay's Q3 Steps Back From The Q2 Record, But Record Q4 Tanker Rates Shift The Focus To Fleet Renewal And Capital Returns
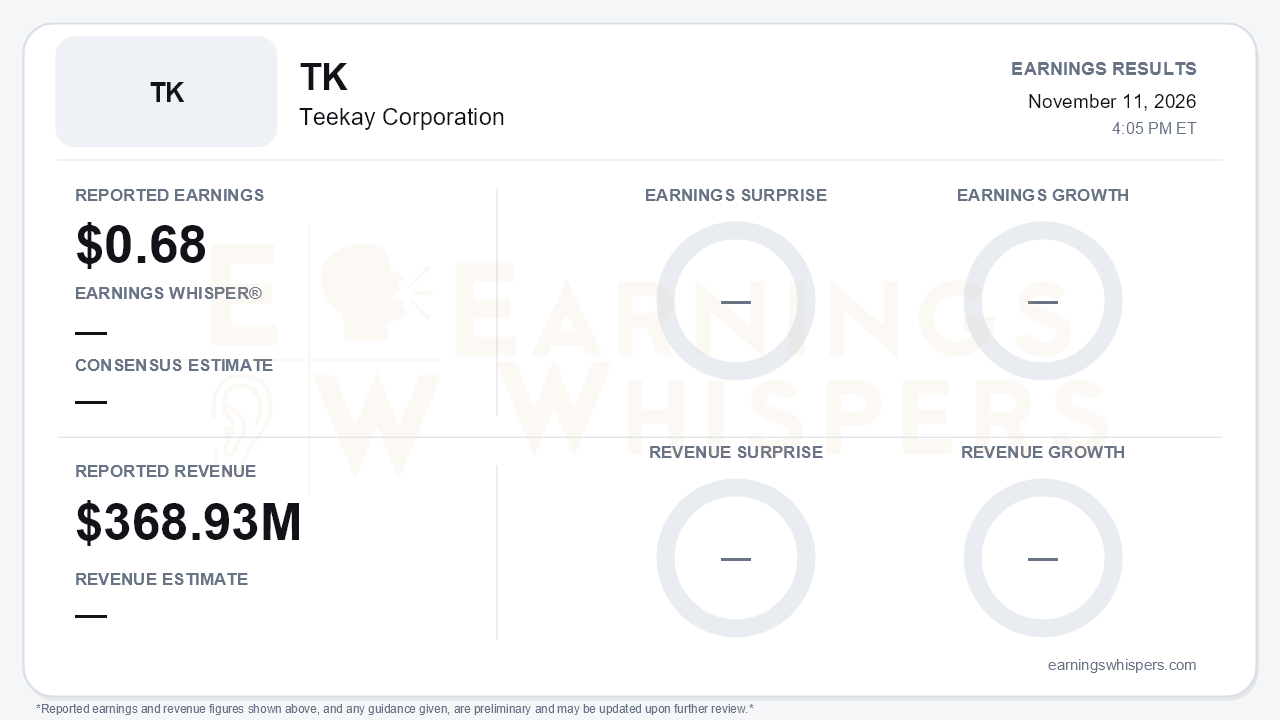
Teekay Corporation reported earnings of $0.68 per share on revenue of $368.93 million for the September 2026 quarter. No consensus estimate or year-over-year comparison was available, so the headline cannot be scored as a beat or a miss. The more useful read is sequential. Q3 was a step down from a record Q2. But management used the call to argue that the fourth quarter is shaping up as the strongest in the company's history, and that tension is the core of the report.
The press release was a pointer to the group's online update and offered no financial detail. The call carried the substance. One reconciliation issue needs flagging first. The per-share figures discussed on the call do not match Teekay Corporation's $0.68 per share:
- adjusted net income of $176 million, or $5.04 per share;
- GAAP net income of $195 million, or $5.60 per share.
Those figures appear to reflect results at the Teekay Tankers operating level. Teekay Corporation consolidates Teekay Tankers through a controlling stake, so its own per-share earnings reflect a different share base and ownership structure. Investors should treat the call's per-share numbers as an operating-company trend, not as TK's reported EPS.
On that operating basis, Q3 cooled from Q2:
- Adjusted net income slipped from a record $194 million ($5.56 per share).
- GAAP net income fell from $226 million ($6.49 per share).
- Realized Suezmax spot rates eased to $106.4k/day from $109.2k.
- Aframax/LR2 rates fell to $67.6k from $74.1k.
- The mid-size average dipped to roughly $87k from $91k.
These are modest declines from extraordinary levels, not a sign of a weakening market. Through nine months, adjusted net income was nearly $500 million, already matching record full-year 2023. Free cash flow ran at roughly $15 per share.
What changed is the forward picture. Quarter-to-date Q4 mid-size bookings are a weighted ~$236k/day, which management put at more than 30 times its free-cash-flow breakeven. A quarter ago, management cited Q3 bookings of $104.8k for Suezmaxes and $59.9k for Aframaxes. On that basis, management is guiding to a record Q4 and a record full year. The tone turned more emphatic, with references to "exceptional strength" and the "strongest front end of the curve ever."
The demand case has also broadened beyond a single disruption:
- Red Sea attacks are rerouting Yanbu flows via Suez/Sumed, adding about 30 days to voyages.
- Atlantic-to-Pacific ton-miles are growing.
- Global crude trade is back above pre-war levels.
- Chinese imports have recovered to near 10 mb/d, with depleted inventories still to rebuild.
Management is converting that cash into fleet renewal at an accelerating pace:
- **Disposals:** four vessels sold year-to-date for $211 million, generating $78 million in gains.
- **Commitments:** ten vessels acquired or committed for about $716 million, up from five vessels for $332 million at the Q1 update.
- **Newbuilds:** two Chinese-built LR2s and two Korean-built Suezmaxes for 2030 delivery, plus two options, taking the newbuild orderbook to six.
- **Product tankers:** a 2020-built MR bought for about $49 million, re-entering the segment after roughly a decade.
For shareholders, the most tangible catalyst may be timing. The special dividend decision moves up to February 2027, alongside full-year results, instead of May.
Bears have legitimate ammunition, and management acknowledged much of it:
- Rates have moderated from the September/October peaks as refining margins retreat from records.
- Management conceded conditions may not stay at extreme levels.
- WTI has dropped about $20 in recent weeks, with no visible stock-building yet.
- The mid-size orderbook stands near 25% of the fleet, with deliveries accelerating over the next three years.
- A US-Iran resolution could unwind the trade inefficiencies now inflating ton-miles.
Management also plans to sell more ships over the next 12 months. That raises capital but trims the earnings base just as the cycle may be peaking. The 2030 newbuild timing implies management is positioning for a longer horizon than the current rate spike.
Market context is thin. Current price, sentiment readings and inter-earnings range data were not available. Shares opened at $10.96 after the July report, and the 200-day moving average now sits at $12.52, but without a current quote there is no basis for judging how the stock has traded since. Investors should anchor on the operating evidence rather than on price action.
The bottom line is that Teekay's Q3 was a minor sequential retreat from a record quarter, while the call made a credible case that Q4 will set new highs on rates far above breakeven. The questions now are durability and capital allocation. Investors will be watching how much of this windfall reaches shareholders in February versus how much goes into a fleet-renewal program built for a market that could look very different once the orderbook delivers and today's trade dislocations ease.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-11 | |
| Nov-11 | |
| Oct-27 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-15 | |
| Jul-14 | |
| May-14 | |
| May-13 | |
| May-13 | |
| May-11 | |
| Apr-29 | |
| Apr-08 |
