Cardinal Infrastructure's Margin Collapse Turns A Growth Story Into An Execution Test As Guidance Is Withdrawn
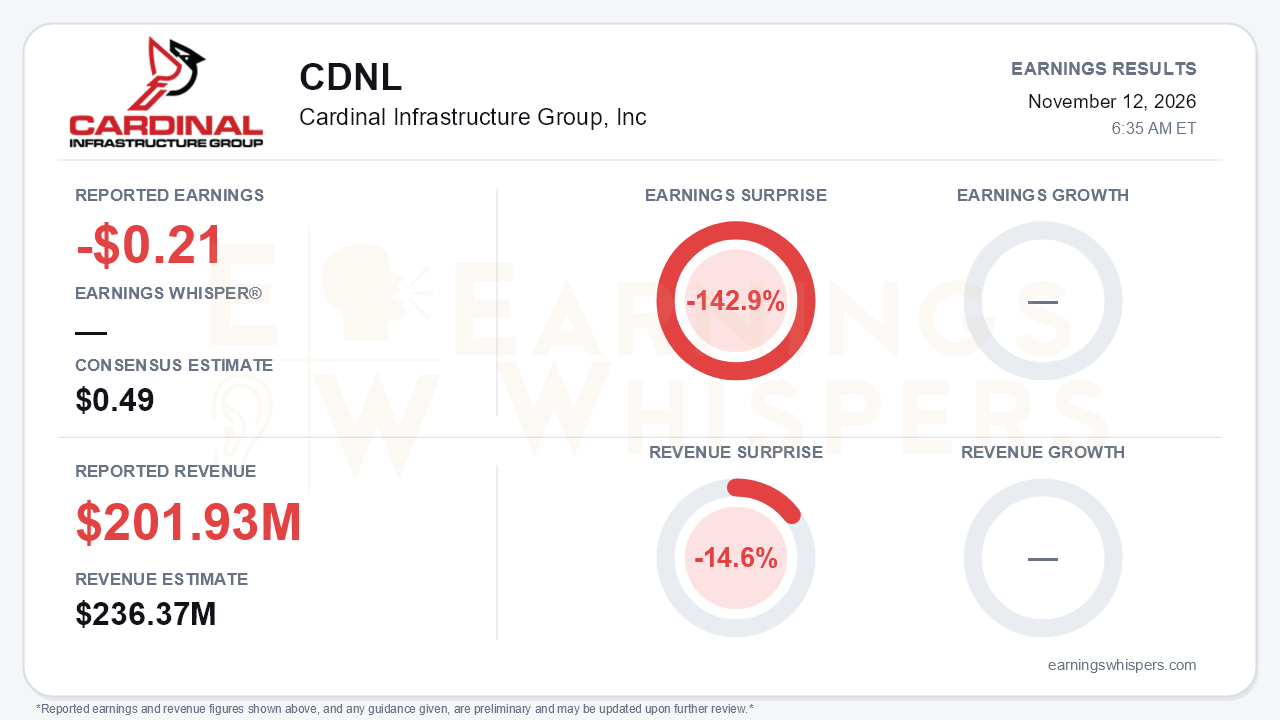
Cardinal Infrastructure Group (NASDAQ: CDNL) delivered the kind of quarter that resets an investment thesis. The company reported a loss of $0.21 per share against a consensus estimate for a $0.49 profit, a 142.9% miss. Revenue of $201.93 million fell 14.6% short of the $236.37 million consensus. Management then withdrew full-year 2026 guidance, postponed the Hughes Brothers acquisition and disclosed that CFO Mike Rowe will step down. Revenue still rose 65.1% year over year, but that growth figure is now beside the point. The central tension is that Cardinal has been scaling faster than its ability to estimate and execute profitably, and this quarter exposed the gap.
The quality of the quarter deserves scrutiny well beyond the headline loss. Gross margin fell to 5.4% from 15.9% a year earlier. Adjusted EBITDA dropped to $8.5 million, a 4.2% margin versus 17.5% in the prior-year quarter. Net results swung from $10.1 million of net income to an $11.0 million net loss. Management broke the 13.3-point adjusted EBITDA margin decline into three pieces:
- $13.2 million of project estimate revisions, about 6.5 points;
- residential pricing pressure and thin initial bid margins on commercial and industrial work, about 3.6 points;
- higher fuel and transportation costs, about 3.5 points.
That breakdown matters because only the first item looks one-time in nature. Pricing pressure and cost inflation sound structural. G&A also nearly tripled to $14.7 million, so overhead is growing faster than gross profit. Organic growth contributed only $23.9 million of the $79.6 million revenue increase; acquisitions supplied the rest.
The sequential trend is worse than the year-over-year comparison. Revenue fell from about $227 million in the second quarter. Adjusted EBITDA margin slid from 16% in the first quarter to roughly 12% in the second and now 4.2%. Guidance has gone through three stages in three quarters:
- Q1: raised to $675-685 million in revenue with a 20%-plus margin;
- Q2: raised again to $880-900 million, but with the margin cut to 16-18%;
- Q3: withdrawn entirely.
The medium-term low-20s margin ambition was not reiterated. On the call, residential softness that management called manageable a quarter ago is now described as Southeast-wide and likely to persist through 2027, with intensified pricing competition in the Carolinas. Three Carolinas residential projects accounted for half of the estimate revisions. Management also tied forecasting problems in part to an ERP transition, which raises legitimate questions about project visibility. The tone shifted just as sharply, from "never felt better" last quarter to "results are not acceptable" and "credibility will be built through execution."
There is a credible, if narrower, recovery case. Total backlog of $815.5 million is up 26.2% from a year ago. However, that increase is mostly acquired, backlog fell from $866 million in the second quarter, and book-to-bill was below 1. Management said the troubled projects are more than 75% complete and expects fourth-quarter adjusted EBITDA to improve sequentially, though it gave no revenue or margin figures. Other potential catalysts include:
- a change order that lifts the data center Phase 1 contract by roughly 50%, with a Phase 2 award expected late in the first quarter or early in the second quarter of 2027;
- the Aviator asphalt plant running fully for its first full quarter;
- COO Benji Wood taking direct control of estimating and project-review standards, backed by an outside advisor.
The balance sheet provides real cushion. Cardinal holds $335.0 million of cash and $136.5 million of net cash, which supports the new $50 million buyback. Still, free cash flow was negative $11.3 million year to date, and a CFO search during a controls overhaul adds execution risk.
The market had largely anticipated trouble before the release. Shares closed at $14.99 heading into the report, down 70.7% from the $51.08 open after the August report. That leaves the stock 72% below its inter-earnings high of $53.51, set on that same post-report day. Shares sat about 65% below the 200-day moving average and only about 20% above a 52-week low of $12.51 set November 5. Investor sentiment fell from a neutral 0.03 to -1.05, the extreme negative end of the range. Expectations were therefore deeply pessimistic before management confirmed the damage. The AVWAP trend remains negative, consistent with sustained selling pressure.
The bottom line is that Cardinal's third quarter converted a high-growth roll-up narrative into a show-me execution story. Bears have ample ammunition: collapsing margins, withdrawn guidance, falling backlog, a departing CFO and residential weakness expected to last into 2027. The stock's collapse and washed-out sentiment show that much of this was already feared, and the net cash position buys time. The next test is whether fourth-quarter margins actually recover and whether bookings stabilize, not whether revenue keeps growing.
Read our earnings preview for Cardinal Infrastructure Group, Inc: https://www.earningswhispers.com/article/CDNL/22867
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 5 hours | |
| 7 hours | |
| 7 hours | |
| 8 hours | |
| 8 hours | |
| Nov-05 | |
| Nov-04 | |
| Oct-27 | |
| Oct-20 | |
| Oct-19 | |
| Oct-13 | |
| Oct-07 | |
| Oct-01 | |
| Sep-24 |
