Tecogen Beats On A Q3 Rebound, But The Data Center Story Shifts To A New Product Instead Of Orders
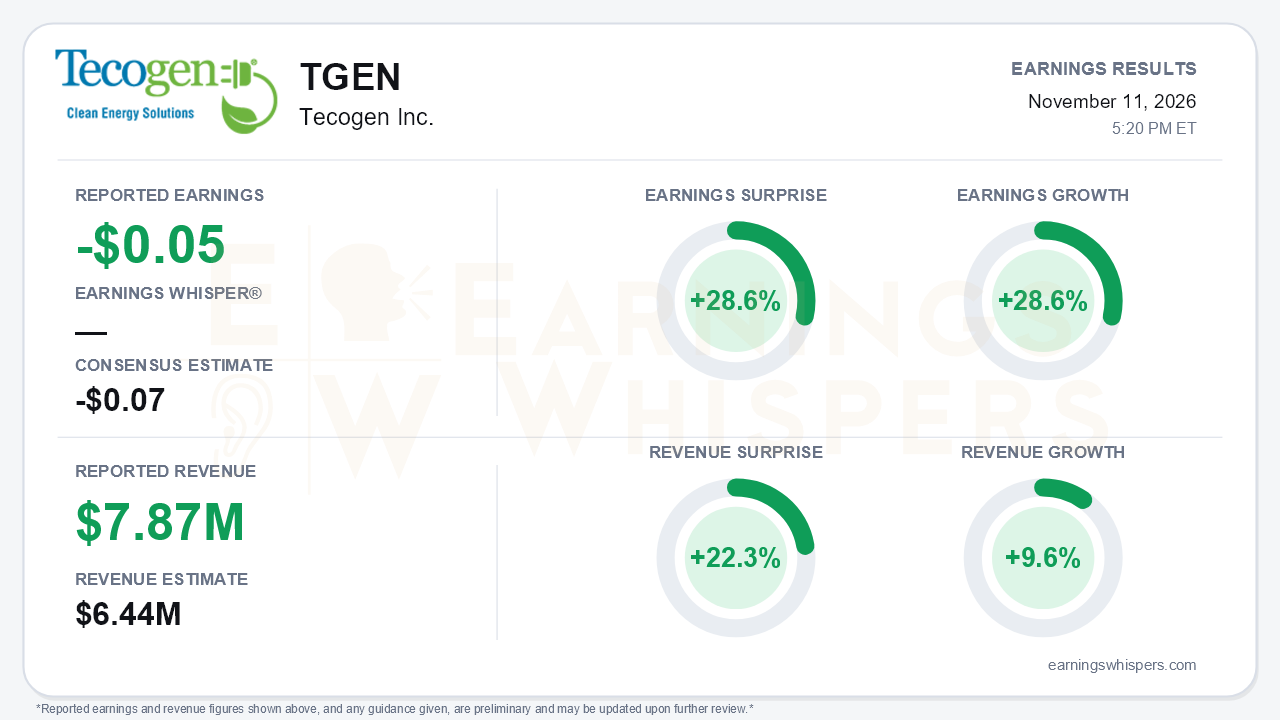
Tecogen delivered the third-quarter rebound it had promised, but the call did not convert its data center pipeline into orders. The company reported a loss of $0.05 per share against a consensus estimate of -$0.07, a 28.6% earnings surprise. Revenue of $7.87 million beat the $6.44 million consensus by 22.3%. Earnings improved 28.6% from a year ago and revenue grew 9.6%. Sequentially the recovery was sharper: revenue rose from $5.8 million in Q2 and $6.4 million in Q1. That is the central tension. The base business is healing, yet the catalyst investors have been underwriting for several quarters slipped further, and the hope was reframed around a newly unveiled modular product rather than signed contracts.
The quality of the beat leans heavily on services. Services revenue rose 13.2% to $4.46 million, helped by the acquired Aegis maintenance contracts. More important, services gross margin jumped to 42.6% from 25.3%, which validates the cost actions flagged on the first- and second-quarter calls. That drove consolidated gross margin to 37.4% from 30.4%. Energy production revenue also rose 42%. Products, the segment that carries the growth thesis, was far less convincing:
- **Products revenue:** up just 2.2% to $3.05 million, and down 38.2% for the nine months.
- **Products gross margin:** fell to 27.1% from 36.8% a year ago and 48.5% in Q2. Management cited hybrid-drive chiller material costs and a factory realignment.
- **Operating expenses:** rose 5.3%. Stock-based compensation roughly doubled and credit-loss provisions increased.
The net loss narrowed to $1.59 million from $2.13 million, and adjusted EBITDA improved to -$1.01 million from -$1.67 million. The release puts adjusted EBITDA at -$1.01 million; figures discussed on the call were closer to -$1.1 million. Either way, the company remains firmly loss-making.
The balance sheet deserves attention. Cash fell to $5.33 million at September 30 from $12.43 million at year-end, after $6.85 million of operating cash burn over nine months. Third-quarter cash was roughly flat sequentially. The CEO said cash had risen to $5.7 million, with about $800,000 more expected within two weeks. That is a welcome stabilization, not yet a trend. The company itself lists the ability to obtain financing on favorable terms as a risk factor, and the share count has already climbed about 5% year over year.
On the call, management spotlighted a modular dual power source package that retrofits onto third-party chillers, dry coolers and other data center loads, and said it is covered by existing patents. Management claims the module offers more than twice the roughly 100-chillers-per-year capacity of its current production, along with higher margins and lower working capital needs. It is also pitched as a fit for data centers facing construction moratoriums, since it can add power on already-approved sites. Management also highlighted:
- **Backlog mix:** more than 70% of the backlog now sits with large property portfolio owners and energy services companies.
- **New leads:** utility-rate spikes and power shortages are generating $2-5 million industrial and healthcare leads.
- **Early adoption:** one non-data-center prospect has already specified the module into a project.
Bears have legitimate ammunition, however:
- **Vertiv:** the master purchase agreement remains unannounced after several quarters of anticipation, with management offering only "stay tuned."
- **Hyperscale and neocloud demand:** twelve summer demos produced no orders, and customers now want proof that production can scale.
- **Module timing:** there is no shipment date, and launch customers are still being sought.
- **Backlog:** it held at more than $8 million, unchanged from Q2, without visible evidence of the additional closes management had expected.
The market had largely priced in that disappointment before the print. Shares closed at $1.70, down 54.8% from the $3.76 open after the August report and about 54% below the 200-day moving average of $3.70. Investor sentiment swung from modestly positive (0.13) to modestly negative (-0.10), a meaningful shift in expectations rather than a collapse. Earnings Whispers price and AVWAP trend readings remain negative, consistent with how heavily the stock has been sold.
The bottom line is that Tecogen produced a genuinely better quarter: sales sharply higher, services profitability transformed and losses narrower. But it did not deliver what the stock needed, which was data center orders. A sizable beat against low expectations, combined with a depressed share price, gives the story room to stabilize. Until the Vertiv agreement, a hyperscale order or first module shipments materialize, and products margins recover, the investment case still rests more on management's pipeline narrative than on contracted revenue, with a thinning cash cushion adding urgency.
Read our earnings preview for Tecogen Inc.: https://www.earningswhispers.com/article/TGEN/22965
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-11 | |
| Nov-05 | |
| Nov-04 | |
| Oct-14 | |
| Aug-17 | |
| Aug-12 | |
| Jul-31 | |
| Jul-06 | |
| May-13 | |
| May-12 | |
| Apr-24 | |
| Mar-18 | |
| Mar-17 | |
| Mar-02 |
