Crown Crafts Grows EPS 9.1% Despite A 19.7% Sales Drop, As Margins And Debt Paydown Hide A Weak Top Line
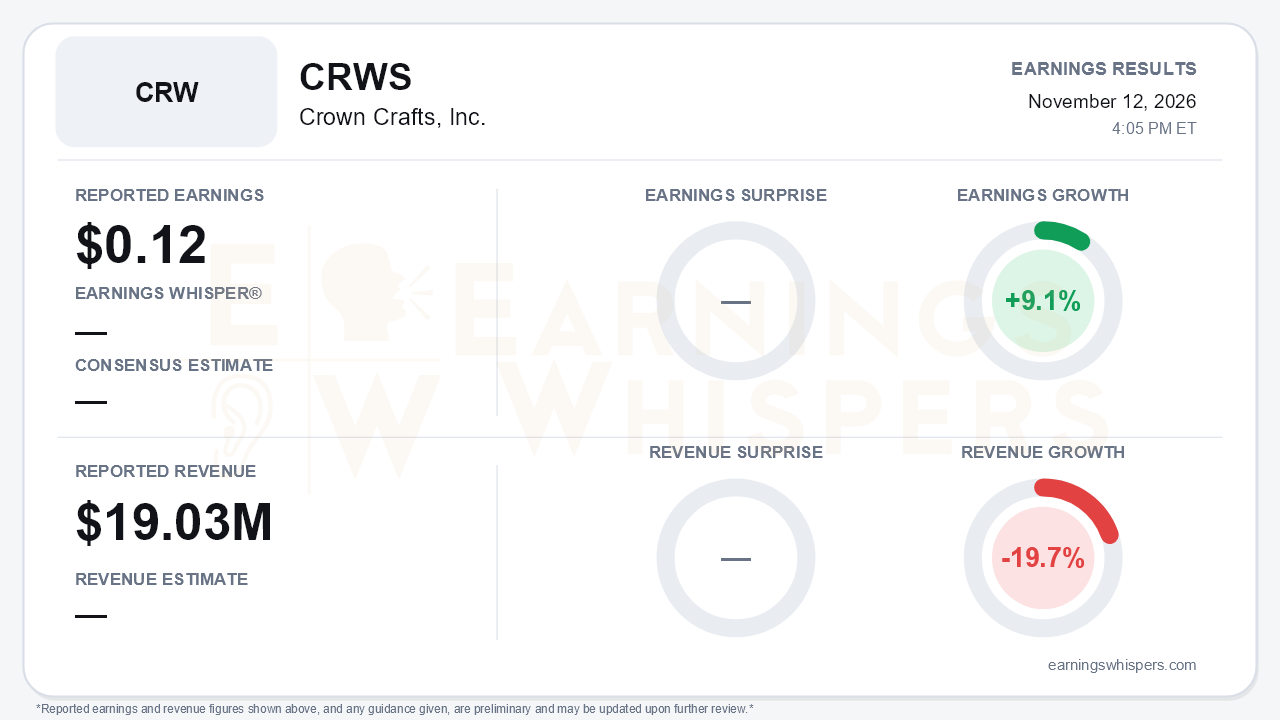
Crown Crafts reported fiscal second-quarter earnings of $0.12 per share, up 9.1% from $0.11 a year ago, on revenue of $19.03 million, down 19.7%. No consensus estimate or Earnings Whisper was available, so the quarter cannot be judged as a beat or miss. It has to be judged on its own internals, and those show a clear split. Profitability per dollar of sales improved meaningfully, but the top line deteriorated sharply. That reverses the 8% sales growth the company posted in the first quarter. Management's statement that the company "generated strong sales" is hard to square with a nearly $4.7 million year-over-year revenue decline. That is the central tension.
The quality of the earnings growth deserves scrutiny. Reported gross margin rose to 32.0% from 27.7%. That figure includes $0.4 million of tariff refunds tied to the Supreme Court ruling on IEEPA tariffs, partly offset by $0.2 million of severance. On the company's adjusted basis, gross margin was 30.9%, still a solid 320-basis-point improvement. Because sales fell so steeply, however, adjusted gross profit dropped to $5.87 million from $6.57 million. Marketing and administrative expense fell modestly to $4.5 million from $4.7 million, but operating income still slipped to $1.56 million from $1.86 million. The EPS gain came below the operating line. Net interest swung from $287,000 of expense to $72,000 of net interest income, and other income rose to $150,000 from $4,000. Without that, the quarter would have shown lower operating earnings on a shrinking revenue base.
The balance sheet is the most tangible improvement. Total debt fell to about $5.3 million from roughly $14.1 million at fiscal year-end in March. That paydown was aided by the much larger tariff refunds booked in the first quarter, $4.2 million year-to-date in cost of products sold. It also benefited from a $3.5 million drop in amounts due from the factor and a $2.5 million rise in accounts payable. Some of the cash improvement is therefore working-capital timing rather than recurring earnings power. Year-to-date, net income of $3.4 million compares with essentially breakeven a year ago. Yet six-month adjusted gross profit was flat at $10.1 million, a reminder of how much the refunds have shaped the first-half picture.
The conference-call record adds less than usual. The transcript tied to this report appears to repeat the first-quarter call nearly verbatim. It references $16.8 million in sales and the June balance sheet, so it offers no genuinely new commentary on the September quarter. Read in that light, the call material reflects management's earlier narrative:
- Groovy Girls was selling ahead of expectations, especially in Canada through Indigo, with U.S. inventory diverted north.
- A European launch and a partial Amazon rollout were planned.
- New Canadian and European distributors were supporting international growth.
- The Minneapolis office lease will not be renewed.
- Roughly $0.9 million of tariff refunds remained unbooked.
The release's mention of Groovy Girls strength in Canada suggests that story continued. But nothing in the materials explains why consolidated sales fell nearly 20%.
The risk list from that commentary remains relevant:
- Consumer demand was described as soft.
- Sourcing is concentrated in China in the high-90% range, keeping tariff exposure live.
- A diaper bag relaunch got off to a slow start.
- Target private-label losses in bibs and diaper bags still weigh on volume.
- Warehouse consolidation, targeted for May 2028, will require upfront investment.
The dividend also matters. The board declared $0.03 per share, which the call characterized as a right-sized cut to fund growth investment and debt reduction. That is a defensible capital-allocation choice, but it signals management prioritizing balance-sheet repair over income. No formal guidance has been offered.
Market context is thin. No current price or investor sentiment reading was available. Shares opened at $2.95 after the August report, modestly above the 200-day moving average of $2.77. That leaves the stock's post-report trajectory unclear going into a quarter that pairs better margins with worse sales.
The bottom line is that Crown Crafts delivered higher EPS through margin discipline, lower interest costs, and other income rather than through a healthier business. Adjusted gross margin of 30.9% and a sharply reduced debt load are real gains, and the tariff-refund windfall has materially de-risked the balance sheet. But a 19.7% revenue decline, lower operating income, a reduced dividend, and a call record that offers no fresh Q2 detail leave investors with an unanswered question: whether Groovy Girls and international distribution can offset softness in the core baby and private-label business. Until sales stabilize, the margin story alone is unlikely to carry the investment case.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-05 | |
| Oct-22 | |
| Aug-12 | |
| Aug-12 | |
| Aug-05 | |
| Jun-24 | |
| Jun-24 | |
| Jun-24 | |
| Jun-24 | |
| Jun-17 | |
| May-14 | |
| Mar-11 |
