Rekor Matches On EPS, But A 23% Revenue Drop, Abandoned EBITDA Target And $15 Million Note Maturity Put Liquidity Front And Center
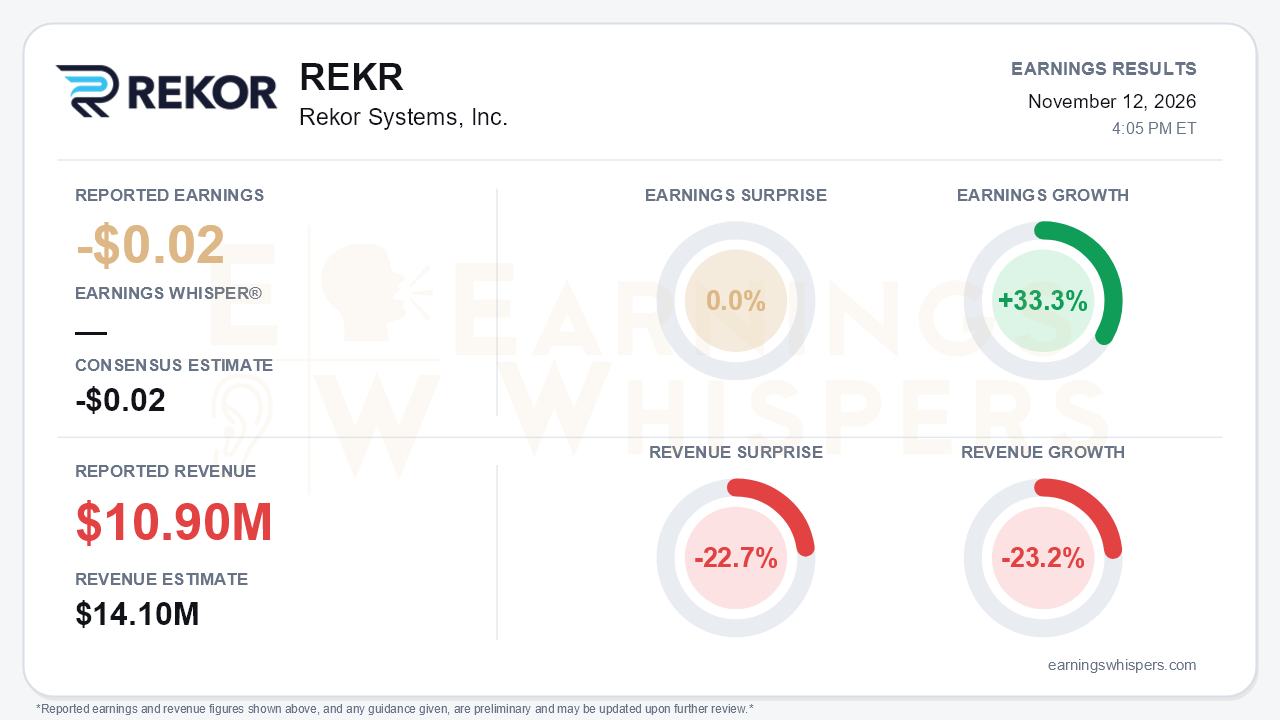
Rekor Systems matched expectations on the bottom line and missed badly on the top. The company reported a third-quarter loss of $0.02 per share, in line with consensus and a 33.3% improvement from a year ago. Revenue of $10.9 million missed the $14.1 million consensus by 22.7% and fell 23.2% year over year. The EPS figure is the least important number in the release. This quarter broke the improving narrative management had built over the prior three calls. Revenue reversed, margins compressed, the adjusted EBITDA profitability target disappeared, and a $15 million note maturity on December 15 is now the dominant issue for the equity.
The quality of the reported loss deserves scrutiny. The narrower GAAP net loss of $2.9 million included a $3.9 million net gain on lease remeasurement, partly offset by a $2.2 million write-off of leasehold improvements. Strip those out and the operating picture is worse than the headline implies. Adjusted EBITDA loss widened to $2.6 million from $1.5 million a year ago and from roughly $1.2 million in the second quarter. The revenue mix explains much of the damage:
- Recurring revenue grew 16% to $7.5 million and now accounts for 69% of sales.
- Product and service revenue collapsed to $3.4 million from $7.7 million, because last year's high-margin perpetual software license sales did not recur.
- Adjusted gross margin fell to 48.2% from 63.4% a year ago. It also declined sequentially from about 56% in Q2 and 53% in Q1.
Management additionally flagged higher urban mobility delivery costs as a margin headwind.
Cost discipline is real, and it is the strongest part of the story. Combined G&A, selling and R&D expenses fell 28% in the quarter, with annualized savings cited above $10 million. Lease exits in Columbia and Tel Aviv cut operating lease liabilities to $0.8 million from $13.3 million and should save more than $2 million a year. Nine-month operating cash use fell 49% to $10.6 million.
The problem is that cuts cannot offset a shrinking top line forever. Demand also deteriorated. Management attributed the stall in license-based license plate recognition (ALPR) sales to privacy and regulatory uncertainty. That stands in sharp contrast to late 2025, when the company described license plate recognition (LPR) licensing as picking up and played down regulatory risk.
Forward commitments also moved backward:
- The prior goal of adjusted EBITDA profitability in the second half of 2026, reiterated on the Q2 call, was replaced by an undated objective of profitability at roughly $50 million of annual revenue. The release itself explicitly cautions that this is not a forecast. Nine-month revenue is running at $33.8 million, well short of that level.
- The aggressive sales ramp slid into 2027.
- Born Authentic, formerly GoSecure, slipped from a Q3 2026 launch to a planned Q1 2027 retail introduction.
The tone on the call was heavily caveated, with management saying it was not 'declaring victory.'
The contract pipeline is the credible counterweight:
- A South Carolina statewide opportunity with potential value above $22 million, still subject to final negotiations.
- An Oregon intent to award worth about $1.4 million over five years.
- A Florida contract ceiling raised 94% to $9.5 million, which the company stresses is not committed revenue.
- A Southern Nevada award worth up to $1.54 million.
Roughly $2 million of prepaid inventory is also available for 2027 deployments, which should ease the cost of rolling out new business. However, none of these awards solves the immediate problem. Cash fell to $5.1 million from more than $10 million at the end of Q2, partly due to $2.6 million in lease termination payments. That leaves the company holding a third of the $15 million in revenue-sharing notes due next month. Management describes 'active, productive discussions' with multiple lenders but has no definitive agreement. The forward-looking statements now reference going-concern risk. Two further overhangs remain: a Nasdaq bid-price deadline of April 26, 2027, and litigation against a former director.
The market had already priced in considerable distress. Shares closed at $0.33 ahead of the report, down 54.6% from the $0.72 open following the August release and about 52% below the 200-day moving average of $0.68. The stock set a 52-week low of $0.22 on October 27 before rebounding roughly 48% off that level. It still trades far closer to the bottom of its inter-earnings range than the top. Investor sentiment was essentially unchanged at about -0.51, firmly negative, which suggests expectations were already low rather than newly broken. The Earnings Whispers AVWAP trend remains negative, consistent with sustained selling pressure since the last report.
The bottom line is that Rekor's restructuring has produced a leaner cost base and a larger recurring revenue mix, but the quarter exposed a business whose revenue and margins are moving the wrong way just as its financing window narrows. The in-line EPS is cosmetic, flattered by lease accounting gains. Until a refinancing is signed and contract awards convert into recognized revenue, liquidity rather than operating progress will define the investment setup.
Read our earnings preview for Rekor Systems, Inc.: https://www.earningswhispers.com/article/REKR/23085
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-10 | |
| Nov-09 | |
| Oct-28 | |
| Oct-27 | |
| Oct-19 | |
| Sep-30 | |
| Sep-03 | |
| Aug-31 | |
| Aug-14 | |
| Aug-13 | |
| Aug-12 | |
| Aug-11 | |
| Jul-29 |
