CytoSorbents Beats On The Bottom Line And Hits Cash-Flow Breakeven, But A Thin Balance Sheet And Stalled Revenue Still Define The Story
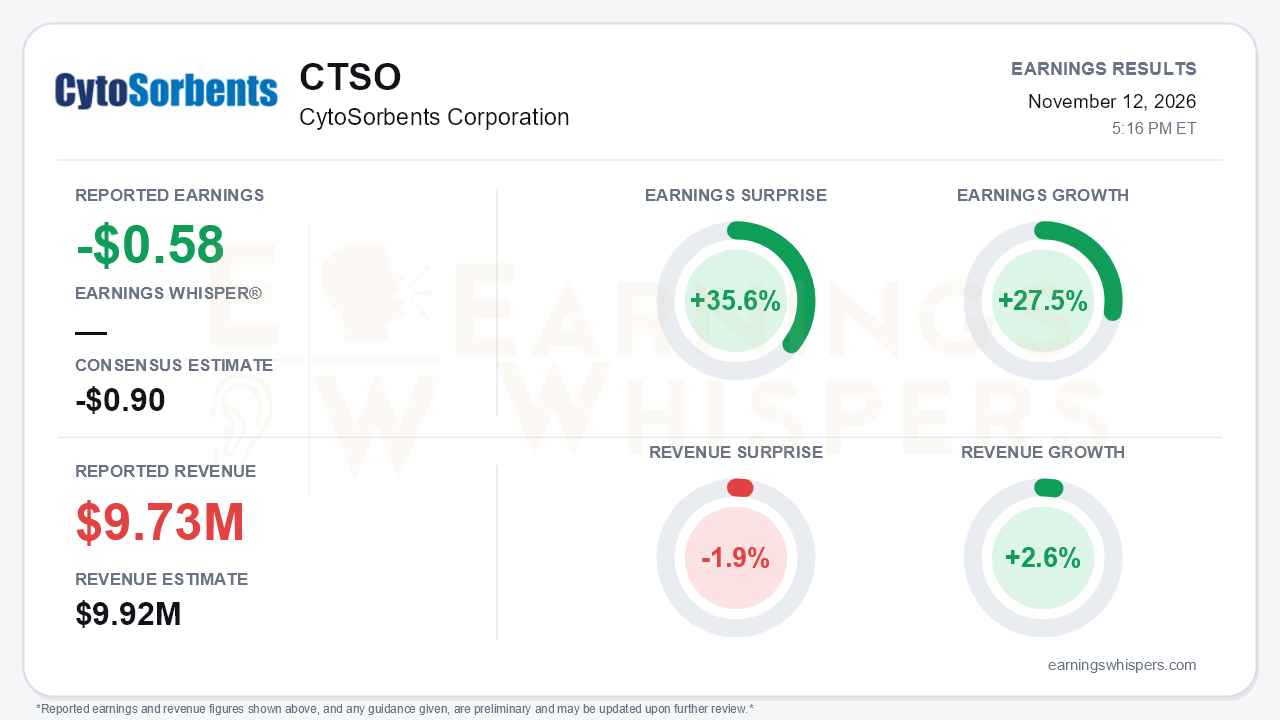
CytoSorbents reported a third-quarter loss of $0.58 per share, well ahead of the -$0.90 consensus estimate. That is a 35.6% earnings surprise and a 27.5% year-over-year improvement in per-share results. Revenue was $9.73 million, which missed the $9.92 million consensus by 1.9% and grew only 2.6% from a year ago. The quarter's real headline is not the EPS beat. It is that management delivered the operating cash-flow breakeven it has been promising since late 2025: positive operating cash flow of about $43,000, excluding $251,000 of restructuring payments. That is the central tension. The cost side of the turnaround is largely done, while the revenue side has barely started.
The quality of the improvement is real, but it should be read precisely. Gross margin reached 75%, up from 73% in Q2, 69% in Q1 and 70% a year ago. Operating expenses fell 11% to $8.5 million, helped by a 24% headcount reduction since September 2025. As a result, operating loss narrowed to $1.2 million from $2.9 million. Adjusted EBITDA loss shrank 86% to roughly $0.3 million, extending a clean sequential progression from $2.2 million in Q1 and $1.6 million in Q2. A working-capital tailwind also helped: inventory dropped to $3.2 million from $5.3 million at year-end, a source of cash that cannot repeat indefinitely. Below the operating line, net interest expense rose to $892,000 from $645,000. A $227,000 foreign-currency gain also flattered the GAAP net loss modestly. Breakeven here is an operating cash-flow milestone excluding restructuring, not GAAP profitability. Total quarterly cash burn including those payments was still about $200,000.
Beneath the flat top line, the business is diverging. Distributor and strategic-partner sales are the bright spot. The release cites both 16% and 18% year-over-year growth for this channel in different passages. The call material frames it as acceleration from flat in Q1 to roughly +16% in Q2 and +18% in Q3. Direct sales outside Germany, however, decelerated from +13% in Q1 to +9% in Q2 to just +4% in Q3. Germany, at 24% of sales, fell about 20% year over year, a steeper drop than in prior quarters. Management attributes the German decline to its own restructuring: a smaller sales force and reduced territory coverage. In other words, part of the margin gain was bought with lost revenue in the company's most important direct market. The fix is underway. Two German reps have been added, a third is expected next month, two more are planned through early 2027, and a new SVP of Direct Sales has been hired. Management also cautioned that breakeven will not be linear as it reinvests in sales.
The forward catalysts center on DrugSorb-ATR. An independent 587-patient analysis presented at ESC showed a 37% relative reduction in severe BARC-4 bleeding (21.8% vs. 34.5%, p=0.002). That analysis is meant to anchor a new ticagrelor De Novo submission now targeted for early 2027, with a separate DOAC submission planned for 2027. Investors should note the timeline has slipped repeatedly, from an original March 2026 target to the current one. The supporting animal study is also moving slower than management wanted because of institutional review and protocol amendments. Management also raised its gross-margin framing to a consistent mid-70s range and is exploring licensing, partnering or non-dilutive funding for HemoDefend-BGA.
Bears have legitimate ammunition on the balance sheet. Cash stood at $5.7 million, down from $7.8 million at the start of the year. About $17.5 million of debt is now classified as current. Stockholders' equity has turned into a $2.3 million deficit. A 1-for-20 reverse split was required in September, and both Nasdaq compliance and the debt extension or refinancing remain unresolved. Breakeven matters precisely because it reduces future financing needs, but it does not solve the maturity wall.
Investor sentiment swung sharply, moving from clearly negative (-0.57) after the prior report to solidly positive (+0.43). The price action tells a rougher story. Shares were at $5.34 heading into the report, down 29.7% from the open after the August release and nearly 42% below the 200-day moving average of $9.17. The stock hit a 52-week low of $2.84 on October 15 and has since rebounded about 88% off that level. The rebound shows buyers were positioning for a better quarter before the release. AVWAP trend readings have turned positive, while other trend signals are mostly neutral.
The bottom line is that CytoSorbents proved it can run near cash breakeven, and the EPS beat reflects genuine margin and cost discipline rather than accounting noise. Proving it can grow is the harder part. Revenue missed, Germany is shrinking, direct international growth is fading, and the balance sheet leaves little room for error. The next several quarters hinge on whether rebuilt German coverage and partner momentum can lift revenue before the debt and listing issues force the company's hand, with the DrugSorb filing as the larger but still-distant option.
Read our earnings preview for CytoSorbents Corporation: https://www.earningswhispers.com/article/CTSO/23010
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-09 | |
| Nov-06 | |
| Oct-29 | |
| Sep-30 | |
| Sep-23 | |
| Sep-10 | |
| Sep-04 | |
| Sep-03 | |
| Sep-02 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 |
