Belite Bio Beats On The Bottom Line As FDA Path For Tinlarebant Clears, But Slipping GA Timelines And Rising Launch Spend Leave Investors Souring
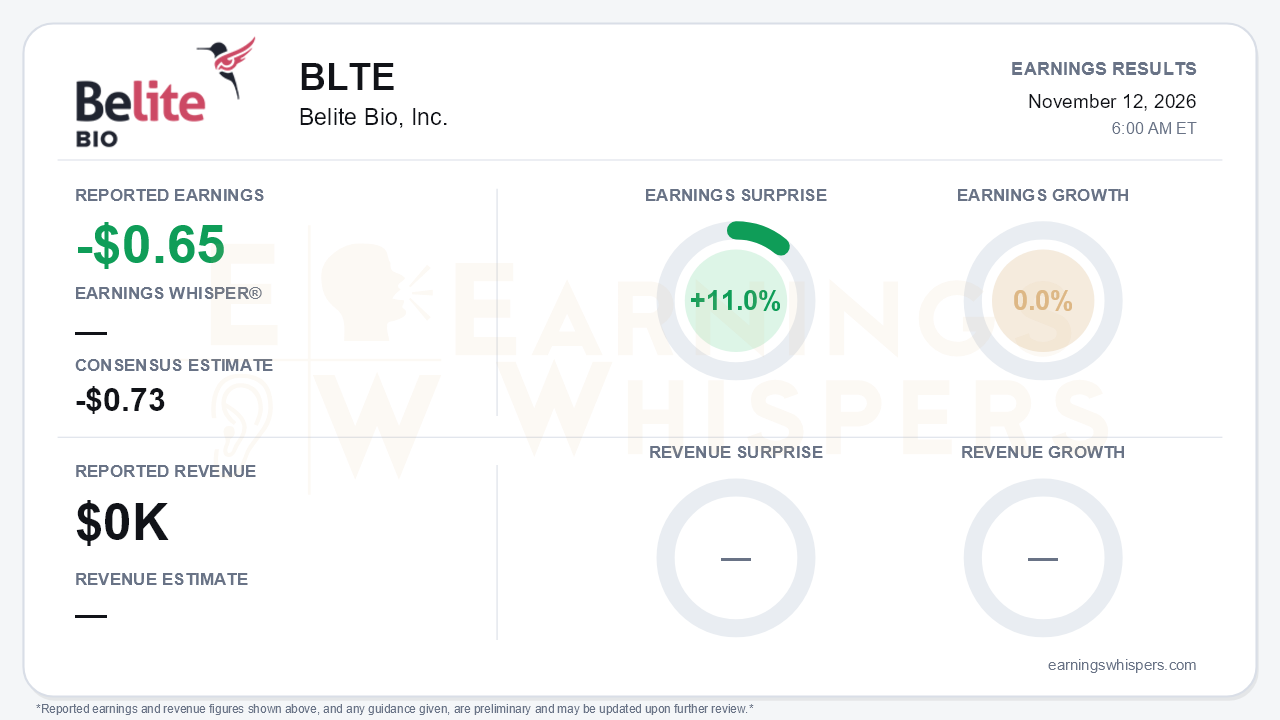
Belite Bio (NASDAQ: BLTE) posted a third-quarter loss of $0.65 per share against a consensus estimate of a $0.73 loss, an 11.0% beat, with earnings flat year over year at 0.0% growth on no revenue. For a pre-commercial biotech, the EPS beat is the least important part of the quarter. The real development is regulatory. The FDA told the company it will not convene an advisory committee for the tinlarebant NDA in Stargardt disease type 1 (STGD1). Management described the mid-cycle review as "incredibly smooth," and the February 12, 2027 PDUFA date remains intact. That is the clearest de-risking of the U.S. filing to date. It arrived alongside two developments bears can point to: rising spend and another delay in the geographic atrophy (GA) program.
The headline per-share figures deserve scrutiny. The company's own release shows a GAAP net loss of $30.3 million, or $0.75 per share, compared with $21.7 million, or $0.65 per share, a year earlier. Excluding share-based compensation, the non-GAAP loss was $0.60 per share, up from $0.26. Whichever basis investors use, losses widened in absolute dollars. Total GAAP operating expenses rose to $36.9 million from $23.0 million. Non-GAAP SG&A jumped to $16.3 million from $2.1 million a year ago. Interest income partly cushioned the step-up, as other income climbed to $6.7 million from $1.3 million on a much larger Treasury portfolio. Lower stock compensation also flattered the GAAP comparison: SBC fell to $5.9 million from $12.9 million, which masks how quickly cash-based costs are rising.
The sequential trend tells the same story. Non-GAAP SG&A has climbed from $5.7 million in Q1 to $10.9 million in Q2 to $16.3 million in Q3. The non-GAAP net loss has moved from $13.7 million to $21.6 million to $24.3 million. That is the cost of a launch build, and the call made clear the build is real:
- a fully staffed Japan team for self-commercialization;
- early payer and PBM engagement in the U.S.;
- a September Commercial Day and a new disease-awareness website.
Management kept its rare-disease pricing framing, previously referenced at roughly $350,000 to $500,000 per year. It also cited about 20,000 diagnosed U.S. patients against an estimated prevalence of 53,000, plus roughly 10,000 in Japan. Combined cash and Treasuries of about $774 million remain essentially unchanged from year-end and comfortably exceed the roughly $450 million launch-plus-pipeline budget management has referenced.
The ex-U.S. strategy also accelerated. Last quarter, management framed European filings as following FDA approval. Instead, Belite submitted a J-NDA under Japan's Sakigake designation and filed MAAs in the UK, Switzerland and Singapore via the Access Consortium, all ahead of the U.S. decision. Including Japanese patients in the now fully enrolled DRAGON II trial is intended to support the Japanese filing. The October uplisting to the Nasdaq Global Select Market adds to the sense of a company preparing to commercialize.
The risk side of the ledger is just as concrete. The PHOENIX interim analysis in GA has slipped repeatedly:
- second-half 2026;
- then year-end 2026;
- then Q1 2027;
- now deferred until after the PDUFA date, with the interim design still unconfirmed.
GA is the far larger commercial opportunity, so each slip pushes back the catalyst most capable of expanding the story beyond an orphan indication. The pediatric study for ages 3-11 has also drifted, from an April start to late 2026 after an additional IRB review. Management acknowledged bandwidth strain from running parallel regulatory reviews. It also described itself as "neutral" on label breadth for patients aged 12 and older and adults, a topic not yet discussed with the FDA.
The market had already turned cautious going into the print. Investor sentiment collapsed from a strongly positive 0.95 after the prior report to -0.48. That swing is large enough to signal a genuine reversal in expectations rather than noise. Shares closed at $155.94 ahead of the release. That is 12.9% below the open after the August report, 2.6% under the 200-day moving average, and 21.5% off the September 8 inter-earnings high of $198.58. The stock was trading about 10.6% above the November 6 low of $141.00. The Earnings Whispers trend readings lean negative, with sequential growth and AVWAP weak even as momentum has turned positive. The investor reaction suggests the market is weighing GA delays and rising spend more heavily than the de-risked FDA review.
The bottom line is that Belite Bio delivered what matters most for a pre-revenue company: a cleaner path to a potential first-ever STGD1 approval, with no advisory committee, a smooth mid-cycle review and an accelerated global filing footprint. The beat itself is thin cover for widening losses, and the GA program keeps losing time. Investors now hold a binary February catalyst that looks better positioned than it did three months ago. They are also holding a stock whose sentiment and technical setup show that much of September's enthusiasm has already been unwound.
Read our earnings preview for Belite Bio, Inc.: https://www.earningswhispers.com/article/BLTE/22967
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-05 | |
| Nov-05 | |
| Oct-19 | |
| Oct-14 | |
| Oct-01 | |
| Sep-28 | |
| Sep-11 | |
| Sep-08 | |
| Sep-04 | |
| Sep-01 | |
| Aug-24 | |
| Aug-21 | |
| Aug-14 |
