Intellicheck Meets EPS Estimates And Tops Revenue Forecasts, But The Largest-Customer Volume Loss Is Now Reaching The Top Line
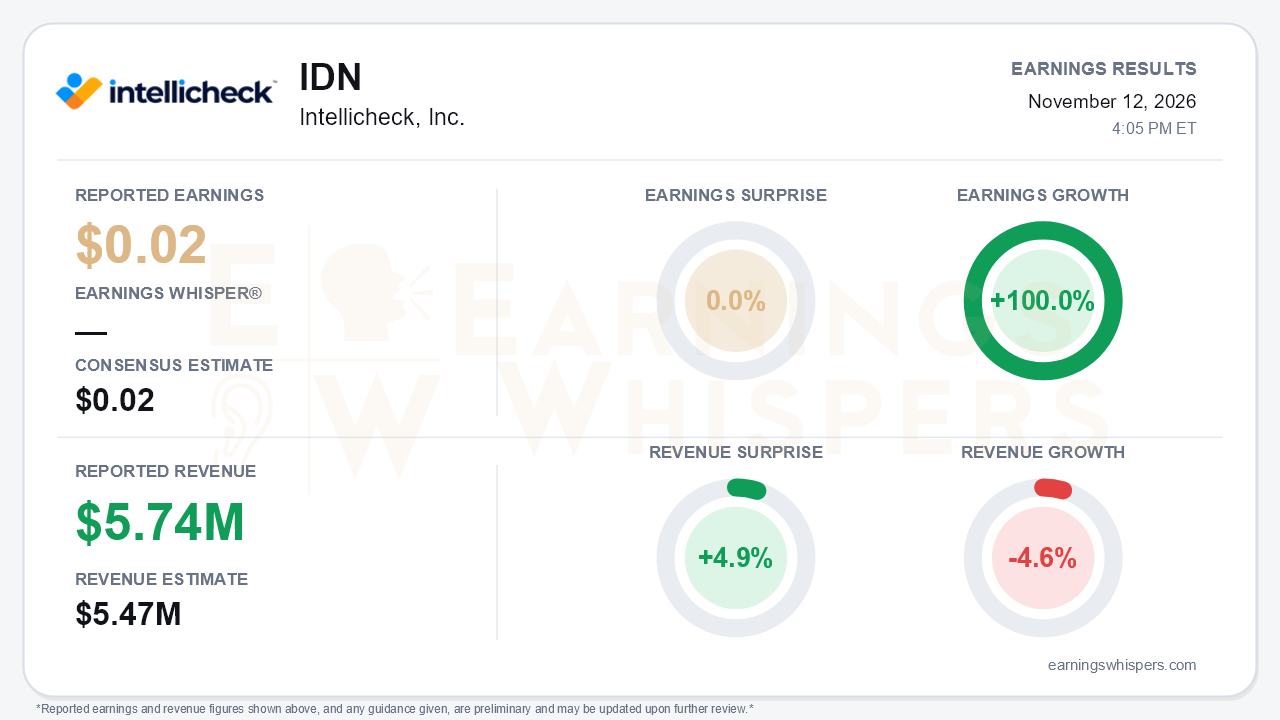
Intellicheck's third quarter looked steady at first glance. Earnings of $0.02 per share matched the consensus estimate and grew 100.0% from a year ago. Revenue of $5.74 million beat the $5.47 million consensus by 4.9%. The more important development is that revenue fell 4.6% year over year and about 3% sequentially. Earlier in the year, revenue grew 13% in Q1 and 16% in Q2. That is the central tension: profitability and cash generation keep improving, while the revenue engine has started to contract, and management's own disclosures suggest Q4 could be harder.
The quality of the earnings result deserves scrutiny. Net income rose to $471,000 from $290,000. The improvement came largely from spending discipline rather than growth. Operating expenses fell to $4.85 million from $5.21 million, helped by a roughly $220,000 cut in R&D. Other income, mostly on a larger cash pile, doubled to $104,000 and supplied a meaningful share of the year-over-year gain. Gross margin held near 91%. Adjusted EBITDA, a non-GAAP measure, rose to $892,000 from $631,000. However, the adjusted EBITDA margin slipped to about 15.5% from roughly 19% in Q2 and 17% in Q1. Sequential SG&A rose about $201,000 on legal and investor-relations fees and a stock-compensation catch-up. Management also noted that the year-ago quarter included non-recurring engineering revenue, which softens the year-over-year comparison somewhat. That explanation does not cover the sequential decline.
The call made clear that the largest-customer problem has moved from hypothetical to real. This customer accounted for about 29% of first-half revenue. The 10-Q discloses a 65% to 75% reduction in its scan volumes. That sharply contrasts with the Q2 call, when management said volumes were "nowhere near" a worst-case scenario. The CEO now concedes he cannot say Intellicheck will retain the business it had. Q3 absorbed only part of the lower run rate, while Q4 will carry it for the full quarter.
The rest of the business is not compensating the way it was. Growth excluding that customer slowed from 19% in the first half to 6% in Q3, partly because the company lapped a large Southeast regional bank win. Management also dropped its Q2 suggestion that full-year 2026 revenue could exceed 2025's $22.7 million. Nine-month revenue stands at $17.2 million, up 7%. Matching last year would require a Q4 that looks difficult given the full-quarter customer drag. Management declined to frame Q4 or 2027 growth. Instead, it pointed to channel partners and retail seasonality to fill the gap.
There is a credible pipeline of new catalysts, even if few are near-term revenue drivers:
- a channel deployment with one of the world's largest investment managers, marking the company's first move into wealth management;
- new partnerships with Agility Credit in auto lending and Conmito in freight check-in;
- a Desco collaboration that could reach roughly 500,000 U.S. scanners, aimed at small banks and credit unions;
- a bank client merger that added 300 branches;
- a renewal successfully defended against a PE-backed competitor that cut prices.
A large social media customer cut its unprocessable image rate from about 30% to 0.6%, but management still excludes it from forecasts. The largest customer also signed a new purchase order and remains committed to migrating to the newer API. These are reasons for hope rather than visible offsets.
The balance sheet buys time. Cash rose $1.3 million in the quarter to $13.2 million, the highest since late 2021, with no debt. Nine-month operating cash flow reached $3.3 million, up from $2.1 million a year ago, and deferred revenue climbed to $1.6 million from $1.2 million in Q2.
The market had already been pricing in the deterioration. Shares opened at $2.99 after the August report and stood at $2.37 heading into this release, down 20.7%. The stock sits roughly 46% below its 200-day moving average of $4.37. It hit a 52-week low of $1.95 on November 6 before rebounding about 21%, well short of the $3.31 quarterly high set in August. Investor sentiment moved more firmly into negative territory, falling from -0.24 to -0.48. The Earnings Whispers momentum and AVWAP trend readings also remain negative.
The bottom line is that Intellicheck delivered an in-line profit and a revenue beat that mask a business entering a revenue air pocket. Cost control, a debt-free cash position and an expanding partner list give the company room to absorb the loss of most of its largest customer's volume. However, Q3 showed that growth in the rest of the business has slowed sharply just as that hit arrives. The new partnerships now need to produce measurable revenue, and Q4 will show how quickly that can happen.
Read our earnings preview for Intellicheck, Inc.: https://www.earningswhispers.com/article/IDN/22923
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-04 | |
| Oct-30 | |
| Oct-29 | |
| Oct-20 | |
| Oct-12 | |
| Aug-19 | |
| Aug-13 | |
| Jul-28 | |
| Jul-07 | |
| Jun-22 | |
| May-27 | |
| May-20 | |
| May-20 |
