Heartflow Beats Big And Raises Again As Plaque Ramps, But A 51% Run Leaves Little Room For The Implied Q4 Slowdown
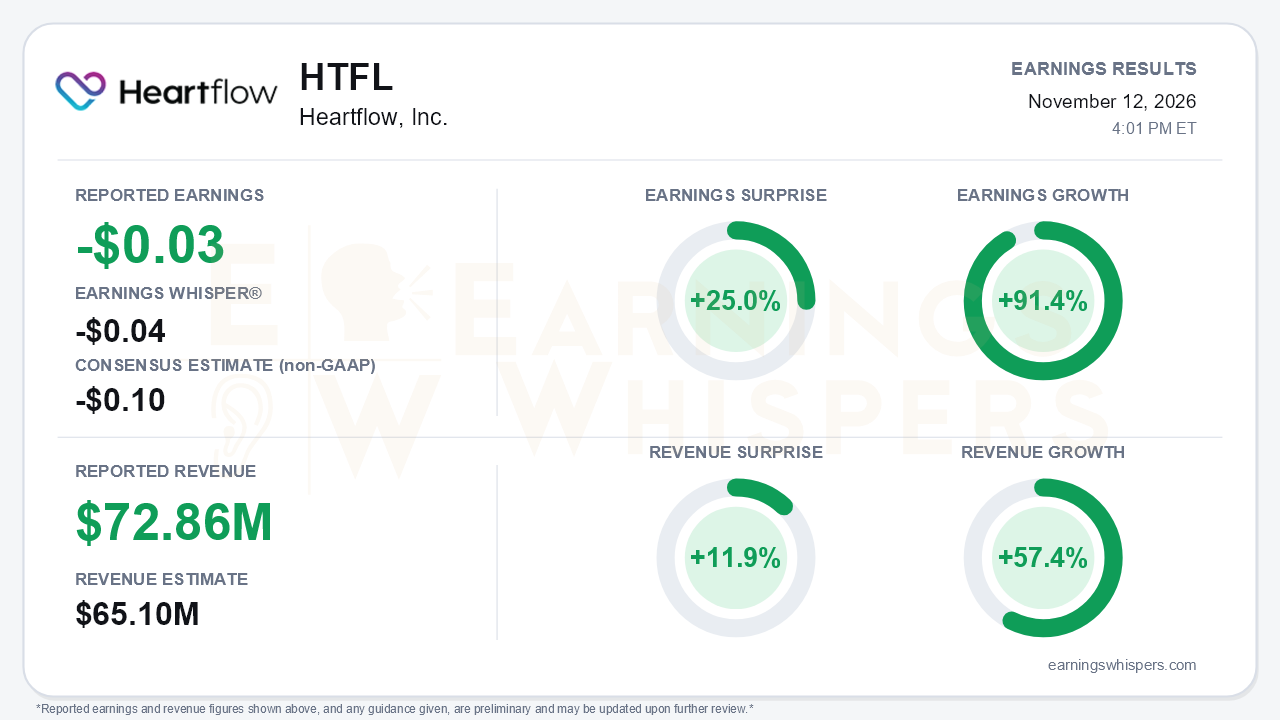
Heartflow delivered the kind of quarter growth investors pay for: a third straight quarter of accelerating revenue, a fourth consecutive full-year guidance raise, and losses that are shrinking quickly. The company posted a non-GAAP loss of $0.03 per share, well ahead of the -$0.10 consensus and a penny better than the -$0.04 Earnings Whisper number, a 25.0% earnings surprise. Revenue of $72.86 million topped the $65.1 million consensus by 11.9% and grew 57.4% year over year. Earnings improved 91.4% from a year ago. The beat was not in question. The central tension is that the stock had already priced in much of this good news. Shares entered the report near a 52-week high after a 51% run, and guidance implies growth will slow in the fourth quarter.
The quality of the quarter holds up well. Growth has stepped up sharply this year, from roughly 40% in Q4 2025 to 41% in Q1, 48% in Q2 and 57% in Q3. U.S. revenue rose 60%, its fastest pace in 11 quarters. Global case volume grew 89.5%. Plaque Analysis contributed $11.8 million, up from $7.8 million in Q2 and $3.2 million in Q1. Non-GAAP gross margin widened to 83.8% from 76.8% a year ago and 83.3% in Q2. Management credited case volume, Plaque mix and AI-driven productivity gains in production. Operating leverage is also visible. Non-GAAP operating expenses fell to about 91% of revenue from 110% in Q1, and the non-GAAP operating loss narrowed to $5.0 million from $15.5 million in Q1. The GAAP picture is less flattering. The GAAP loss was $0.13 per share, and stock-based compensation nearly doubled year over year to $7.6 million. Litigation costs added another $1.3 million. GAAP operating expenses still exceeded revenue.
The call reinforced that this is a broadening adoption story, not a single-product spike. Full-year revenue guidance rose to $262 million to $264 million, implying 49% to 50% growth. That compares with $246 million to $250 million last quarter and an initial range of $218 million to $222 million. Other targets moved up as well:
- Plaque revenue guidance climbed to $36 million to $37 million, from $15 million to $17 million at the start of the year.
- Plaque-activated accounts are now expected to reach roughly 1,300 by year-end.
- Covered lives for Plaque rose to 82%.
- Non-GAAP gross margin guidance edged up to about 82.5%, and the 85% mid-term target was reaffirmed.
- Management said it has increased confidence in reaching cash-flow profitability by mid-2028.
The catalyst slate is unusually rich. The P4 randomized trial, published in NEJM, showed that CT-guided PCI planning with Heartflow matched IVUS on one-year outcomes while cutting procedure time 27%. Heartflow also announced a Boston Scientific collaboration on PCI planning. DECIDE one-year data showed 34% fewer major cardiovascular events, and FUSION became the fourth randomized trial supporting FFR CT. Management also guided to a Plaque pricing step-up in Q1 2027 that it said is more than 10% above consensus. It expects 2026 new account additions to exceed the record 340 added in 2025.
Bears still have legitimate ammunition. Subtracting nine-month revenue from the annual guide implies fourth-quarter revenue of roughly $72.5 million to $74.5 million, barely above Q3 and a clear deceleration from the 57% pace. Several factors drive that slowdown:
- Plaque pricing is flat sequentially because 2026 contractual escalators are exhausted.
- FFR CT pricing declines are only expected to moderate in 2027.
- Holiday seasonality weighs on the quarter.
- FFR CT volume growth is running near 37%, well below total case growth.
Management itself cautioned that Plaque adoption will be steady, "not a hockey stick." Hiring of analysts and customer-success staff will partly offset 2027 gross margin gains. The IP litigation and DOJ civil investigative demand remain unresolved, with no update on the call.
The market setup is more complicated than the surprise implies. Shares closed at $59.10 before the report, up 51.3% from the open after the August release. That put them 69% above the 200-day moving average and within 3% of a $60.66 inter-earnings and 52-week high set the day before results. Investor sentiment remained positive but weakened meaningfully, falling from 0.59 to 0.31. Expectations appear to have grown more demanding even as the stock rallied. Earnings Whispers momentum and AVWAP trend readings remain positive, consistent with the strength in price.
The bottom line is that Heartflow's fundamentals improved on nearly every axis that matters: growth, Plaque uptake, gross margin, operating leverage and clinical evidence. Guidance was raised again with nothing cut. The challenge is that the stock entered the print stretched and near its highs, sentiment had already cooled, and the guide points to a softer fourth quarter before the 2027 Plaque price step-up arrives. The growth story is credible and strengthening. From here, the debate centers on how much of that improvement the stock has already priced in.
Read our earnings preview for Heartflow, Inc.: https://www.earningswhispers.com/article/HTFL/22922
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-04 | |
| Nov-02 | |
| Nov-01 | |
| Oct-19 | |
| Aug-28 | |
| Aug-27 | |
| Aug-14 |
This AI-Tied IPO Stock Just Broke Out On Its 'Outsized' Guidance Boost
HTFL +35.70%
Investor's Business Daily
|
| Aug-14 | |
| Aug-13 | |
| Aug-13 | |
| Aug-12 | |
| Jul-31 |
