HireQuest Misses On EPS As Accelerating Top Line Runs Into Rising Costs And Thinning Cash
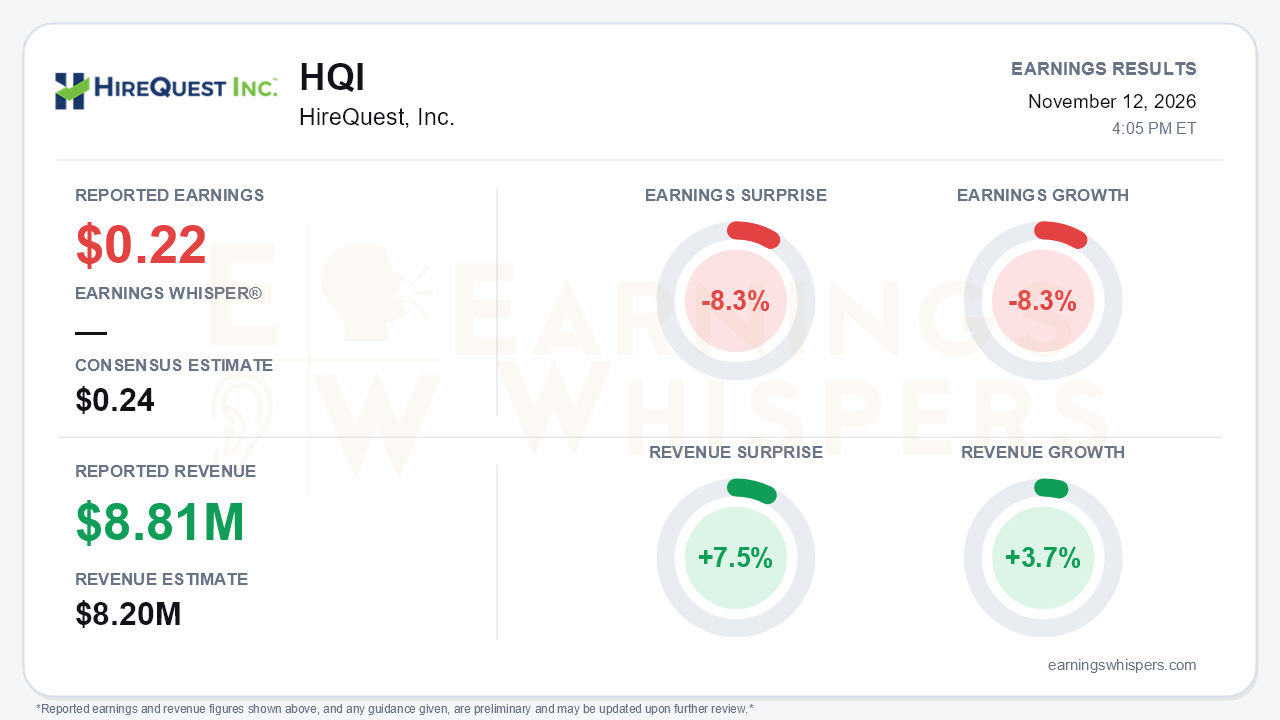
HireQuest's third quarter split cleanly in two. Adjusted earnings of $0.22 per share missed the $0.24 consensus by 8.3% and fell 8.3% from a year ago. Revenue of $8.81 million beat the $8.2 million estimate by 7.5% and grew 3.7% year over year. That is the central tension: the staffing recovery is broadening and, by management's account, accelerating into the fourth quarter, but the gains are not yet reaching the bottom line. Investors who bid the stock up through the late summer were paying for operating leverage, and this quarter did not deliver it.
The quality of the miss deserves scrutiny. Adjusted EPS already excludes the $1.3 million non-cash write-down of notes receivable, which was tied mainly to repossessing a franchised location that is now corporate-owned pending resale. So the shortfall came from elsewhere. Net workers' compensation was a $434,000 expense versus a $99,000 benefit a year earlier, and management cited medical inflation. The effective tax rate jumped to about 17% from 5.2% on lower WOTC benefits. Core SG&A fell from $4.6 million a year ago but rose sequentially to $4.4 million from $3.8 million in Q2. Including the write-down, GAAP net income fell to $1.7 million, or $0.12 per diluted share, from $2.3 million a year ago and $2.7 million in Q2. Adjusted EBITDA of $4.5 million was flat year over year, a sharp stall after Q2's 39% gain.
Beneath the headline, the revenue picture is better than the reported growth rate suggests. The January divestiture of the MRINetwork permanent-placement franchise base distorts the comparisons. Pro forma for that sale, total revenue rose 11.1% and system-wide sales rose 11.4%, up from 6.9% in Q2 and roughly flat in Q1. HireQuest Direct added $7.5 million in system-wide sales and Snelling added $6.6 million. Management said Q4-to-date system-wide sales are running up in the high teens year over year. It also pointed to five straight months of year-over-year growth in BLS temp employment. The call's tone has climbed steadily over the past year, from finding a bottom, to green shoots, to a clear industry tailwind. Management cited new drivers as well:
- warehouse automation retrofit projects;
- better capture of food-service work;
- a national-accounts team that now co-sells with franchisees;
- a recruiting app that wins projects outside the branch footprint.
Not everything accelerated, however. Pro forma franchise royalty growth slowed to 7.9% from 13.8% in Q2, even as system-wide sales growth sped up. The balance sheet is also absorbing the recovery. Cash fell to $1.1 million from $3.9 million at year-end, and $0.5 million is now drawn on the credit line. Accounts receivable swelled to $54.9 million from $39.3 million. Some of that is normal working-capital build in a growing franchise-funding model, and line-of-credit availability of roughly $40.5 million leaves ample liquidity. Still, the company also spent about $2.4 million repurchasing roughly 226,000 shares this year. Q3 also benefited from the absence of major hurricanes, a tailwind that may not repeat. There is no formal guidance, so the Q4 sales trend is a management observation rather than a commitment.
Two strategic threads add uncertainty. Management described the M&A pipeline as thawing, with three to five opportunities as sellers' price expectations normalize. Meanwhile, the $105 million bid for TrueBlue's PeopleReady on-demand business that featured in the first quarter went unmentioned, so there is no deal in hand. The franchise repossession also raises a question about franchisee credit quality, even as demand improves.
The market setup is more complicated than the surprise alone implies. Shares were up 24.1% from the open after the August report. They sat about 34% above the 200-day moving average and near the middle-to-upper part of the inter-earnings range. That leaves the stock 12.4% below the 52-week high of $20.84 set in late September and well above the $14.63 August low. Investor sentiment moved the other way, falling from -0.18 to -0.44 ahead of the report, a meaningful slide deeper into negative territory. Price momentum and AVWAP readings remain positive, so the stock has held much of its gain even as enthusiasm cooled. A margin-driven miss gives skeptics legitimate ammunition against a stock that had already re-rated.
The bottom line is that HireQuest's demand story improved this quarter, with accelerating pro forma system-wide sales and a strong Q4 start. Profitability, however, moved backward on workers' comp, taxes, sequential cost growth and a franchise write-down. The rally since August has priced in a recovery that the income statement has not yet shown. The next test is whether high-teens system-wide sales growth turns into royalty growth and EBITDA expansion, rather than more receivables and borrowing.
Read our earnings preview for HireQuest, Inc.: https://www.earningswhispers.com/article/HQI/22921
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-04 | |
| Oct-29 | |
| Sep-02 | |
| Aug-18 | |
| Aug-13 | |
| Aug-11 | |
| Aug-10 | |
| Aug-07 | |
| Jul-27 | |
| May-27 | |
| May-13 | |
| May-12 | |
| May-12 |
