HawkEye 360 Beats And Raises, But Slowing Organic Growth Keeps The Bounce Off October Lows Contested
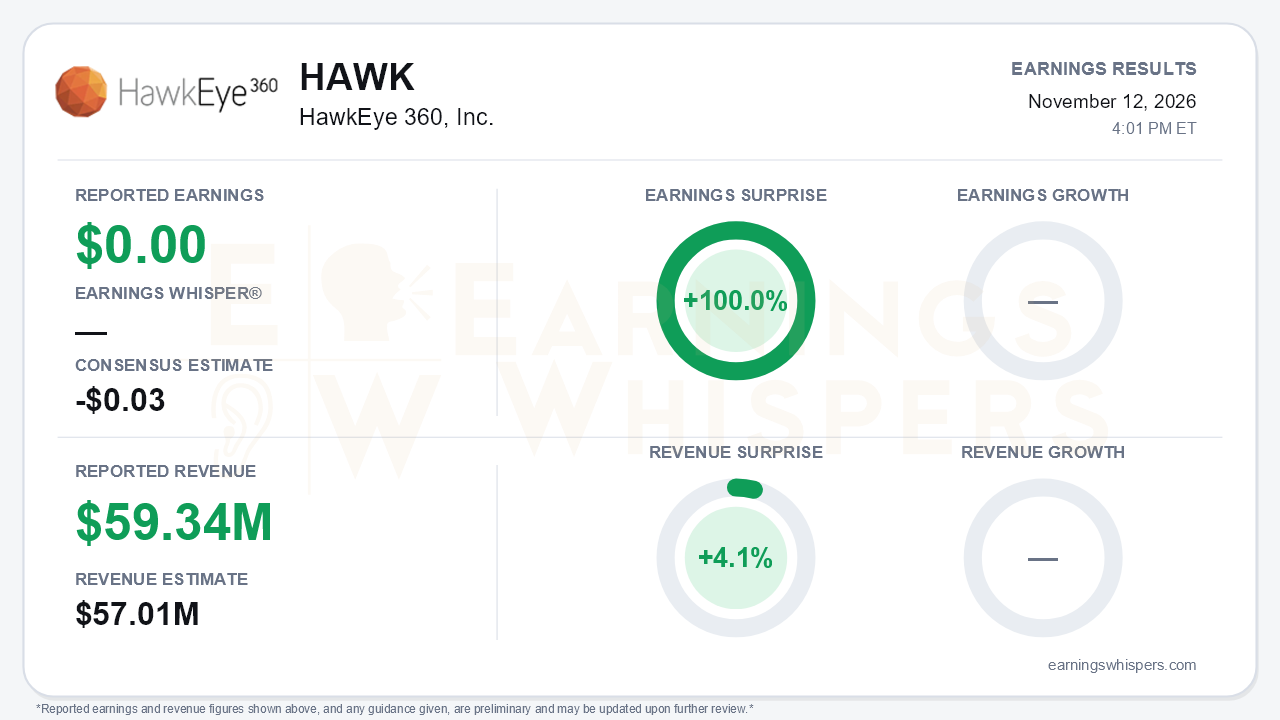
HawkEye 360 delivered the beat-and-raise quarter its post-IPO shareholders needed. Third-quarter results were breakeven per share against a consensus loss of $0.03, a 100.0% surprise. Revenue of $59.34 million topped the $57.01 million estimate by 4.1%. The company reported revenue growth of 84% year over year and 19% sequentially from $49.8 million in the second quarter. Management raised full-year revenue guidance to $225-$227 million from $215-$220 million. It lifted adjusted EBITDA guidance to $38-$40 million from $30-$36 million. The central tension is that the headline acceleration is heavily acquisition-assisted. Organic growth is cooling: excluding the ISA acquisition, revenue grew about 24% year over year versus 33% in the second quarter. International growth slowed to 76% from 134%.
The quality of the earnings beat deserves scrutiny. Breakeven EPS reflects a GAAP net loss of $0.2 million, compared with net income of $1.7 million a year earlier. The company posted an operating loss of $4.4 million versus operating income of $1.7 million last year. What closed the gap was $4.4 million of interest income on the roughly $495 million cash pile left from the IPO. Cost growth outpaced revenue:
- Direct cost of sales tripled to $17.1 million.
- SG&A more than doubled to $24.3 million.
- Stock-based compensation jumped to $7.4 million from $1.3 million.
On a non-GAAP basis the story is genuinely better. Adjusted EBITDA reached $13.3 million at a 22% margin, up from $7.0 million and 14% in the second quarter. That beat management's earlier signal that third-quarter EBITDA would look similar to the second quarter. Cash generation was thin, however. Free cash flow was just $137 thousand, down from $5.4 million in the prior quarter, as capital spending on satellites continued.
The call preserved a credible demand story. International revenue hit a record $23.3 million, up 11% sequentially and entirely organic. U.S. government revenue rose 25% from the second quarter, and legacy U.S. revenue improved 14% sequentially. Legacy U.S. is still down $2.5 million year over year, though that is an improvement from a $3.2 million decline last quarter. Bookings and pricing also supported the outlook:
- Backlog edged up to $300.3 million from $292.2 million on a book-to-bill of about 1.1x.
- Management cited a double-digit blended pricing tailwind per collection.
- Clusters 15 and 16 launched on schedule in October, with all six satellites contacted. Management expects revisit rates to improve to roughly 30-37 minutes from 35-45 minutes.
The bigger forward-looking development came after quarter-end. HawkEye 360 signed $135 million in new contracts, more than $70 million of them European follow-ons and about $60 million restricted U.S. government work. Management said these awards effectively secure 2026 and provide strong 2027 visibility, though most of the revenue flows into 2027 and beyond. Other catalysts include:
- The NRO operational augmentation contract, which makes HawkEye 360 the first commercial RF provider to move beyond test and evaluation.
- A Space Force radar warning sensor selection for ISA.
- The new Luxembourg subsidiary.
- Partnerships with Leonardo and ERA, which deepen the push into sovereign European defense.
The risks have not disappeared, and bears have legitimate ammunition. Management flagged several:
- Possible U.S. budget delays or a continuing resolution after the midterms.
- Long, ITAR-gated international sales cycles.
- Tightening rideshare launch capacity beyond 2028.
- Execution risk on the first Block 3 launch in Q1 2027.
The guidance math also deserves attention. Nine-month adjusted EBITDA was $27.7 million, so the raised full-year range implies fourth-quarter EBITDA of roughly $10-$12 million. That is below the third quarter's $13.3 million, consistent with management's warning that stepped-up investment spending means the 22% margin should not be extrapolated.
The market setup is more complicated than the surprise implies. Shares opened at $24.00 after the August report and stood at $15.26 the day before this release, down 36.4%. That leaves the stock about 25% below its 200-day moving average of $20.46 and 38% below the inter-earnings high of $24.71. Shares hit a 52-week low of $11.25 on October 23 and have since rebounded about 36% off that trough. Investor sentiment remained positive but weakened sharply, falling from 0.65 to 0.27 heading into the report. That suggests much of the post-IPO enthusiasm had already been wrung out. AVWAP-based trend readings remain negative, underscoring how much ground the stock has to recover.
The bottom line is that HawkEye 360 delivered a clean beat-and-raise backed by better adjusted margins, growing backlog and a $135 million post-quarter award haul that improves 2027 visibility. The quarter's weaknesses sit beneath the headline: decelerating organic and international growth, a breakeven result propped up by interest income, near-zero free cash flow, and implied fourth-quarter margin compression. With sentiment already deflated and shares well below their long-term average, the report gives the company room to rebuild credibility. Proving the growth story requires organic momentum to stabilize rather than lean on acquisitions and IPO cash.
Read our earnings preview for HawkEye 360, Inc.: https://www.earningswhispers.com/article/HAWK/22920
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-10 | |
| Nov-04 | |
| Oct-29 | |
| Oct-23 | |
| Oct-20 | |
| Oct-15 | |
| Oct-13 | |
| Oct-08 | |
| Sep-24 | |
| Sep-17 | |
| Sep-17 |
