Digimarc's Pipeline Accelerates While Revenue, ARR And Cash Burn Keep Deteriorating
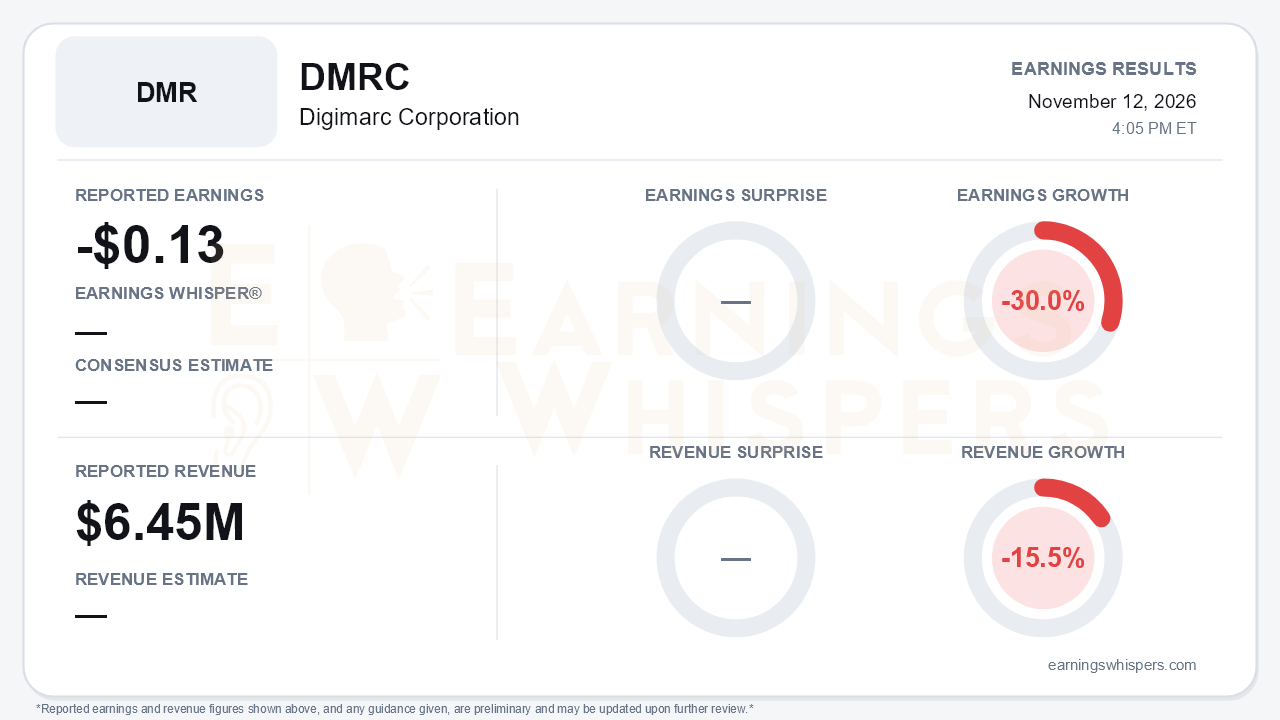
Digimarc's third quarter put the company's two stories side by side. On the reported numbers, the business is still shrinking. The non-GAAP loss widened to $0.13 per share from $0.10 a year earlier, a 30.0% decline in earnings. Revenue fell 15.5% to $6.45 million. On the commercial side, new CEO Paul Carreiro described pipeline converting to signed business "earlier than expected." No consensus estimate was available, so the useful test is not a beat or a miss. It is whether the commercial momentum can catch the financial decline before it costs more. Right now it has not, and that is the central tension.
The quarter got worse on several fronts, and not only against last year. Revenue has fallen every quarter: $8.9 million in Q4 2025, then $7.6 million, $7.4 million and now $6.4 million. The non-GAAP loss also widened in sequence, from $0.07 in Q1 to $0.08 in Q2 to $0.13 in Q3.
Subscription revenue fell to $3.2 million from $4.6 million a year ago. Two causes accounted for most of the drop:
- a commercial contract that expired in October 2025;
- a contract that stepped down in June 2026.
The same two events explain the slide in ending ARR. ARR fell to $10.8 million from $15.8 million a year earlier and from $11.6 million just one quarter ago. The new business so far is not offsetting those losses: only $0.7 million of net ARR additions came from new and existing contracts.
The GAAP picture is slightly better. The net loss narrowed to $0.36 per share from $0.38, helped by lower operating expenses, smaller stock-based compensation and lower bad-debt expense. Margins were mixed:
- Non-GAAP gross margin held at a strong 82%.
- Subscription gross margin slipped to 87% from 89% in Q2.
- Non-GAAP operating expenses were essentially flat sequentially at $8.0 million.
Cost discipline is not the problem. The revenue base is.
The call explained why management sounded more confident even as the numbers weakened. The gift card program has become a real deployment story:
- Retailer engagement rose to 68+, up from 31 in Q2, 15 in Q1 and 8 in Q4 2025.
- Schnucks is live at 115 stores and Stater Bros at 165.
- Food City has begun rolling out.
- Kroger started a five-store kickoff in October, with a 500-store expansion targeted for Q1 2027.
- Management is targeting more than 1,000 additional stores across other retailers in the first half of 2027, and expects another large retailer to kick off in Q4.
The quarter also added a European CPG authentication win worth more than $1.1 million in expected annual ARR. That deal was signed in Q4, so it is not in the reported numbers. It covers only 2 of the customer's 24 regions, which gives it obvious expansion potential. Carreiro said he was "even more confident than my first call." That is a notable shift from Q2, when management withdrew its target of significant 2026 ARR growth and told investors not to expect upside this year.
Bears still have legitimate ammunition. Carreiro admitted that visibility into 2027 bookings and revenue is not yet where he wants it. He also said new sales reps will not be fully productive until Q1 or Q2 2027, and that limited engagement with the existing customer base has hurt retention. No formal guidance was provided. Gift card rollouts also depend on scanner software availability and retailer scheduling, neither of which Digimarc controls.
The ARR math is the core issue. A single $1.1 million win is meaningful for a company with $10.8 million in ARR, but it is roughly what the base lost in one quarter.
The balance sheet improved, but at a cost. An $18.2 million registered direct offering lifted cash and investments to $22.1 million, from $8.8 million at the end of Q2. That buys runway, but it diluted shareholders. Meanwhile, free cash flow burn widened to $4.3 million from about $1 million in Q2. Management attributed part of that to reorganization and CEO-transition payables, which suggests some of the increase should not repeat. Still, a quarterly burn above $4 million against $22 million of cash leaves limited room for the 2027 ramp to slip.
The market context offers only partial guidance because current price and sentiment data were not available. Shares opened at $6.30 after the August report, below the 200-day moving average of $7.15. That suggests the stock was already being treated as a show-me story before this report. Little in Q3 changes that status, because the progress was in pipeline rather than reported results.
The bottom line is that Digimarc delivered a quarter with better commercial momentum and worse financial results. Store rollouts, retailer engagement and the European CPG win give the turnaround a more credible narrative than it had three months ago. However, ARR, revenue, losses and cash burn all moved the wrong way, and management concedes 2027 visibility is limited. The equity raise buys time to prove the strategy. The next test is whether ARR stabilizes and begins growing as signed deals and store deployments turn into recurring subscription revenue.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Oct-27 | |
| Oct-26 | |
| Oct-07 | |
| Sep-30 | |
| Aug-13 | |
| Aug-13 | |
| Aug-03 | |
| Jul-27 | |
| Jul-06 | |
| Jun-08 | |
| May-28 | |
| May-15 |
