Caliber Holds Platform EBITDA Positive But Cuts 2026 Revenue Outlook As Tighter Credit Tightens The Liquidity Squeeze
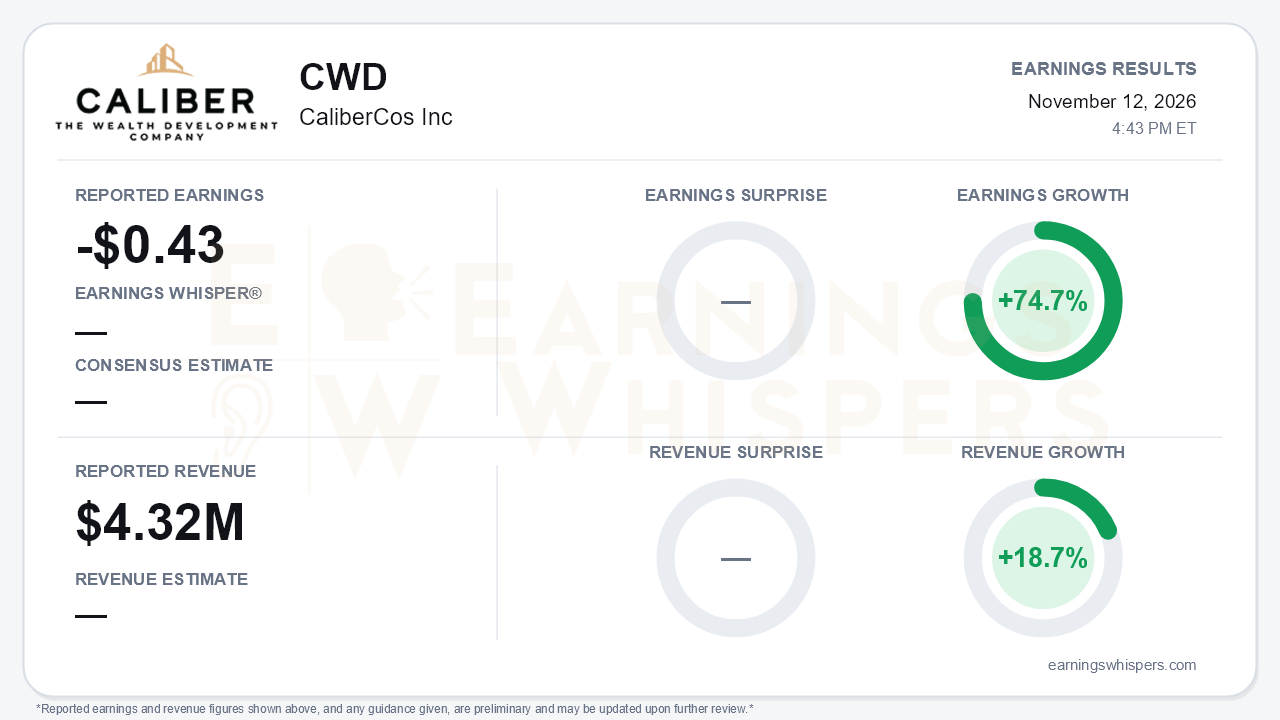
CaliberCos (NASDAQ: CWD) reported a third-quarter loss of $0.43 per share on revenue of $4.32 million. Earnings improved 74.7% year over year and revenue grew 18.7%, with no consensus estimate available. The headline improvement looks better than the underlying change. The more important news is that management cut full-year revenue guidance for the first time and withdrew its net operating income outlook. Lenders that seemed to be reopening in the first half have, in management's words, moved "back in a defensive posture." Cost discipline is keeping the asset-management platform marginally profitable. It is not solving a balance sheet that remains the central risk.
The quality of the per-share improvement deserves scrutiny. The $0.43 loss is the Platform figure. Platform net loss was essentially unchanged at $4.3 million versus $4.4 million a year ago. The per-share gain reflects weighted shares rising to 10.3 million from 2.6 million, which means dilution, not earnings power. On a consolidated GAAP basis, the loss attributable to Caliber widened to $5.0 million, or $0.49 per share. That figure includes a $0.7 million out-of-period correction. Both figures absorbed a $3.9 million non-cash tax provision. Below that line, the picture is more mixed:
- Platform pre-tax loss shrank to $0.4 million from $4.4 million.
- Much of that improvement came from a $1.6 million mark-to-market gain on the company's LINK token holdings, versus a $0.7 million loss last year.
- Interest expense fell by about $0.5 million.
The 18.7% consolidated revenue growth is also flattered by consolidating the Riverwalk and Commons Fundco entities. Platform revenue, the measure management emphasizes, grew a more modest 9% to $3.8 million. Fund management fees rose to $3.1 million, about 82% of revenue. Financing fees fell to $64,000 from $207,000.
That 9% Platform growth is a genuine re-acceleration from a 10% decline in the second quarter. Platform Adjusted EBITDA stayed positive for a second straight quarter at $0.1 million, an $0.8 million year-over-year improvement. Platform expenses fell 3% and general and administrative costs dropped sharply. However, EBITDA slipped from $0.3 million in Q2, so the profitability trend is holding rather than building. Fundraising was the clearest bright spot:
- The wholesale channel had its best quarter in more than three years, with $8.4 million raised from nine firms.
- Direct fundraising more than tripled sequentially.
- Managed capital edged up to $498.3 million, though it remains 1.5% lower year over year.
The guidance reset is where the tone changed. Full-year Platform revenue is now expected at $15 million to $17 million, down from $18 million to $22 million. Management attributed the cut to tighter credit after the September Fed hike, which pushed several financings, including the Canyon HUD loan and the Encore/Johnstown construction loan, into early 2027. The new range assumes no improvement in financing conditions. That is a conservative cushion, but it is a sharp reversal from first-quarter commentary that financing had not been better in two years. Management reaffirmed only that the platform will be Adjusted EBITDA-profitable for the year.
Tokenization is the story management wants investors to focus on. Four tokenized offerings are now live with up to $110 million in maximum offered equity, above the $100 million target. The new Caliber Tokenization Services unit is pitched as a partner-driven, low-overhead business serving family offices. It remains a pre-revenue narrative, while the liquidity problem is concrete:
- The call carried going-concern language.
- Parent cash stood at $1.8 million against $18.7 million of notes matured or maturing within twelve months.
- Stockholders' equity attributable to Caliber turned to a $3.6 million deficit.
The note program is making real progress. According to the release, payoff options now cover $14.8 million of notes, $13.6 million of which mature within a year and could be retired for about $10.9 million. Call figures were slightly different. The cash to exercise those options is not yet committed. Add a Nasdaq minimum-bid deficiency with a February 17, 2027 deadline and possible market-value issues, and further dilution looks like a realistic part of any resolution. The CFO role also remains on an acting basis.
The market has treated the stock as a distressed situation. Shares opened at $0.58 after the August report and spiked to $1.08 on September 22. They then collapsed to a 52-week low of $0.37 on October 26, well beneath the $0.83 200-day moving average. Investor sentiment entering this report was slightly negative at -0.07, more indifferent than hostile. The Earnings Whispers trend readings are mixed, with price and momentum neutral and AVWAP still negative.
The bottom line is that Caliber delivered operating improvement that bears and bulls can both cite. Platform revenue re-accelerated, fundraising strengthened and EBITDA stayed positive. But per-share gains reflect dilution, pre-tax improvement leaned on a crypto mark, and the guidance cut shows how dependent the fee model remains on credit markets. Until the company funds its note payoffs and resolves its listing issues, the balance sheet, not tokenization, will likely define the investment case.
Read our earnings preview for CaliberCos Inc: https://www.earningswhispers.com/article/CWD/23011
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-06 | |
| Nov-04 | |
| Oct-30 | |
| Oct-19 | |
| Sep-14 | |
| Aug-27 | |
| Aug-17 | |
| Aug-13 | |
| Aug-13 | |
| Aug-12 | |
| Jul-31 | |
| Jul-16 | |
| Jul-02 |
