Beeline's Core Mortgage Business Improves, But Thin Liquidity Leaves The Story Riding On The TYTL Deal
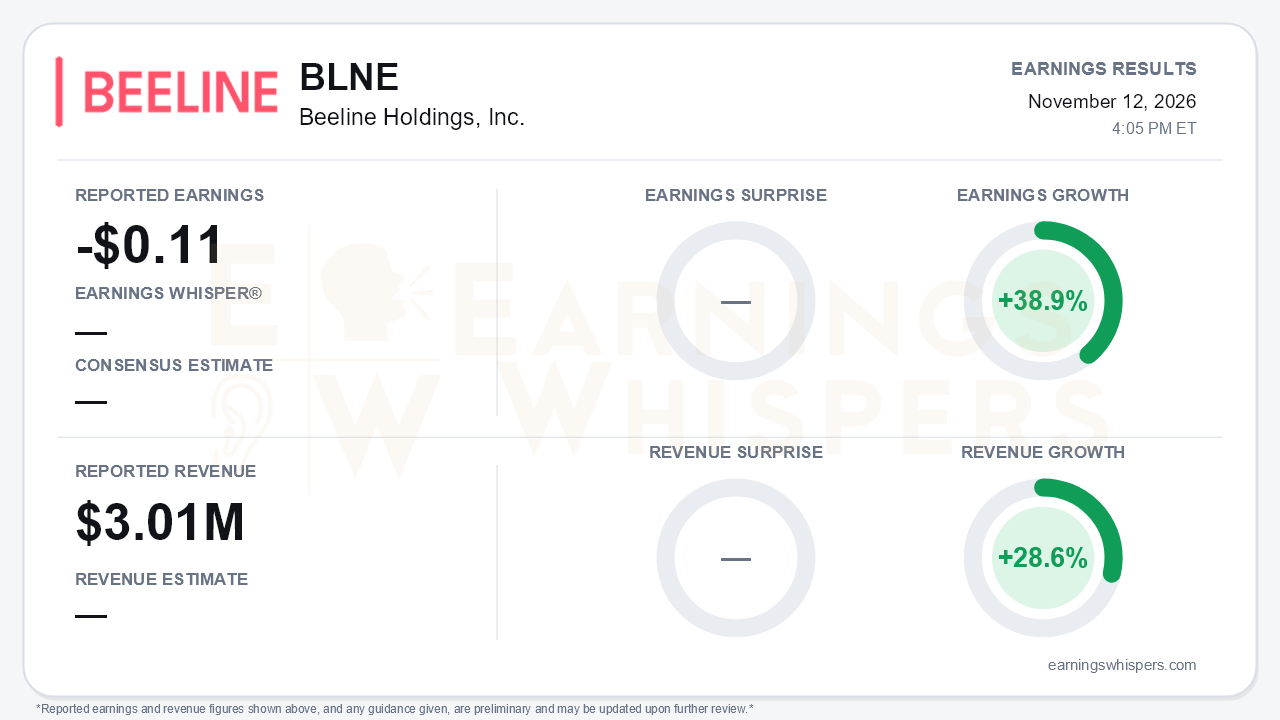
Beeline Holdings (NASDAQ: BLNE) reported a third-quarter loss of $0.11 per share on revenue of $3.01 million, an earnings improvement of 38.9% year over year on revenue growth of 28.6%. There was no consensus estimate or Earnings Whisper to measure against, so the quarter has to be judged on its own trajectory. On that basis the core mortgage business is getting better. Margins, conversion and cost discipline all improved, and this was the first quarter of 2026 in which revenue rose while operating expenses fell. That is the central tension. Operating progress is now outpacing the company's financial cushion, and the equity story increasingly depends on a merger that has not yet been signed.
The headline figures show genuine progress, but the quality of that progress deserves scrutiny. Revenue rose 15% sequentially from $2.6 million, which management called the strongest level since 2021. Overall mortgage margin expanded for a third straight quarter, from 2.78% in Q1 to 3.07% in Q2 and 3.56% in Q3, and reached roughly 3.67% in October. Operating expenses declined from $7.9 million in Q1 to $7.1 million in Q2 and $6.8 million in Q3.
The bottom-line improvement is more modest than the non-GAAP figures suggest. The adjusted EBITDA loss narrowed to $1.8 million from $2.6 million in Q2 and $2.7 million a year ago. Over the same period, the GAAP net loss barely moved, at $3.8 million versus $4.0 million in both comparison periods. Much of the gap reflects $1.1 million of stock-based compensation that did not exist in the year-ago quarter, plus $845,000 of depreciation and amortization. G&A also rose sequentially on legal and special-committee costs. The company cites 30% revenue growth, slightly above the normalized 28.6%, but either way growth decelerated sharply from 57% in Q2.
The call showed a business deliberately trading volume for quality. Non-QM loans, mainly DSCR and bank-statement products, rose to about 90% of units from roughly 80% in Q2. Loans closed rose 11% to 268, and revenue per loan increased 5% sequentially and 15% year over year. Lead volume fell about 28%, yet management said lead-to-close conversion improved more than 50%, crediting the now-consolidated Magic Blocks AI platform. The weaker data points matter, though. Dollar volume was flat at roughly $67 million. Beeline Equity generated just $20,000 in revenue despite earlier talk of Q3 scaling. The $100 million run-rate target for end-2027, stated in Q1, was not reiterated.
The forward-looking picture is split between catalysts and constraints.
On the catalyst side:
- **TYTL merger.** The deal has moved from a non-binding LOI to definitive agreements that management expects "within days." It would pair Beeline's mortgage and title infrastructure with TYTL's blockchain securitization platform, with plans to tokenize mortgage assets starting in 2027.
- **Dilution offsets.** CEO Nick Liuzza will cancel about 3 million of his roughly 9 million merger shares. Another third of his shares are tied to $100 million and $200 million market-cap milestones.
- **New products.** Closed-end second mortgages and HELOCs extend Beeline into home equity products that are less rate-sensitive.
- **Cost cuts.** A new roughly $250,000-per-month plan reaches full run-rate on December 1, and U.S. payroll is down 35% in November.
The risks are more immediate:
- **Cash runway.** Cash was only $2.1 million at September 30, against a $1.8 million quarterly adjusted EBITDA loss. The company continues to rely on its ELOC/ATM facilities and CEO funding.
- **Warehouse capacity.** A $5 million line was not renewed in October, cutting capacity to $20 million.
- **Fourth-quarter conditions.** Management framed Q4 around normal seasonality and 30-year rates near 7%, and offered no formal guidance.
- **Deal timing and execution.** TYTL has already slipped from the early-Q4 close implied last quarter. It still needs shareholder approval, and TYTL must arrange financing to meet closing conditions.
Investors have not been rewarding the operating improvement. Earnings Whispers sentiment deteriorated meaningfully, from -0.48 to -0.60, moving deeper into negative territory. Shares entered the report at $0.62, down 42.8% from the $1.09 open after the August release and about 60% below the 200-day moving average of $1.57. The stock sits just 7% above its 52-week low of $0.58, set October 30, and roughly 46% below the inter-earnings high of $1.15 from early September. The internal trend readings are mixed: momentum is positive, but AVWAP remains negative. The market appears to be pricing financing and dilution risk rather than margin gains.
The bottom line is that Beeline delivered its cleanest operating quarter of the year, with higher revenue, wider margins, lower costs and better conversion. Even so, the GAAP loss barely moved, growth is decelerating, and $2.1 million of cash leaves little margin for error. Bears have legitimate ammunition on liquidity, dilution and a TYTL deal that has already missed its timeline. Bulls need the merger signed and the cost cuts to show up in Q4 before the improving fundamentals can change the stock's trajectory.
Read our earnings preview for Beeline Holdings, Inc.: https://www.earningswhispers.com/article/BLNE/23006
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-06 | |
| Oct-20 | |
| Oct-07 | |
| Oct-07 | |
| Oct-06 | |
| Oct-06 | |
| Oct-02 | |
| Sep-24 | |
| Sep-23 | |
| Sep-23 | |
| Sep-22 | |
| Sep-18 | |
| Sep-18 |
