Birchtech's Core Product Business Improves, But The Rejuvenation Story Slips Again
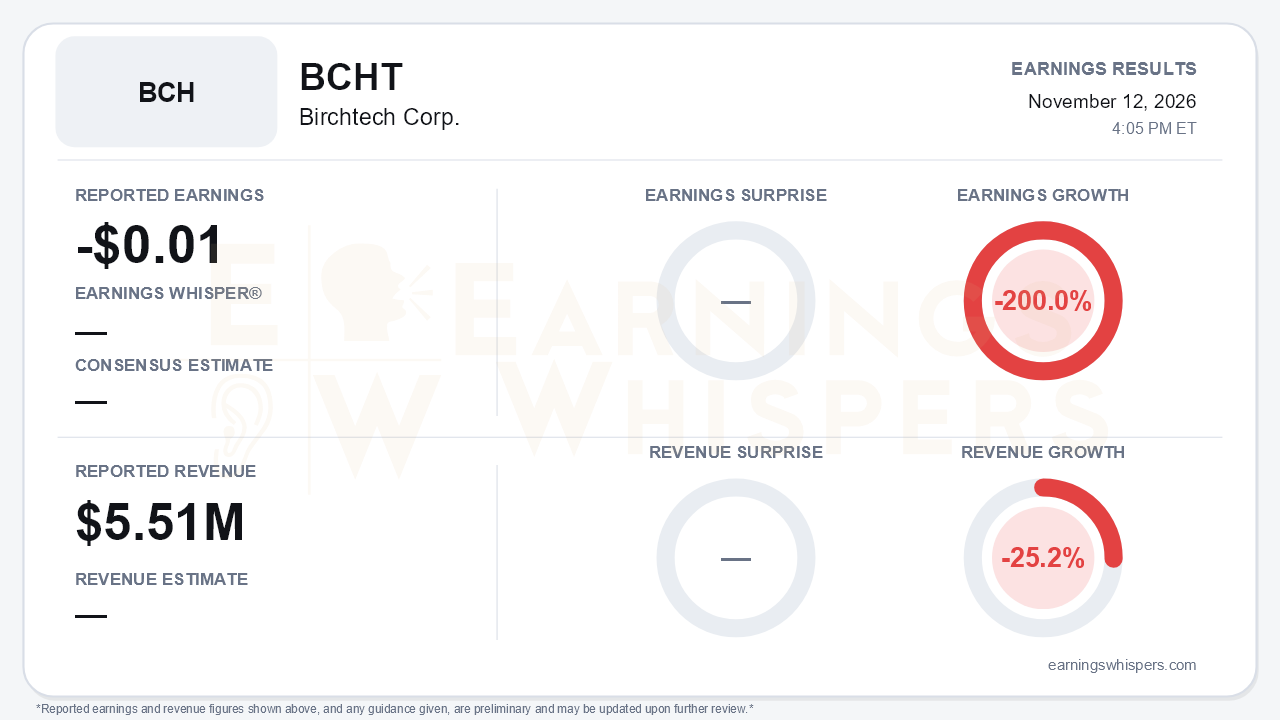
Birchtech Corp. (NYSE American: BCHT) reported a third-quarter loss of $0.01 per share on revenue of $5.51 million. Earnings fell 200.0% year over year and revenue declined 25.2%, reversing the year-ago profit of $0.04 per share. No consensus estimate was available, so there is no beat or miss to judge. The year-over-year comparison is also misleading. Last year's quarter included $2.6 million of one-time up-front license fees. Strip those out, and Birchtech's core product business is moving in the right direction. Product revenue rose 15.7% to $5.5 million, and the loss narrowed sharply from the second quarter. The central tension is that operating results are steadily improving while the strategic catalysts investors have been waiting on keep slipping.
The quality of the quarter is better than the GAAP swing suggests, but it deserves some scrutiny. Revenue rose 45% sequentially from $3.8 million in Q2 and was up from $4.2 million in Q1. The growth came from stronger coal-fired generation demand in the mercury emissions business, which management tied to extreme weather, higher natural gas prices and data-center load. Water treatment also contributed sales, compared with none a year ago. SG&A fell 35% to $1.8 million on sharply lower legal fees, down from $2.1 million in Q2. The net loss narrowed to $0.3 million from $3.0 million in Q2. Adjusted EBITDA was a $0.5 million loss, versus a $1.9 million loss in Q2. The net loss was smaller than the adjusted EBITDA loss, which is worth noting. That gap reflects a $252,000 gain from the change in fair value of the profit-share liability plus interest income, so the GAAP bottom line was flattered by non-operating items.
Margins tell the structural story. Gross margin was 29.9%, compared with 54.8% a year ago when high-margin licensing revenue was in the mix. That figure improved from roughly 27% in Q2 but remained below Q1's roughly 33%. Without new licensing events, Birchtech is a sub-30% gross margin carbon supplier. On those economics, even healthy product growth only gets the company close to breakeven. Management's plan to convert licensed coal-fired utilities into recurring SEA supply customers is therefore central to making the air business the "self-funding engine" the CEO described.
The new catalyst of substance is in water. Birchtech signed a granular activated carbon supply agreement with an industry partner. It expects to begin supplying water treatment customers in early 2027 at 2,000 tons per year, and the call indicated the arrangement could scale to about 10,000 tons per year. Management framed the deal as a faster, capital-free entry into water than the reactivation acquisition it had pursued. That acquisition, announced as a non-binding term sheet in September, was terminated.
That substitution is where bears have legitimate ammunition. On the Q2 call, management promised hard news on Carbon Rejuvenation offtake by the end of September. None arrived. Facility placement announcements have now been pushed to "before year-end," and any plant still needs an 18-24 month build once a decision is made. Meaningful rejuvenation revenue therefore looks like a 2028-or-later event. The EPA's proposed extension of PFAS compliance timelines adds further risk to that timing. Management said large systems will likely work toward a 2030-31 timetable.
The litigation track is also moving forward, but slowly. Birchtech filed its appellee brief defending the roughly $78 million judgment, and post-judgment interest continues to accrue. The remaining Iowa consolidated case has been remanded to Missouri with the stay lifted, which opens a path to settlement. However, the Q2 hope for an appeal ruling this year looks increasingly stretched.
The balance sheet holds $10.8 million in cash and no debt. That is down from about $11.8 million at the end of Q2, and management expects quarterly cash use to stay in a similar range. The company has also started its $5.0 million buyback, purchasing 103,864 shares at an average of $1.64. That price was above the $1.41 opening after the Q2 report but below the stock's $1.76 200-day moving average. In other words, management was buying in a range where the market had not yet re-rated the shares despite the judgment overhang.
The bottom line is that Birchtech delivered a cleaner operating quarter than its headline earnings and revenue declines imply. Product growth, lower legal costs and sharply narrower losses show a core business moving toward breakeven. The investment case, however, still rests on events outside the quarterly numbers: collecting the $78 million judgment, placing rejuvenation facilities and ramping the water business. On two of those three, timelines slipped again this quarter, so the year-end rejuvenation announcement management has promised is now a credibility test.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-02 | |
| Oct-29 | |
| Oct-01 | |
| Sep-22 | |
| Sep-10 | |
| Sep-09 | |
| Sep-08 | |
| Aug-14 | |
| Aug-13 | |
| Aug-12 | |
| Aug-07 | |
| Aug-06 | |
| Jun-10 |
