INNOVATE's Debt Cut Comes At The Cost Of Its Earnings Engine: DBM Global Sale Leaves A Small, Loss-Making Portfolio
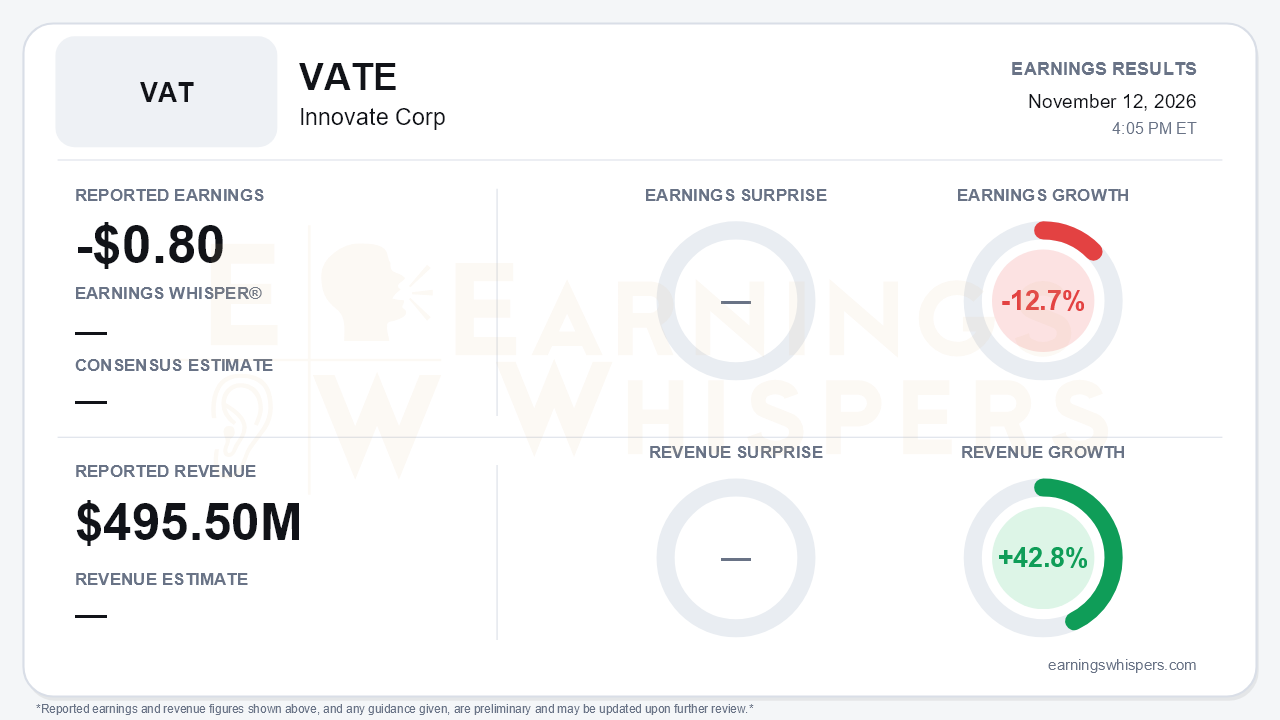
INNOVATE's third quarter was less an earnings event than a structural break. Revenue rose 42.8% year over year to $495.5 million. On the Earnings Whispers normalized basis, however, the company lost $0.80 per share, and earnings fell 12.7% from the prior-year quarter. That figure conflicts sharply with the GAAP diluted profit of $1.10 per share, a reversal of last year's $0.71 loss. The reconciling issue is quality. GAAP net income leaned on a $32.9 million gain from selling a controlling interest in HC2 Broadcasting, which flattered the bottom line. Meanwhile, a $10.3 million deemed dividend on R2's preferred stock, a $7.7 million rise in interest expense and a $10.0 million increase in tax expense ate into it. Without the one-time gain, the quarter does not support the profitability the GAAP headline implies. No consensus estimate was available, so there is no beat or miss to frame.
The bigger story is that this was DBM Global's final quarter under INNOVATE's ownership, and it went out strong. DBMG revenue jumped 45.0% to $490.6 million, essentially all of consolidated revenue. Segment net income attributable to INNOVATE nearly tripled to $25.2 million, and adjusted EBITDA climbed to $43.6 million from $23.5 million. Reported backlog reached $2.6 billion, up from $1.9 billion in the second quarter. The steel fabrication business was clearly at or near peak value when it was sold. The LTM adjusted EBITDA mark of $143.3 million at sale compared with $87.5 million for fiscal 2025.
Beneath that peak, the trajectory had begun to cool, and the call made the sequential slippage plain:
- **DBMG margins:** Gross margin fell to 15.3% from 18.5% in Q2, and adjusted EBITDA margin dropped to 8.9% from 11.8%.
- **DBMG EBITDA:** Adjusted EBITDA slipped from a record $48.7 million.
- **Backlog:** Adjusted backlog stalled at $2.7 billion after rising sharply in the first half.
- **Consolidated EBITDA:** Total adjusted EBITDA of $40.5 million doubled year over year but was down from $46.3 million in Q2.
The release attributed some industrial maintenance weakness to material-cost fluctuations. INNOVATE does not have to live with that deceleration, but it underscores that the sale captured a cyclical high.
The balance-sheet repair is real and substantial. The DBMG sale brought roughly $413 million in cash at closing, including a $35 million tax-election payment, plus 430,974 IES shares. Proceeds redeemed $325 million of senior secured notes and repaid the revolver. On the call, management said total principal debt fell to $238.3 million pro forma, from $583.3 million at quarter-end and $687.2 million at the end of 2025.
That is the central tension. INNOVATE has cut its debt load by roughly two-thirds by selling the business that produced nearly all of its revenue and EBITDA. What remains is small and loss-making:
- **R2:** Revenue fell to $1.2 million amid liquidity constraints, and demand eased to $3.1 million from $3.6 million. Its secured note matures December 31, 2026.
- **MediBeacon:** An equity stake whose losses rose in the quarter.
- **Broadcasting:** A 25% stake, now equity-method accounted and illiquid.
The company's own risk factors still flag substantial doubt about its ability to continue as a going concern. Standalone corporate cash was just $4.2 million.
Bulls are not without catalysts:
- **MediBeacon China:** 600 TGFR monitors ordered, with shipments planned from Q4 2026 through Q2 2027.
- **MediBeacon U.S.:** Engagement now spans more than 120 U.S. institutions, and Big Pharma clinical-trial use is anticipated in 2027.
- **Broadcasting:** The 287-station platform is positioned for a potential second spectrum auction, and INNOVATE holds an option to raise its stake to 40%.
- **R2:** Production at EIT is underway, and carry-forward backlog edged up to 116 systems.
These, however, are option-value catalysts, not cash-flow drivers. MediBeacon's adoption still hinges on reimbursement coding and 6-12 month conversion cycles. Further deleveraging depends on monetizing the IES stock after a lock-up of up to 60 days, exposing the company to IES share-price risk. No guidance was offered, and leadership remains interim.
Market context is thin. Shares opened at $11.04 after the August report. The 200-day moving average now sits at $8.91, well below that level, a reminder that the stock had been trading at an elevated level heading into the transaction closings. Investors now must price a fundamentally different, much smaller company.
The bottom line is that INNOVATE executed the portfolio surgery it needed. It sold DBMG near peak performance and slashed debt. But the normalized loss, the reliance on a one-time gain for GAAP profit, and the sequential cooling at DBMG show the headline overstates earnings quality. With the earnings engine gone, going-concern language intact, minimal corporate cash and $238.3 million of debt still outstanding, the investment case now rests on asset monetization and early-stage life sciences execution rather than operating earnings.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-05 | |
| Oct-05 | |
| Sep-18 | |
| Sep-02 | |
| Aug-18 | |
| Aug-10 | |
| Aug-07 | |
| Aug-06 | |
| Aug-03 | |
| Jul-08 | |
| Jun-01 | |
| May-15 | |
| May-14 |
