SKYX Matches On A Narrower Loss, But A Revenue Miss And An Undated Cash-Flow Target Overshadow The Deako Pipeline
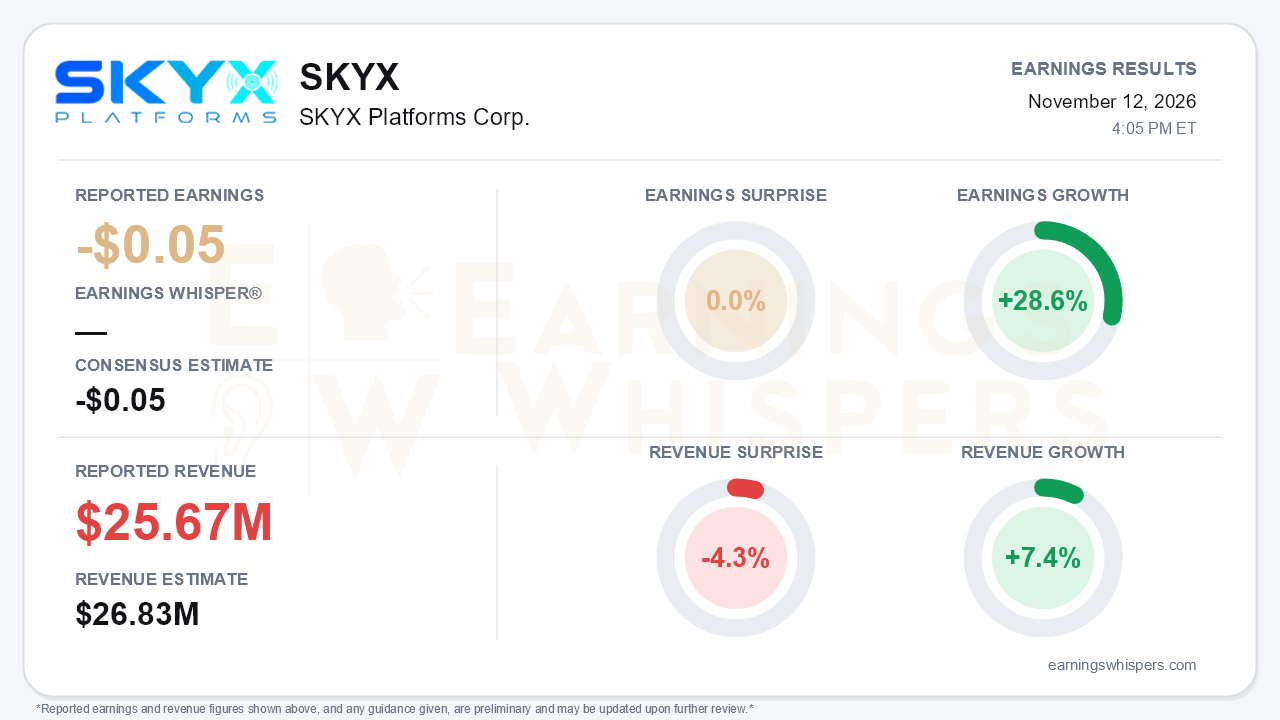
SKYX Platforms reported a third-quarter loss of $0.05 per share, exactly in line with consensus, on revenue of $25.67 million. Revenue missed the $26.83 million consensus by 4.3%. The loss narrowed enough to register 28.6% earnings growth year over year, and revenue rose 7.4%, the company's 11th straight quarter of year-over-year growth. The central tension is a widening gap between the story and the numbers. The completed Deako merger has given SKYX a much larger builder pipeline, but reported growth is still modest and the timeline for cash-flow breakeven has slipped again, this time with no date attached.
The quarter itself was better on margins than on sales. Gross profit reached a record $8.1 million, up 11% sequentially from $7.3 million. The release puts gross margin at 31.4% versus 28.9% in the second quarter, while the call analysis cites 31.7%. Either figure is a solid sequential recovery, but neither is a structural step-up. The call figure is roughly flat with the approximately 32% posted in the year-ago third quarter. Adjusted EBITDA loss, a non-GAAP measure, narrowed to $2.9 million from $3.5 million in Q2. Operating cash burn fell 15.5% year over year to $4.2 million. Cash, equivalents and restricted cash rose to $21 million from $10 million at year-end, and interest-bearing debt fell to $14.7 million from $18.3 million. Investors should note where that liquidity came from: the call analysis ties it to the roughly $29 million raise in the first quarter, not to internally generated cash.
The Deako merger, which closed October 13, dominated the call and the release. SKYX now cites a combined pipeline of about 4 million units at an expected average selling price near $50, compared with roughly 1 million units across announced projects at the end of fiscal 2025. Three builder programs totaling more than 210,000 units across more than 2,500 homes have been announced since closing:
- Maronda Homes
- Home Creations
- Stone Martin
Deliveries on those programs run through 2027. Management also highlighted a Trump Towers project in Hyderabad, initial builder shipments in Austin and Dallas, and expected merger cash savings of more than $6 million annually. The call analysis cites a $6-8 million synergy range. Management also floated up to five times more revenue per Deako home through upselling the full portfolio.
The quality of that pipeline deserves scrutiny. According to the call analysis, the near-term builder awards largely reflect pre-existing Deako backlog rather than new demand for SKYX's ceiling technology. Deako's revenue and margin profile has not yet been disclosed beyond 2025 revenue of more than $26 million. Management also acknowledged housing weakness and builder cost-cutting, which could pressure 2027 volumes. Retail has a similar gap between interest and orders. The turbo heater fan line expands from one model to five for the winter season, but big-box in-store orders remain unsigned. Meanwhile, the legacy e-commerce business still made up more than 90% of revenue as of late fiscal 2025, which helps explain why years of project announcements have produced only single-digit growth.
The most consequential change was a target that disappeared. Cash-flow positive was originally pegged for the second half of 2025 and later moved to the exit of 2026. Management now says only "as soon as possible." For a company issuing 25 million shares to fund a merger, the repeated slippage gives bears legitimate ammunition. The lock-up on those shares begins easing in 12 months, adding a future supply consideration.
The market had already priced in considerable skepticism before the report. Shares were $0.70 as of November 10, down 40.6% since the open after the August report. That leaves the stock about 47% below its $1.31 200-day moving average and 54% below its September high of $1.52. It sits just 3.3% above a 52-week low of $0.67 set November 5. Price and AVWAP trend readings remain negative, although the sequential growth trend is positive. Investor sentiment improved modestly, from 0.06 to 0.15, which suggests the merger narrative has some traction even as the shares have been sold.
The bottom line is that SKYX delivered an in-line quarter with better margins, less cash burn and a stronger balance sheet, and the Deako deal plausibly widens its route into builders. Against that, revenue fell short, the pipeline remains largely prospective and partly inherited, and the cash-flow-positive milestone is now undated. Until builder programs and Deako's contribution show up as faster reported growth, the stock's position near its lows reflects a credibility discount that this report did not resolve.
Read our earnings preview for SKYX Platforms Corp.: https://www.earningswhispers.com/article/SKYX/23086
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 5 hours | |
| Nov-10 | |
| Nov-10 | |
| Nov-09 | |
| Nov-04 | |
| Oct-26 | |
| Oct-22 | |
| Oct-21 | |
| Oct-14 | |
| Sep-30 | |
| Sep-10 | |
| Aug-13 | |
| Aug-12 | |
| Aug-10 |
