Shimmick's Profit Inflection Collides With A Third Revenue Cut And A Bookings Air Pocket
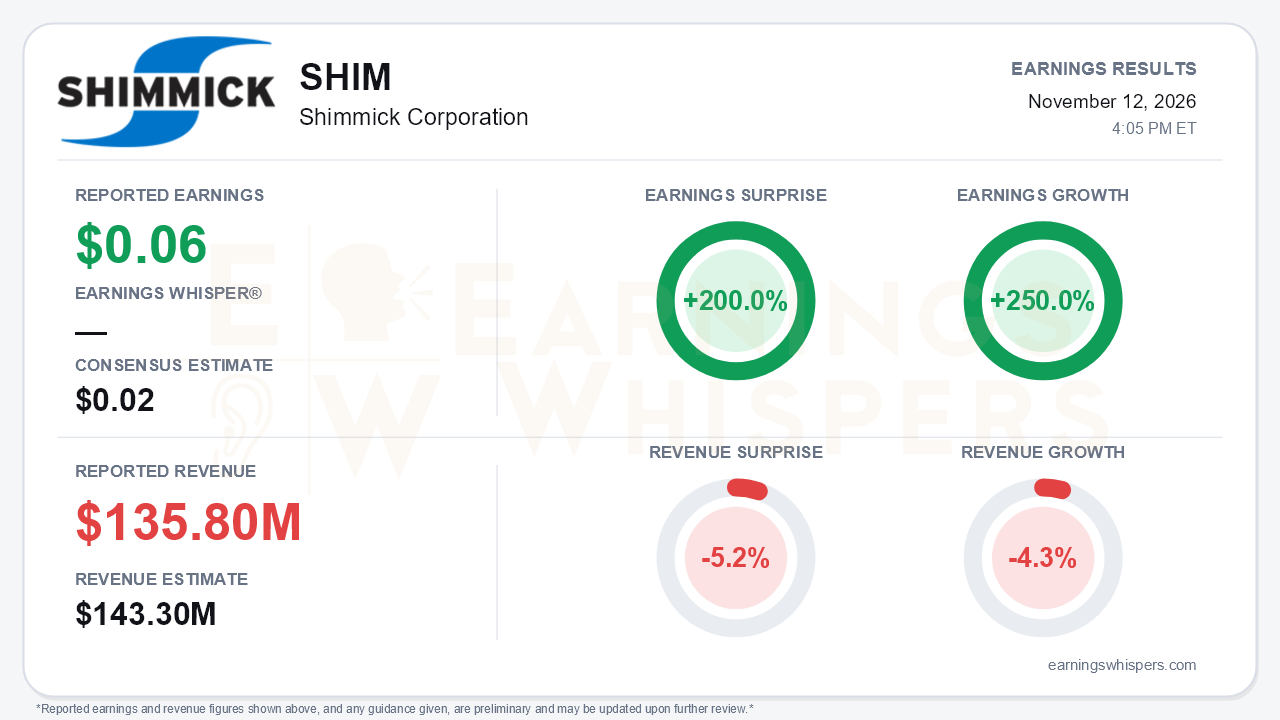
Shimmick Corporation delivered the quarter its turnaround thesis needed on profitability. It also delivered another reason to doubt the timing of its growth story. Earnings Whispers puts third-quarter earnings at $0.06 per share, a 200.0% beat against the $0.02 consensus and 250.0% growth from a year ago. Revenue of $135.8 million, however, missed the $143.3 million consensus by 5.2% and fell 4.3% year over year. Management also cut full-year revenue guidance for the third straight quarter. That is the central tension: margins, earnings and cash flow are improving, while the top line and new bookings keep disappointing.
The earnings figure needs context. The company reported GAAP diluted EPS of $0.02 and adjusted EPS of $0.08. Adjusted results exclude $1.5 million of Non-Core legal costs, stock compensation and transformation charges. The normalized figure falls between the two. Either way, Shimmick swung from a $(0.12) GAAP loss a year ago to its first positive net income since Q3 2023, at $848,000.
The drivers are genuine:
- **Gross margin:** Consolidated gross margin rose to $17 million (about 12.5%) from $11 million (roughly 8%).
- **Core projects:** Shimmick Projects revenue grew from $107 million to $136 million year over year, and its margin widened to 13% from 9% as newer awards ramped.
- **Costs:** SG&A was flat at $14.3 million.
- **Adjusted EBITDA:** It reached $8.9 million, up from $4 million in Q2 and $3 million in Q1.
The year-over-year revenue decline is almost entirely Non-Core runoff. That segment went from $35 million of revenue to slightly negative after the Tennessee lock project was terminated.
The call added evidence that the inflection extends to cash:
- Operating cash flow was about +$10 million in the quarter, the first positive quarter since Q4 2024.
- Working capital turned positive for the first time since the IPO.
- Management now expects positive operating cash flow in 2027.
- Liquidity rose to $53 million from $33 million.
The quality of that liquidity gain deserves scrutiny. Management acknowledged part of it reflects one-time receivable timing and project closeouts. Nine-month operating cash flow is still negative $14.7 million. The balance sheet also absorbed $18.3 million of equity proceeds this year, lifting the share count from 36.0 million to 42.8 million. Stockholders' deficit remains at $44 million. A refinancing at a rate about 320 basis points lower should cut future interest costs, though it temporarily raised Q3 interest expense.
Bears have legitimate ammunition on growth. Full-year revenue guidance fell to $500-$525 million. It was $525-$575 million last quarter and $550-$600 million in Q1, and the implied midpoint growth has shrunk from 17% to about 4%. That guidance also includes Shimmick's share of joint-venture work. Management attributes the cuts to Non-Core work with no margin impact. Even so, it again cited slower-than-expected contract execution and ramp timing.
Bookings were the more concerning signal. New awards were only $48 million, a 0.4x book-to-burn, compared with $138 million in Q2 and $289 million in Q1. Booked backlog fell to $907 million from $991 million.
The offset is the pipeline. Pending awards nearly doubled to $401 million from $221 million, and management expects most to convert within about 90 days. It said a good portion already has. Electrical work is targeted to rise from the high teens to 30%-plus of backlog in 2027, driven by data center and mission-critical projects. Non-Core work is now under 2% of backlog.
On EBITDA, the company raised the low end of guidance to $20 million but left the $22.5 million midpoint unchanged. That reduces downside risk rather than signaling upside.
The market had already priced in deep skepticism. Shares fell 45% from the $4.16 opening after the August report to $2.29 just before this release. That left the stock 38.8% below its 200-day moving average and only 5.5% above its October 22 inter-quarter low of $2.17. Investor sentiment swung sharply from a mildly positive 0.19 to a clearly negative -0.30. Investors entered the print expecting more slippage, not a profit inflection.
The Earnings Whispers trend signals reflect the same split. Sequential growth and momentum readings are positive, while price and AVWAP trends remain negative. Fundamentals are improving underneath a chart that has not stopped falling.
The bottom line is that Shimmick showed its core business can earn money and generate cash once legacy losses stop leaking into results. That was the profitability proof turnaround skeptics were not positioned for. But a third revenue cut, a 0.4x quarter of bookings, equity dilution and partly one-time liquidity gains mean the growth narrative still rests on management's promises. The next test is whether the $401 million of pending awards converts quickly enough to rebuild backlog and support revenue that matches the improving margins.
Read our earnings preview for Shimmick Corporation: https://www.earningswhispers.com/article/SHIM/22944
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-04 | |
| Oct-29 | |
| Oct-21 | |
| Aug-11 | |
| Aug-10 | |
| Aug-07 | |
| Jul-28 | |
| Jul-27 | |
| May-26 | |
| May-22 | |
| May-14 | |
| May-04 | |
| Apr-28 |
