Laird Superfood Posts A Paper-Thin EPS Beat, But A Revenue Miss And Halved EBITDA Outlook Expose A Stalled Roll-Up
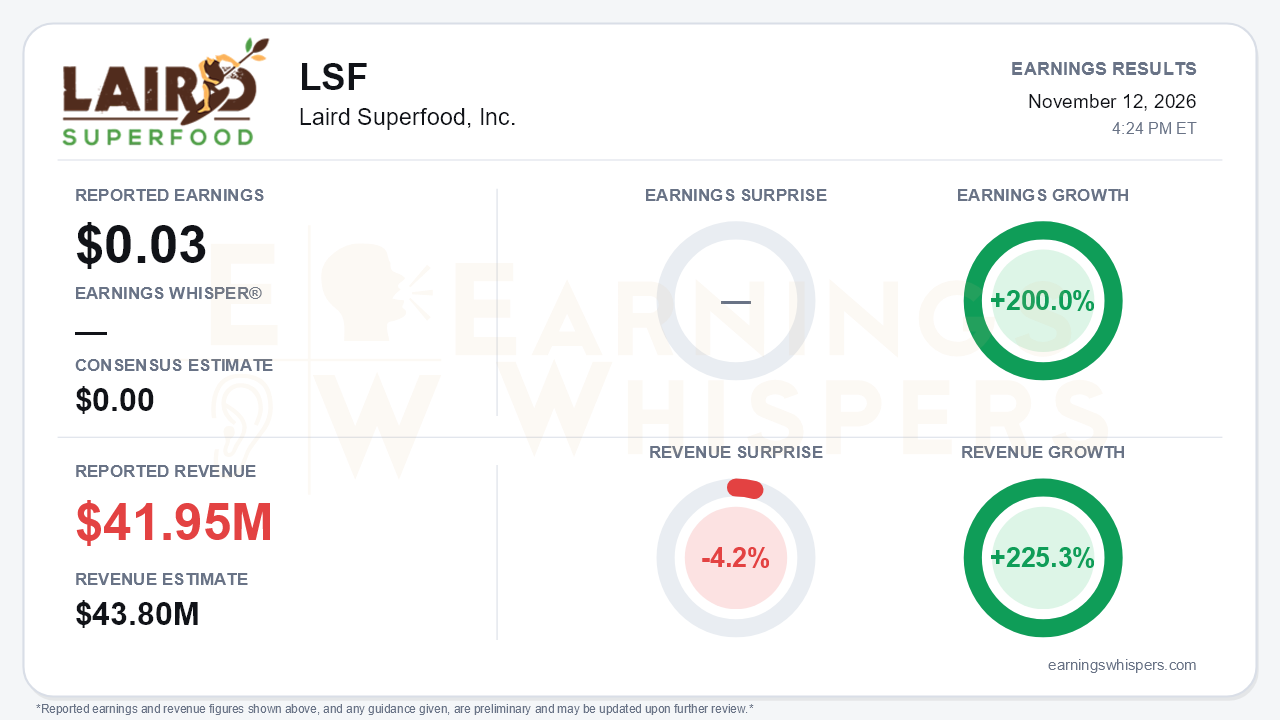
Laird Superfood reported third-quarter earnings of $0.03 per share against a consensus of $0.00, and earnings grew 200.0% from a $0.09 loss a year earlier. Revenue rose 225.3% to $41.95 million but missed the $43.8 million consensus by 4.2%. The more consequential news was guidance. The company cut its fiscal 2026 adjusted EBITDA outlook to $5-6 million from $8-12 million, and the call disclosed that the net sales range now stands at $135-140 million, down from $138-148 million. The headline EPS beat matters far less than the evidence that the Navitas and Terrasoul roll-up is producing scale without the expected profitability.
The quality of the beat deserves scrutiny. GAAP net income of $1.7 million depended on a $4.1 million non-cash gain from revaluing contingent acquisition consideration. Without that gain, the quarter's $2.3 million operating income would have been an operating loss. After preferred dividends on the $110 million Series A, net income attributable to common shareholders was only $0.3 million. Adjusted EBITDA of $2.1 million improved sharply from $0.2 million a year ago but fell from $3.0 million in the second quarter. Gross margin compressed to 29.6% from 36.5% a year earlier and slipped from 30.3% in Q2 and 33.3% in Q1. Management cited commodity inflation, fuel and freight, and Terrasoul's lower-margin model. The 225% growth figure is almost entirely acquired. Coffee solutions, the legacy Laird core, generated $11.6 million in gross sales, slightly below the $11.8 million a year earlier.
The call made clear that the trajectory has turned. Sequential revenue rose only 2%, from $41.3 million in Q2. E-commerce improved to $22.5 million from $20.0 million on Amazon strength, but wholesale fell to $19.4 million from $21.3 million. Management attributed the wholesale decline to lumpy club timing and lapping a prior-year coffee club deal, while direct-to-consumer stayed soft. Gross margin is now below the "low to mid 30s" back-half view given in Q1 and the "low 30s" view given in Q2. It is far from the high-30s exit rate floated a year ago. Cost-of-goods synergies are lagging because organic cacao, coffee, goji, chia and hemp costs have proved sticky. Retailers are also resisting price increases while adding freight surcharges. Management expects margin pressure to persist into the first half of 2027. Refrigerated liquid creamer, which was relaunched with fanfare last year, is now declining and under strategic review, with a possible exit within one to two quarters.
The release and the call frame guidance differently. The press release says the company "continues to expect" $135-140 million in sales and describes the outlook as "reaffirmed." The call analysis, however, shows that range is a cut from $138-148 million. That earlier range was reaffirmed in both Q1 and Q2, when the prior CFO said she would be disappointed by anything short of the mid-to-high end. Investors should treat this as a lowered outlook, not a reaffirmation. Simple subtraction from year-to-date results implies fourth-quarter sales of roughly $38-43 million and adjusted EBITDA of about $1-2 million. That implied EBITDA comes even as the company adds about $2 million of incremental marketing.
There is a credible growth story beneath the reset. Management cited consumption growth in the teens for Laird (excluding liquid creamer) and Navitas, and said Terrasoul is growing similarly. Walmart velocity across five SKUs in roughly 1,000 doors is rising weekly, and Target is expanding Navitas and Laird. New products include functional instant coffee, electrolyte coffee powders and coffee protein bars, and the company is leaning into powdered coffee and GLP-1-adjacent trends. G&A synergies are tracking ahead of plan. A new CFO from Tropicana and Danone/WhiteWave and a new supply-chain head from Danone add operating depth. Bears still have legitimate ammunition. Cash fell to $17.3 million from $23.2 million in Q2, operating cash flow was negative $10.0 million year-to-date, and M&A is paused for about six months while the complex Terrasoul ERP and network integration continues.
The market had largely anticipated trouble. Shares were trading at $2.50 before the report, down 48.7% from the $4.87 open after the August release and 25.3% below the 200-day moving average of $3.35. The stock hit a 52-week low of $1.50 on November 6 and bounced roughly 67% from that level into the print. Investor sentiment remained negative but improved, moving from -0.49 to -0.39. The Earnings Whispers price and AVWAP trend readings remain negative, while sequential growth reads positive.
The bottom line is that Laird delivered a cosmetic EPS beat on a non-cash gain while missing on revenue and roughly halving its EBITDA outlook. Durable recovery depends on whether commodity relief, synergies and retail distribution gains can restore margins by mid-2027 before the cash cushion thins further. A heavily discounted stock and slightly less negative sentiment suggest low expectations, but the burden of proof has shifted back to management.
Read our earnings preview for Laird Superfood, Inc.: https://www.earningswhispers.com/article/LSF/23024
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-08 | |
| Oct-29 | |
| Sep-04 | |
| Aug-17 | |
| Aug-13 | |
| Aug-12 | |
| Aug-03 | |
| Jul-29 | |
| Jul-14 | |
| Jun-25 | |
| Jun-17 | |
| May-18 | |
| May-14 |
