KinderCare Misses Again And Cuts Guidance A Third Time As Enrollment Slide Deepens, Though A Late-Quarter Inflection Gives Bulls A Narrow Opening
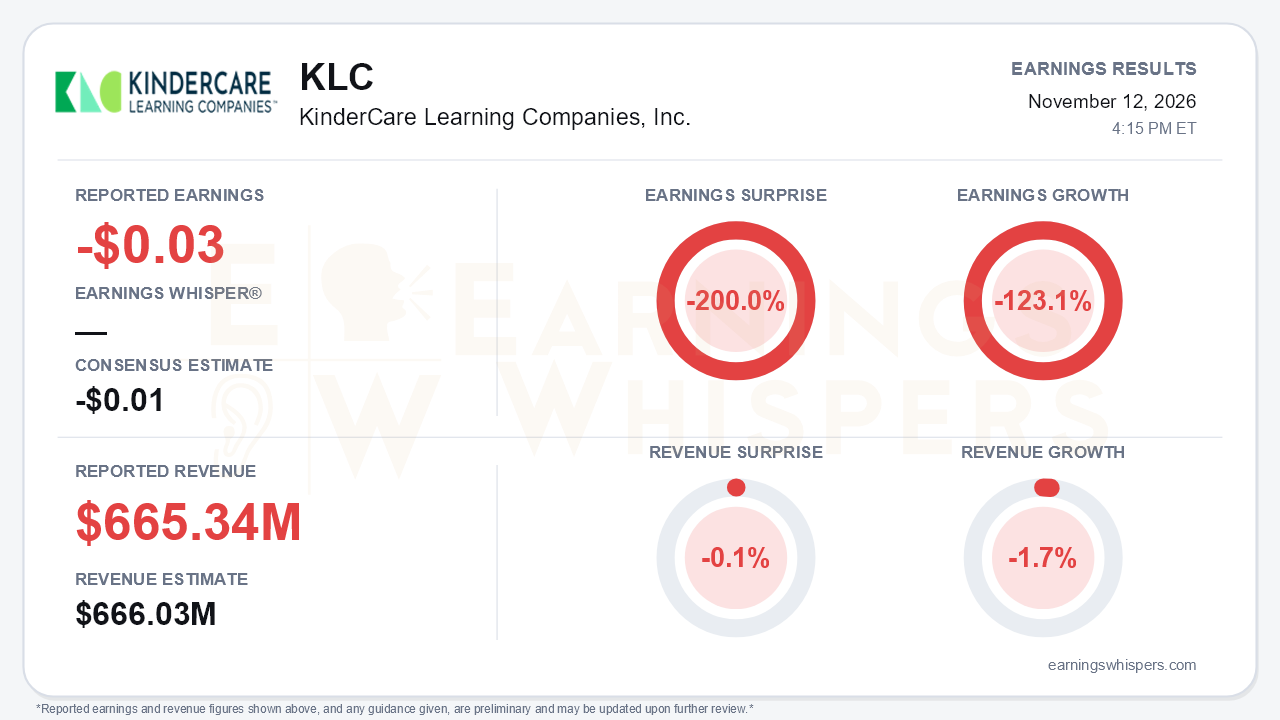
KinderCare Learning Companies (NYSE: KLC) reported an adjusted loss of $0.03 per share for the third quarter, missing the consensus estimate of a $0.01 loss by 200.0%. Revenue of $665.34 million was essentially in line, just 0.1% short of the $666.03 million consensus, but fell 1.7% year over year. Adjusted earnings fell 123.1% from a year ago, when the company earned $0.13 per share. The miss itself was small in dollars. What matters is that the quarter extended a pattern of deterioration. Revenue growth has slipped from modest growth in the first quarter to flat in the second and now to a decline. Management also cut full-year guidance for the third consecutive report.
The GAAP picture was far worse. KinderCare posted a net loss of $85.0 million, or $0.71 per share, compared with net income of $4.6 million a year ago. The swing came largely from $86.8 million of impairments. These included a $71.4 million goodwill charge that the company explicitly tied to the decline in its own market capitalization, which shows how the stock's collapse is feeding back into reported results. Even setting impairments aside, the operating trends were weak:
- Adjusted EBITDA fell 35.9% to $42.5 million, below the company's own $44 million to $48 million third-quarter guide.
- Cost of services rose to 82.9% of revenue from 80.2%, driven by higher rent, insurance, utilities, food and marketing.
- Roughly $3 million of severance was not added back to adjusted EBITDA.
- Early childhood center revenue fell 3.1%. Enrollment dropped 5.9%, only partly offset by a 2.8% tuition contribution. Center closures accounted for about 190 basis points of the enrollment decline.
The call made the enrollment problem impossible to dismiss as timing. Early childhood enrollment declines have widened every quarter this year, from roughly 3% in the first quarter to 4% in the second and about 6% in the third. Same-center occupancy fell to 63.8%, down 320 basis points year over year, even with a benefit of about 150 basis points from closing weaker centers. Management called back-to-school execution at the flagship KinderCare brand the biggest culprit. It installed a new brand leader and restructured field and corporate teams. Subsidy reimbursement rates came in below expectations across states, capping tuition contribution at roughly 2.5% to 2.8%. Household affordability pressure remains a headwind.
The guidance reset is the central development. Each line has now been cut repeatedly:
- Revenue: now $2.64 billion to $2.66 billion, down from $2.66 billion to $2.70 billion last quarter and $2.70 billion to $2.75 billion earlier in the year.
- Adjusted EBITDA: now $190 million to $195 million, compared with $200 million to $220 million last quarter and $215 million to $235 million as recently as the first quarter.
- Adjusted EPS: now $0.02 to $0.04, compared with an initial $0.15 to $0.25.
With $0.09 of adjusted EPS through nine months, the new range implies an adjusted loss in the fourth quarter. Free cash flow is now expected below $10 million, versus $35 million to $40 million earlier in the year. Leverage has climbed to about 3.5 times adjusted EBITDA from 2.6 times at year-end 2025. Lease termination costs of $8 million to $10 million, plus about $10 million of dead rent, will spill into 2027. Liquidity is adequate, with $143.4 million in cash and $187.7 million of revolver capacity. Still, the balance-sheet cushion is thinning while earnings power shrinks.
The bull case rests on a few genuine bright spots:
- **Enrollment inflection:** Since mid-September, new enrollments have run ahead of last year, narrowing the year-over-year enrollment gap from more than 5% to about 3%. Management cited retention near its highest level in Chief Executive Tom Wyatt's tenure.
- **Champions:** The before- and after-school business grew revenue 16.4% on a 17% gain in average weekly enrollment, its fifth straight double-digit quarter.
- **Employer channel:** KinderCare for Employers has a record eight on-site centers under contract.
- **Center optimization:** The closure program is nearly complete at about 85 centers, and the annualized EBITDA benefit was raised to roughly $10 million.
- **Interest costs:** Interest expense fell to $18.3 million from $24.1 million.
These are real positives. They are also small relative to the core centers business, which is still shrinking.
The market had already priced in considerable pain before the report. Shares were $2.14 entering the release, down 39.7% from the $3.55 open following the August report and 37.2% below the 200-day moving average of $3.41. The stock set a 52-week low of $1.63 on October 19 and had rebounded about 32% from that level into earnings. That bounce may have reflected hopes for exactly the enrollment improvement management described. Investor sentiment, already negative, weakened modestly from -0.354 to -0.411. The Earnings Whispers trend readings remain predominantly negative across price, momentum and AVWAP.
The bottom line is that KinderCare delivered another quarter of eroding enrollment, margin compression and a third guidance cut. The goodwill impairment is a reminder that the market's verdict is now showing up in the financial statements. The post-September enrollment improvement, Champions' momentum and the employer pipeline give management a credible story to rebuild around in 2027. Even so, the evidence of a turn spans only weeks. The leverage and lease-cost overhang mean investors will need several quarters of narrowing enrollment declines before the repeated resets lose their weight.
Read our earnings preview for KinderCare Learning Companies, Inc.: https://www.earningswhispers.com/article/KLC/22926
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-04 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Oct-29 | |
| Oct-27 | |
| Oct-27 | |
| Oct-22 | |
| Oct-22 | |
| Oct-21 | |
| Oct-19 | |
| Oct-05 | |
| Oct-02 |
