IZEA's Bookings Nearly Double And Q4 Outlook Points To Growth, But Revenue Is Still Shrinking And Gross Margin Has Cracked
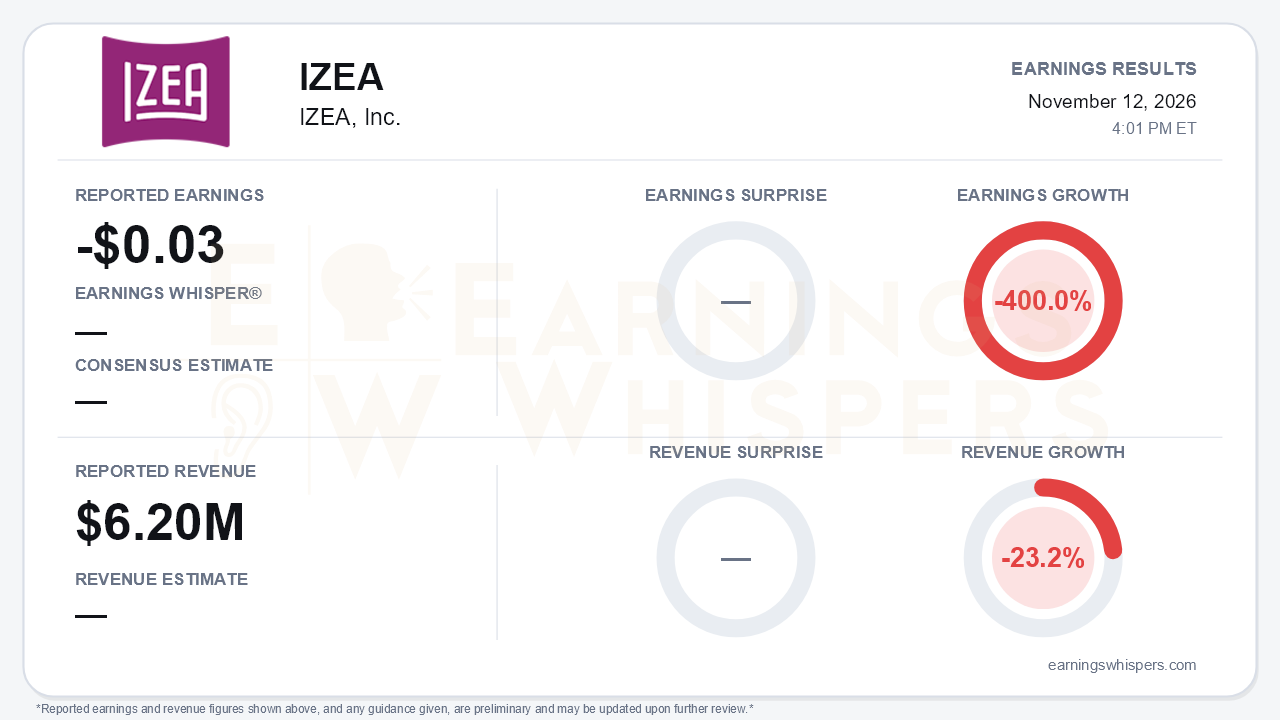
IZEA reported a third-quarter loss of $0.03 per share on revenue of $6.2 million, a swing from a $0.01 profit a year earlier. Earnings fell 400.0% year over year and revenue declined 23.2%. No consensus estimate was available, so the quarter cannot be scored as a beat or a miss. The backward-looking numbers were weak. The forward-looking numbers were the best the company has produced all year. Managed Services bookings jumped 94% to $7.0 million, up 54% from the second quarter, and management issued its first-ever quarterly revenue outlook: $7.5 million to $8.1 million for Q4, or 24% to 34% growth. That gap between a shrinking income statement and a sharply improving pipeline is the central tension of the report.
The quality of the quarter deserves scrutiny beyond the top line. Cost of revenue fell only 6% while revenue fell 23%, and the call put gross margin at 37%, down from 49% a year ago. The company attributed the compression to two factors:
- a lower-margin large enterprise customer;
- internal delivery labor that did not shrink with volume.
Management had described margins as relatively stable on the first- and second-quarter calls, so this is a genuine reversal rather than a continuation. Aggressive cost cutting partly masked the damage. Operating expenses excluding cost of revenue fell 26% to $3.1 million, with sales and marketing down 33% and G&A down 25%. Even so, the operating loss widened to $0.83 million from $0.33 million. Roughly $0.38 million of other income, largely the return on a cash-heavy balance sheet, kept the net loss to $0.4 million. Adjusted EBITDA was a loss of $0.2 million, versus a $0.4 million profit last year.
Sequentially, the picture improves. Adjusted EBITDA losses narrowed from $0.5 million in Q1 to $0.4 million in Q2 and $0.2 million in Q3. Operating expenses stepped down from $4.1 million to $3.3 million to $3.1 million over the same span.
The call framed Q3 as the first real inflection after three disappointing quarters, and the bookings data supports that reading. Q2 bookings were $4.5 million, down 19% year over year, so the move to $7.0 million is a sharp reversal. Q3 bookings also exceeded Q3 revenue, which sets up the Q4 outlook. Other operating developments:
- **Top accounts:** The three largest accounts grew 21% and posted their strongest combined quarter in company history, after a 'temporary slowdown' in Q1.
- **New wins:** Disney-ABC, HBO Max, Hulu and ASUS.
- **Platform:** All new campaigns now run through the ZED AI platform.
- **SMB exit:** The SMB run-off, which contributed $1.2 million in the prior-year quarter, is described as substantially complete. That should make comparisons cleaner from here.
- **Tone:** Management shifted from Q2's defensive macro explanations to 'strong momentum and confidence' in the Q4 range.
Bears have legitimate ammunition. Outside the top three, other established enterprise accounts declined, so the growth is narrowly sourced and customer concentration is rising. Concentration also appears to be part of the margin problem, since the large lower-margin customer is pulling gross margin down. Management conceded that Q4 growth will not offset the earlier shortfall. That effectively abandons the full-year return-to-growth goal set on the Q4 FY25 call. Investors should also note the limits of the outlook itself:
- It is explicitly a one-time disclosure, not a new guidance practice.
- It is built mainly on contracted bookings and expected campaign timing.
- The company's own definition says bookings are not necessarily predictive of quarterly revenue.
Even at the low end, Q4 revenue would need to rise more than 20% sequentially from Q3.
Capital allocation is the wild card. Cash stands at $46.4 million with no long-term debt, down from $50.9 million at year-end. The company has repurchased $2.6 million of stock under its $10 million authorization, including $0.8 million in Q3. Management described M&A activity as at an all-time high and said it has 'learned to go bigger,' citing potentially transformational deals. A large acquisition could accelerate the enterprise strategy. It would also introduce integration and valuation risk at a company still working to restore organic growth and gross margin.
Market context is thin for this report. No investor sentiment readings or current share price were available. For reference, shares opened at $3.19 after the August report, and the 200-day moving average stands at $3.35. Whether the stock has reclaimed that average will help show how much credit investors are extending to the bookings rebound before it appears in revenue.
The bottom line is that IZEA delivered its most encouraging demand signals of the year alongside deteriorating reported results. Bookings, top-account growth and a concrete Q4 revenue range give the turnaround story more credibility than it had after Q2. Falling revenue, a 12-point gross margin decline, rising concentration and a missed full-year growth goal keep the burden of proof on execution. Q4 is now a clear test: converting bookings into the promised revenue at a better margin matters more than any cost cut.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-10 | |
| Aug-12 | |
| Aug-11 | |
| Aug-04 | |
| May-13 | |
| May-12 | |
| May-05 | |
| Mar-31 | |
| Mar-17 | |
| Mar-17 | |
| Mar-10 | |
| Nov-13 | |
| Nov-12 |
