Co-Diagnostics Doubles Its Regulatory Pipeline As Cash Falls To $0.7 Million And India TB Timing Slips
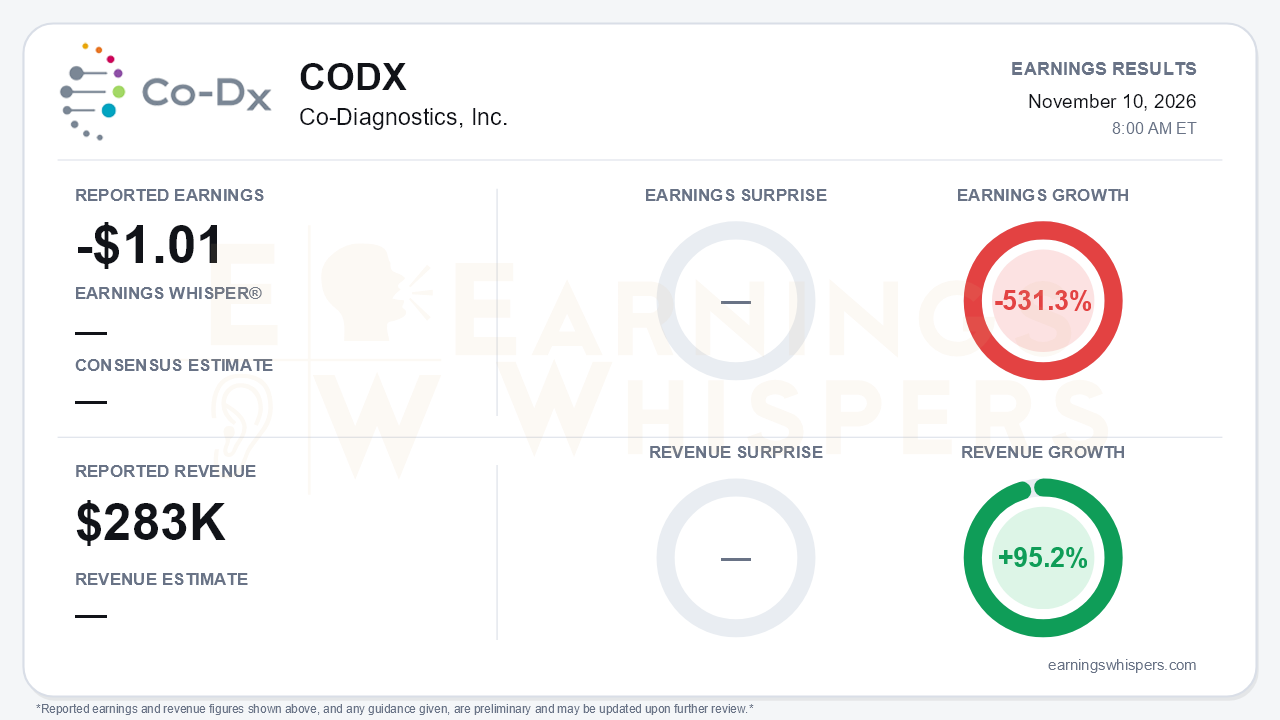
Co-Diagnostics (NASDAQ: CODX) reported a third-quarter loss of $1.01 per share on revenue of $0.28 million. On Earnings Whispers' normalized basis, earnings fell 531.3% year over year and revenue grew 95.2%. No consensus or Whisper estimate was available, so there is no surprise to measure.
The headline numbers matter less than the balance sheet. The company now has two regulatory submissions under review, one with the FDA and one in India. Cash and equivalents ended September at just $714,803, down from $11.9 million at the end of 2025. That is the central tension. The pipeline is closer to a commercial inflection than at any point this year, but the company has very little financial room to wait for one.
The quality of the quarter deserves scrutiny. The release's per-share loss of $1.01, compared with $4.66 a year ago, looks like improvement. It mostly reflects dilution: weighted shares rose to 6.27 million from 1.26 million, and shares outstanding climbed to 7.29 million from 2.10 million at year-end. In dollars, the net loss widened to $6.3 million from $5.9 million. Management attributed that increase to a $1.17 million income tax benefit in the prior-year period.
Operationally, there was real cost progress:
- Operating expenses fell 12% to $6.2 million, down from $9.2 million in Q1 and roughly flat with Q2's $6.3 million.
- R&D dropped to $3.6 million from $4.5 million, and stock-based compensation was halved.
- The adjusted EBITDA loss narrowed to $5.9 million from $6.3 million.
Revenue improved sequentially from $166K in Q2 and $146K in Q1, but it remains immaterial. Cost of revenue of $303K exceeded sales, leaving gross profit slightly negative.
The regulatory story did advance. CoSara completed its point-of-care TB study, reporting average sensitivity of 97.3% and specificity of 96.0% against MGIT culture. It then filed with India's CDSCO. That filing joins the August FDA 510(k) and CLIA waiver submission for the Flu A/B and RSV test, which drew on a 1,400-patient study. Smaller wins rounded out the quarter:
- A non-exclusive feasibility collaboration with ReadyGo on blood-based Ebola testing.
- A partly Gates-funded cloud and mobile infrastructure launch in India.
- The first international Vector Smart deployment, at a U.S. Air Force base.
- A post-quarter full-laboratory order from the Ute Indian Tribe, bringing Vector Smart to roughly 40 customers in 21 states.
Management also flagged Executive Order 14433 on tick- and mosquito-borne disease diagnostics as a potential funding opportunity for Vector Smart.
The call, however, weakened the story in important ways. India TB commercialization had been guided for "by Q3 26" and later "as early as end of Q3." Instead, the test was only just submitted, which is a clear slip. There was no update on several items emphasized on prior calls:
- The WHO ERPD submission promised for "later this year."
- The CoSara SPAC process.
- The CoMira Saudi technology transfer.
- The HPV program.
More telling, the call dropped CFO remarks and the Q&A session, and it did not address revenue, cash or the net loss. The tone shifted from earlier "next phase of growth" framing to brief, heavily caveated remarks. When a company with this liquidity profile narrows its disclosure, bears have legitimate ammunition.
The liquidity math is stark. Nine-month operating cash burn was $20.7 million, below last year's $22.9 million but still roughly $6–7 million a quarter. After quarter-end, Co-Dx closed a senior secured convertible financing with J.J. Astor. It provides about $2.1 million of initial funding, with up to $1.0 million more available subject to conditions. Combined with $0.7 million of cash, that covers only a fraction of a single quarter's burn at the current rate. The release's risk language explicitly cites the company's ability to continue as a going concern. Additional dilutive financing appears unavoidable unless a regulatory clearance unlocks revenue quickly, and secured convertible debt adds structural pressure on common holders.
The market had already been skeptical. Shares opened at $1.45 after the August report, well below the current 200-day moving average of $2.10. That indicates the stock entered this quarter in a longer-term downtrend. Earnings Whispers sentiment data and a current price reading were not available for this report.
The bottom line is that Co-Diagnostics delivered the regulatory filings it promised and kept cutting costs, but the quarter's most important number is the $0.7 million cash balance, not the per-share loss. Two pending submissions give the company credible catalysts. Still, India commercialization is running behind schedule, and a thinner call with no cash discussion leaves investors to weigh the pipeline against near-certain further dilution. Until a clearance converts into meaningful revenue, financing risk, rather than execution, is likely to define the stock.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-10 | |
| Nov-05 | |
| Nov-05 | |
| Oct-29 | |
| Oct-29 | |
| Oct-27 | |
| Oct-20 | |
| Oct-15 | |
| Oct-08 | |
| Oct-07 | |
| Sep-23 | |
| Sep-21 | |
| Sep-17 | |
| Sep-16 |
