Health In Tech Misses Badly And Slashes 2026 Revenue Outlook By A Third As A New CEO Trades Promises For Candor
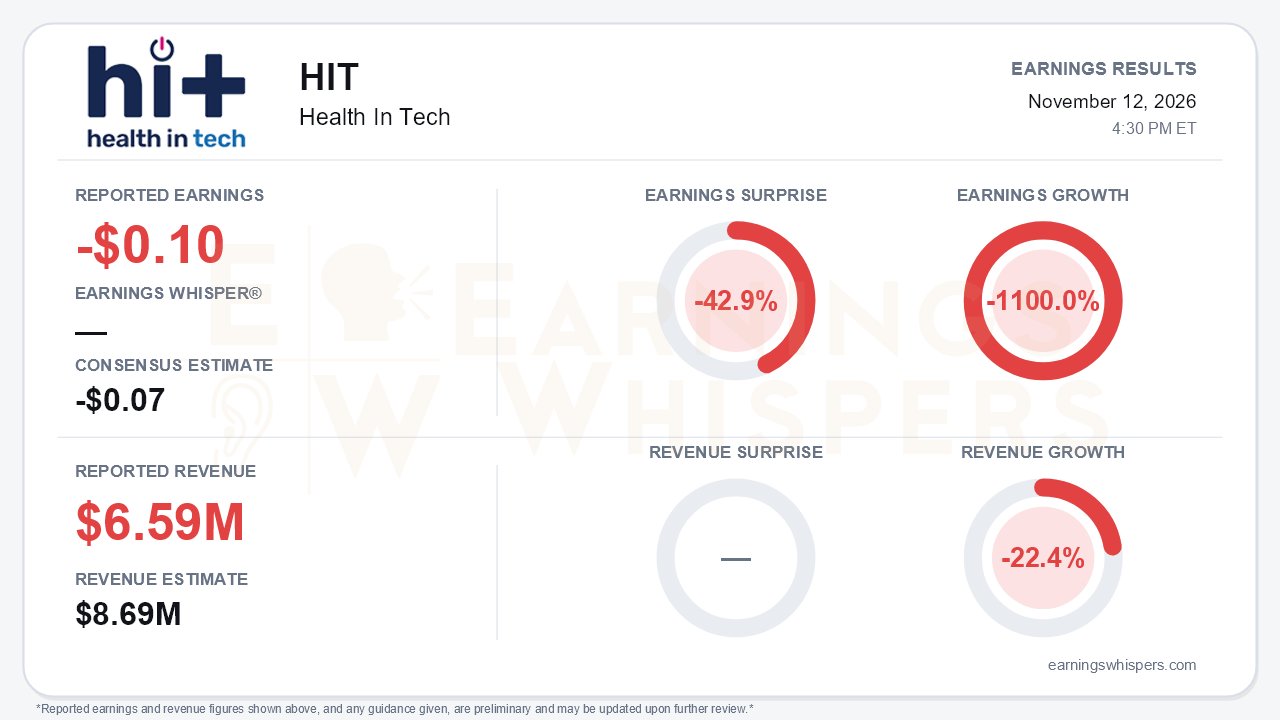
Health In Tech (NASDAQ: HIT) delivered a quarter that reset expectations sharply lower. The company reported a loss of $0.10 per share, missing the -$0.07 consensus by 42.9%. Revenue of $6.59 million missed the $8.69 million consensus by 24.2% and fell 22.4% from a year ago. Earnings declined 1100.0% year over year, swinging from a $0.01 profit to a loss. The GAAP net loss was $7.1 million, or $(0.11) per diluted share. The bigger story is guidance. Full-year 2026 revenue is now expected at roughly $30 million, down from the $45 million to $50 million range management had reaffirmed on each of the prior three calls. That is the central development: a growth narrative that leaned on pipeline metrics has collided with what actually converts into revenue.
The quality of the quarter deteriorated on almost every line. Revenue has now declined for three straight quarters, from $8.8 million in Q1 to $8.1 million in Q2 to $6.6 million in Q3. Underwriting modeling (ICE) revenue fell to $0.63 million from $1.39 million a year earlier, and fee revenue also declined. Gross profit dropped to $3.1 million from $5.1 million, putting Q3 gross margin at about 46.5% and the nine-month figure at 49.1% versus 65.1% last year. Spending moved the other way. Sales and marketing more than doubled to $2.1 million, and R&D roughly quadrupled to $0.9 million. The $5.3 million credit-loss provision covered:
- surplus administration receivables;
- carrier-transition receivables;
- a written-off overseas loan.
Adjusted EBITDA excludes only part of that charge, yet it still came in at -$3.9 million, versus -$1.3 million in Q2 and a $1.0 million profit a year ago.
The call explained what broke, though it did not inspire confidence that the fix is near. Management blamed the guidance cut on delayed policy commencement during a transition to a new carrier. It framed the revenue as shifted into 2027 rather than lost. Even so, several commitments slipped:
- The A-rated carrier that was supposedly about 30 days away on the Q2 call is still unsigned, with no timeline.
- The HitRix marketplace moved from a second-half 2026 launch to a Q1 2027 MVP, which pushes any revenue contribution to Q2 2027 at the earliest.
- The capital-markets leg of the Three-Year Rate Stabilization Program may slip past year-end.
The tone shifted markedly. New CEO Sanjay Shrestha, effective October 20, acknowledged that reported results have not reflected the platform's potential and said initiatives took longer than expected. That is a clear break from the prior quarter's promotional 'not a demand problem' framing. No 2027 guidance was offered; strategic priorities are deferred to the Q4 report.
The headline operating metrics did improve, which is where bulls will point. Pipeline revenue jumped to $156.4 million as of October 30 from $66.3 million at July 31. Platform Placed Plan Value rose to $91.8 million, and distribution partners grew 15.9% year over year to 984. But the assumed pipeline conversion rate was cut to 3% to 7% from 15% to 40%. A pipeline more than twice as large therefore implies far less near-term revenue than the old, smaller one did at the old assumptions. Cash also rose to $10.1 million from $6.5 million. That increase came from $6.65 million of convertible notes, not from the business. Operating cash burn did narrow to $1.0 million, but a $3.5 million receivables collection flattered the figure. The release itself flags the company's ability to regain Nasdaq listing compliance as a risk. Together with convertible notes and a SEPA facility, that points to continued dilution pressure.
The market had largely anticipated trouble. Shares opened at $1.00 after the August report and stood at $0.56 heading into this release, a 44.1% decline. The stock was roughly 50% below its $1.12 200-day moving average and just 13.7% above the $0.49 52-week low set on November 5. Investor sentiment swung from essentially neutral (0.02) to decidedly negative (-0.56), one of the more substantial shifts the scale allows. Earnings Whispers price, momentum and AVWAP trend readings are all negative. Expectations were already depressed, but the guidance cut and loosened conversion assumptions give bears legitimate ammunition that the pre-report sell-off was justified rather than overdone.
The bottom line is that Health In Tech's quarter replaced an aggressive outlook with a much more sober one. Revenue, margins, earnings and guidance all moved the wrong way. Growing pipeline and partner metrics offer a thread of optimism, but management itself has sharply discounted how much of that activity becomes revenue. The new CEO's candor is an improvement in credibility, not in fundamentals. Until the company signs its A-rated carrier, launches HitRix and shows conversion in reported revenue, the 2027 recovery story remains an assertion rather than evidence.
Read our earnings preview for Health In Tech: https://www.earningswhispers.com/article/HIT/23019
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 4 hours | |
| Nov-07 | |
| Oct-29 | |
| Oct-20 | |
| Oct-16 | |
| Oct-08 | |
| Oct-08 | |
| Oct-02 | |
| Sep-30 | |
| Sep-09 | |
| Aug-14 | |
| Aug-13 | |
| Aug-12 | |
| Aug-03 |
