Cerebras Swings To A Core Profit And Raises Guidance Again, But OpenAI Delays And A 54% Drawdown Set Up A Credibility Test
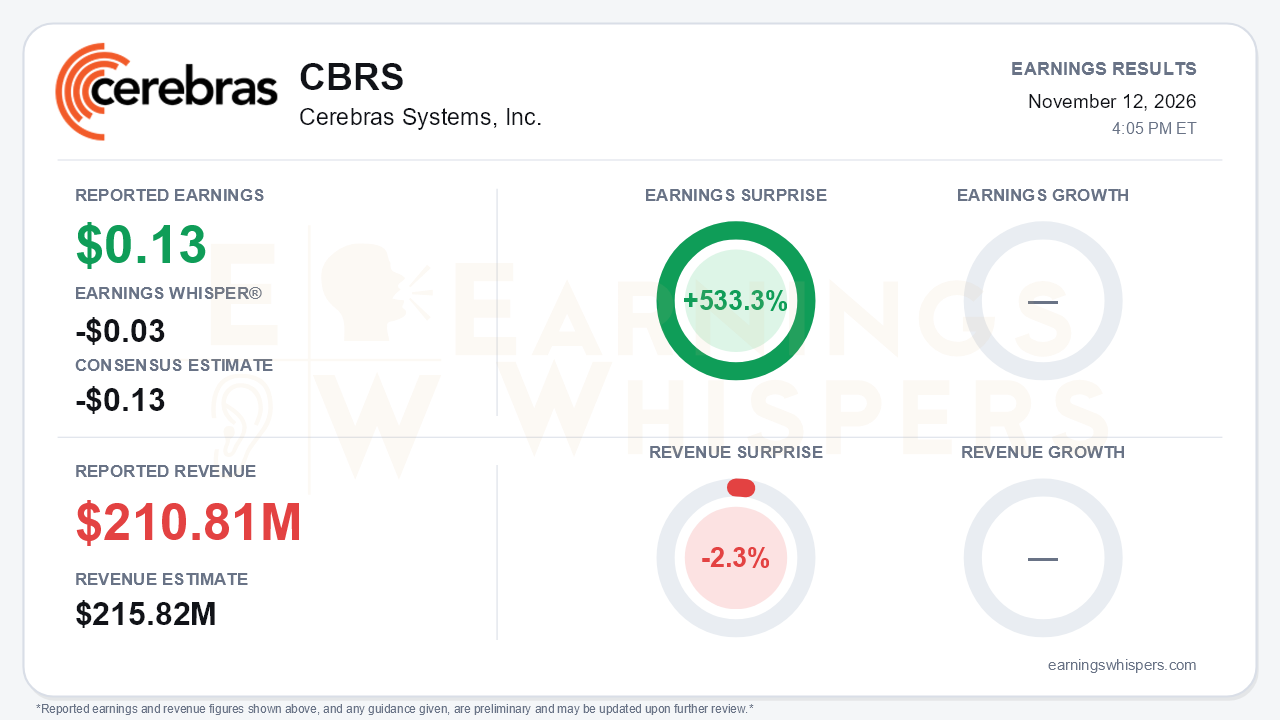
Cerebras Systems delivered the kind of quarter growth investors usually reward. It reported earnings of $0.13 per share against a consensus estimate of -$0.13 and an Earnings Whisper of -$0.03, a 533.3% surprise. It also posted its first positive core net income, $29.8 million, ahead of management's prior expectations. Even so, the stock entered the report down 54.1% since the open after its August release, with investor sentiment deteriorating. That is the central tension. The operating trajectory improved on nearly every axis, while the company's largest contract slipped and the market lost confidence.
The quality of the beat deserves scrutiny because the GAAP and core views diverge sharply.
- **Per-share results:** The $0.13 profit reflects core results. On a GAAP basis, Cerebras lost $161.2 million, or $0.67 per share, as stock-based compensation reached $155.1 million.
- **Revenue:** GAAP revenue of $210.81 million missed the $215.82 million consensus by 2.3%. The gap from core revenue comes mostly from $36.4 million of customer-warrant amortization, which is booked as contra-revenue. Core revenue was a record $230.9 million, up 70% year over year, and beat the $214–216 million guidance management set in August by roughly $16 million.
- **Gross margin:** The warrant drag hit hardware especially hard. GAAP hardware gross margin was just 11%, and total GAAP gross margin fell to 20% from 40.6% a year ago. Core gross margin of 41% beat the 38–40% guide.
- **Operating margin:** Core operating margin of -14.3% came in about ten points better than guidance.
Investors should be clear about which scorecard they are using. The core numbers are strong, but the GAAP loss widened materially.
The call preserved a credible growth story. The mix shift toward cloud is real: core cloud revenue reached $144.9 million, up 272% year over year and 13% sequentially. Core cloud gross margin improved 510 basis points to 46.9%.
Management raised full-year guidance for the second consecutive quarter:
- **Core revenue:** $940–960 million, up from $880–890 million.
- **Core operating margin:** -10% to -8%, compared with -19% to -17% previously.
The fourth-quarter outlook is the steepest step-up yet. Core revenue is guided to $310–330 million, roughly 40% sequential growth, with gross margin of 47–49% and operating margin around break-even. Management also said the gross-margin trough came in the second quarter rather than the third and reiterated that it expects revenue to more than triple in 2027.
The customer and product developments were equally substantive:
- **Hyperscalers:** Oracle will offer Cerebras inference on OCI in 2027. A new top-three hyperscaler deal, which the call identified as Microsoft, gives Cerebras three hyperscaler wins in six months alongside AWS.
- **Capacity and pipeline:** Contracted data center capacity rose to about 700 megawatts from more than 600. The inference pipeline grew more than tenfold.
- **Products:** The WSE-5 processor reached system testing quickly, pulling CS-5 production forward to early summer 2027 from the second half.
Bears still have legitimate ammunition, and much of it centers on OpenAI.
- **OpenAI delays:** The OpenAI contract represented the majority of roughly $25 billion in remaining performance obligations cited last quarter. It is behind schedule on initial tranches because of land, power and shell delays. Estimated delay credits were deducted from RPO, now $26.1 billion. Fewer than 5% of committed megawatts could become cancellable this year, and catch-up is not projected until the second half of 2027.
- **Cloud capacity:** The same constraints leave fourth-quarter cloud revenue guided roughly flat sequentially. The 40% revenue jump therefore leans heavily on higher-priced hardware shipments.
- **Hardware margin:** Core hardware gross margin slid to 31% from 38.8% in the second quarter on final legacy low-price contracts.
- **Rented capacity:** Margin drag from rented-back capacity now extends through at least mid-2027.
- **Cash and spending:** Cash and investments fell to $7.8 billion from $8.6 billion. Nine-month operating cash burn was $389 million, and capital spending exceeded $1 billion.
- **Geography:** More than 75% of 2027 capacity sits outside the U.S.
- **Tone:** Management spent noticeable time rebutting concerns about the OpenAI relationship, model-size support and yields, a defensive posture absent from earlier calls.
The market setup is more complicated than the surprise implies. Investor sentiment fell from roughly neutral (-0.02) to clearly negative (-0.24), a meaningful shift in expectations. The stock tells the same story:
- It peaked at $261.08 on August 17, just after the last report.
- It collapsed to a 52-week low of $77.84 on November 5, days before the IPO lockup fully expired on November 9.
- At $101.08 before the release, it had rebounded about 30% off that low but remained 61% below the quarter's high and 47% below its 200-day moving average.
The trend readings are mixed, with momentum positive but AVWAP still negative, consistent with a stock bouncing inside a broken chart.
The bottom line is that Cerebras delivered a fundamentally stronger quarter than its share price suggests. It beat its own targets for a third straight quarter, reached a core profit early, raised guidance again and diversified its customer base beyond OpenAI. Skeptics were not positioned for that. However, the near-term story now depends on converting hardware orders and delayed data center capacity into revenue on schedule. The widening gap between GAAP losses and core profits will keep the quality of earnings under scrutiny. Execution on the OpenAI tranches and the December capacity additions will likely matter more than this quarter's beat.
Read our earnings preview for Cerebras Systems, Inc.: https://www.earningswhispers.com/article/CBRS/22911
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-11 | |
| Nov-11 | |
| Nov-10 | |
| Nov-10 | |
| Nov-09 |
