AVAX One (AVX) Swings To A $6.11 Profit On An AVAX Mark-Up, But Shrinking Revenue And Cash Show The Real Story
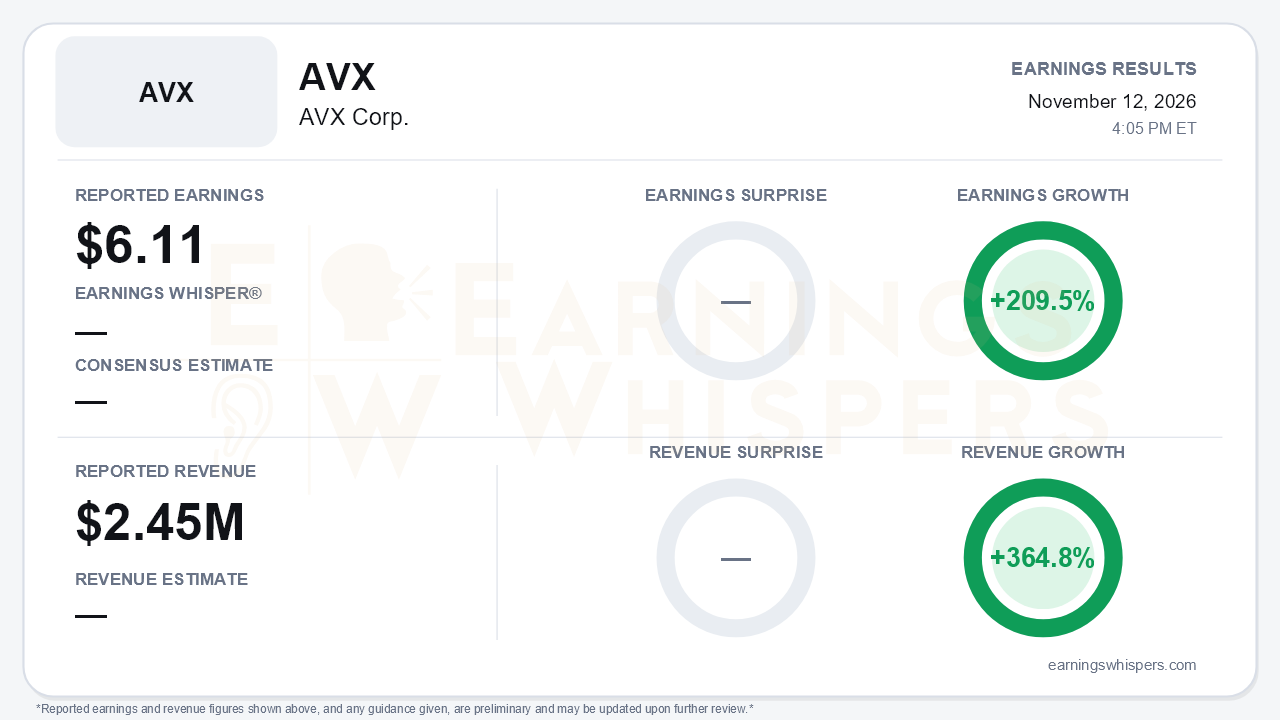
AVAX One Technology (NASDAQ: AVX) reported third-quarter earnings of $6.11 per share on revenue of $2.45 million. Earnings grew 209.5% year over year and revenue grew 364.8%, a swing from a $(66.81) per-share loss a year ago. No consensus estimate or Earnings Whisper was available, so there is no surprise to measure. The more useful comparison is with the company's own recent quarters, and on that basis the headline overstates the improvement. The $49.9 million of net income rests almost entirely on a $55.1 million unrealized gain from marking the AVAX treasury to market. The operating business went backward. That is the central tension: a GAAP profit produced by token prices sitting on top of declining revenue, rising costs and a shrinking cash balance.
The quality of the quarter deserves scrutiny. The year-over-year growth figures mostly reflect the company's pivot to an Avalanche treasury in late 2025, not underlying momentum. Sequentially, the picture is weaker:
- Revenue fell to $2.4 million from $2.8 million in Q2 and $2.5 million in Q1.
- Staking revenue slipped to $1.8 million from $2.1 million, while Bitcoin mining was flat at $0.7 million.
- Adjusted operating expenses, which exclude the digital-asset marks, rose to roughly $4.7 million from $3.2 million. That is nearly double quarterly revenue.
The year-to-date figures show how volatile the reported numbers are. Nine-month results remain a $31.6 million net loss, including $10.9 million of unrealized losses, $5.8 million of realized losses and a $3.7 million staking-token impairment. The release's nine-month per-share line also shows a positive $3.91 alongside that loss. That inconsistency is worth noting at a company whose finance leadership is still in transition.
The balance-sheet work is real, and it is the quarter's strongest element:
- Management retired $14.9 million of convertible debt in Q3, about half repaid in cash and half converted to shares, then cleared the remaining roughly $970,000 after quarter end. Convertible debt is now zero.
- Buybacks resumed. The release cites 384,224 shares repurchased in Q3, while the call referenced 333,500 shares at $5.36 in September. Another 710,000 shares were bought in October at $5.46, and $30.4 million remains authorized.
- Shareholders' equity of $165.3 million against roughly 9.7 million shares outstanding works out to about $17 per share. That gap explains why management calls the repurchase prices attractive.
The trade-off is liquidity. Cash fell to $8.5 million from $11.4 million in Q2, $16.5 million in Q1 and $22.1 million at year-end. That trajectory contradicts earlier claims of roughly three years of runway. The October buyback alone cost roughly $3.9 million, close to half of quarter-end cash. Conversions also pushed shares outstanding to 9.7 million from 7.7 million at year-end.
The call narrowed the story rather than broadening it. Management abandoned the AI/HPC data-center initiative, including the BlueFlare Alberta project. As recently as Q1 that project was framed as a 10MW site with a tenant by early 2027, and it was called "on track" in Q2. Simplifying to a pure AVAX treasury has logic, but it removes the only diversification away from token prices. Operating metrics inside the treasury did improve modestly:
- Holdings rose to about 14.17 million AVAX and equivalents from about 13.9 million.
- Roughly 99.7% of holdings are staked.
- The annualized yield rose to about 5.85% from about 5.3%.
- A laddered staking structure is meant to smooth reward timing.
The external catalysts are notable. The NYSE selected Avalanche for clearing and settlement on its planned tokenized-securities platform, targeting a Q4 launch subject to regulatory approval. Progmat migrated about $2.7 billion of digital securities to the network, and Aave v4 launched with a planned institutional real-world-asset lending market. These developments strengthen the case for Avalanche itself. They reach AVX shareholders mainly through the AVAX price, not through operating revenue.
Guidance creates a further conflict. The release reiterated full-year 2026 revenue of $11 million to $12 million and EBITDA of $2 million to $3 million, assuming spot prices of $9 AVAX and $70,000 Bitcoin. Two problems stand out:
- Revenue: nine-month revenue of $7.8 million implies Q4 revenue of roughly $3.2 million to $4.2 million. That would be a sharp step up from a declining $2.4 million run rate.
- EBITDA: the release did not explain how the EBITDA range reconciles with a $25.5 million year-to-date operating loss. On the call, management also did not repeat its earlier expectation of positive 2026 EBITDA.
Governance adds to the uncertainty. Leadership remains interim, the CFO did not present, and no analyst questions were taken.
No investor-sentiment reading or current price was available for this report. Price context is limited but telling. Shares opened at $3.25 after the August report. The September and October repurchase prices of $5.36 to $5.46 indicate the stock traded well above that level and above its $2.58 200-day moving average during the quarter. The market has been rewarding the debt cleanup and Avalanche headlines more than the operating trend.
The bottom line is that AVAX One delivered a cleaner capital structure and a higher staking yield, but its reported profit is a token-price event, not an operating one. Revenue is falling, adjusted costs are rising, cash is draining, the growth pillar is gone and leadership is interim. Investors are left with a leveraged bet on AVAX run by a company that must now prove it can fund itself without its cash pile, while Q4 guidance requires an operating rebound the third quarter did not show.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-10 | |
| Nov-10 | |
| Oct-30 | |
| Oct-07 | |
| Oct-01 | |
| Sep-02 | |
| Aug-19 | |
| Aug-14 | |
| Aug-13 | |
| Aug-05 | |
| Jul-30 | |
| Jul-09 | |
| Jul-09 |
