Energous Misses Revenue Consensus As Margin Repair Arrives Without The Execution Upgrade Q2 Promised
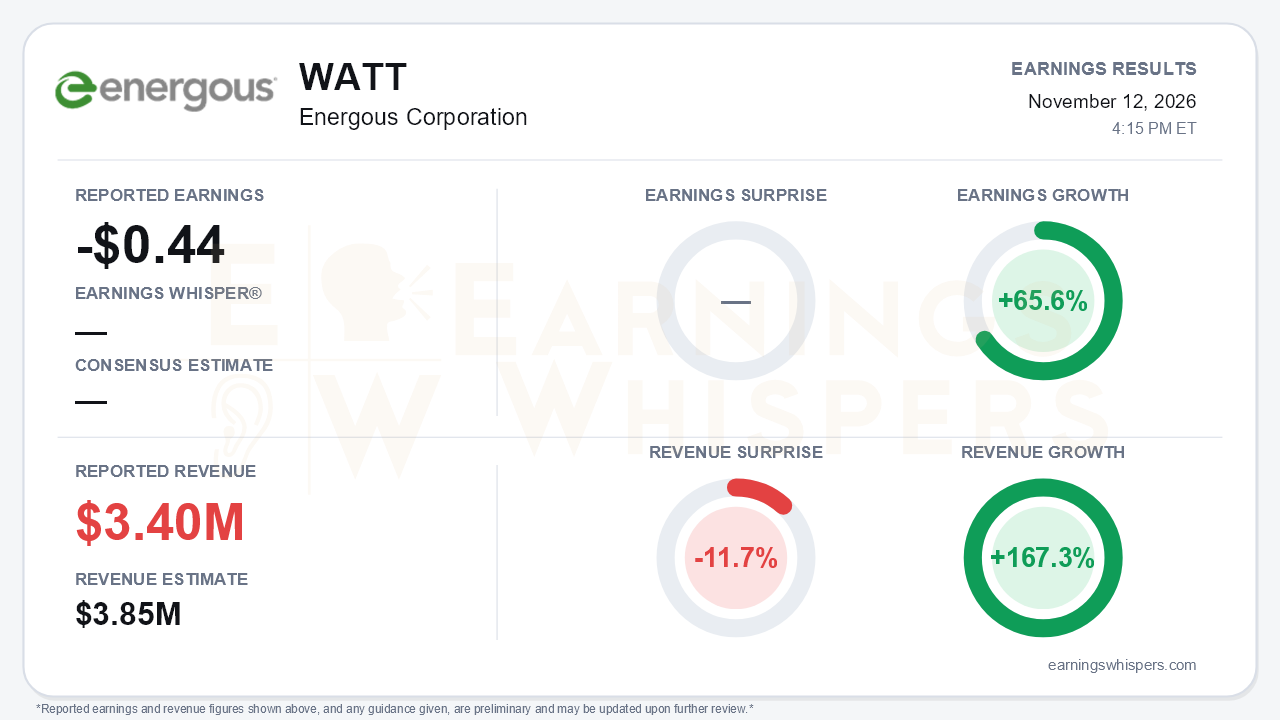
Energous Corporation (NASDAQ: WATT) reported a loss of $0.44 per share on revenue of $3.4 million for the third quarter. Revenue rose 167.3% year over year but missed the $3.85 million consensus by 11.7%. Earnings improved 65.6% year over year on a per-share basis. The release lists the GAAP loss at $0.45 per share, slightly different from the normalized figure. Neither figure supports a clean beat narrative: a younger hardware business that has been promising an inflection came in well short of revenue expectations. The quarter delivered partial repair rather than the step-change the second-quarter call had framed.
The quality of the earnings improvement deserves scrutiny. The per-share gain is largely arithmetic. Weighted shares rose to roughly 5.5 million from 1.6 million a year earlier, and additional paid-in capital has climbed by about $32 million since December. In dollar terms, the GAAP net loss widened to $2.5 million from $2.1 million, and the non-GAAP loss edged up to $2.1 million from $2.0 million. Operating expenses rose to $3.2 million from $2.6 million, including a jump in stock-based compensation to $308,000 from $40,000.
The growth picture is also less uniform than the triple-digit headline suggests. Third-quarter revenue growth of 167% trails the 270% pace for the nine-month period, so year-over-year growth is decelerating as comparisons toughen. Sequential growth of 10% did improve on a roughly flat second quarter, when revenue held near the first quarter's $3.1 million.
Margins are the clearest improvement. Gross margin recovered to 14% from a 3% trough in the second quarter, helped by a July price increase. Gross profit was essentially flat year over year at $479,000 on more than double the revenue, however, and margin remains far below the first quarter's 36%. Management now expects a return to the mid-30% range in the first half of 2027, a timeline that has effectively been pushed out, while it reaffirmed a 40%-plus long-term target. The production story explains much of this. The overseas contract manufacturer produced no volume in the third quarter, despite the prior plan for limited output. Management says both the overseas and U.S. manufacturers are producing at volume in the fourth quarter, and it expects sequential revenue growth to accelerate.
The call preserved a credible pipeline story but trimmed some of the specifics that had made the second-quarter narrative exciting. Positive developments include:
- The first end-to-end proof of concept, with a semi-perishable consumer products manufacturer, is expected to move to deployment in the first quarter of 2027, generating recurring e-Compass SaaS revenue.
- A warehouse club rollout to about 550 locations is slated to begin in early 2027.
- A Fortune 10 retailer is adding Superstore use cases for 2027, at 125-plus bridges per supercenter.
- AWS-reported customer launches doubled to 100-plus.
- A Fortune 10 healthcare retailer is re-engaging directly.
Bears have legitimate ammunition, however:
- The largest Fortune 10 retail customer's 2027 demand was guided only to roughly 2026 levels.
- The quick-service restaurant program cooled from rollout talk to continued evaluation.
- The federal agency opportunity of up to 500 sites went unmentioned.
- Promised reseller announcements and PowerBridge Pro+ contribution were not addressed.
- Energous still has only two active paying deployment customers, which management hopes to double to four in 2027.
The tone was more measured than the second quarter's, and the Q&A consisted of a single question.
The balance sheet provides runway but warrants monitoring. Cash fell to $28.8 million from $31.2 million in the second quarter and about $37 million in the first. The third-quarter decline was more modest after the second quarter's heavy manufacturer prepayments. Inventory has tripled since December to $4.6 million, consistent with the production ramp.
The market had already priced in considerable disappointment before the report. Shares closed at $8.99 on the eve of earnings, down 47.1% from the $17.01 open after the August report and about 45% below the 200-day moving average. The stock peaked at $20.00 on the first day after that report and subsequently bottomed at $6.77 on November 5. It entered this report about 33% off that low, a partial rebound within a deeply damaged chart. Price and AVWAP trend signals remain negative, while the sequential growth reading is positive, matching the improving quarter-to-quarter revenue and margin data. Investor sentiment improved meaningfully, rising from -0.32 to roughly neutral at +0.03. That shift suggests expectations have reset rather than turned optimistic.
The bottom line is that Energous delivered genuine sequential progress in revenue and gross margin, but the quarter missed revenue consensus, the per-share improvement owes more to dilution than to a narrower loss, and several second-quarter growth vectors either slipped or disappeared. The investment case now rests on 2027 execution: dual-manufacturer volume, a return to mid-30% margins, conversion of the first end-to-end deployment, and broader customer diversification. Until those arrive, the stock's steep drawdown reflects a show-me setup that this report did not resolve.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Sep-15 | |
| Aug-13 | |
| Aug-12 | |
| Aug-12 | |
| Jul-29 | |
| Jun-29 | |
| May-14 | |
| May-13 | |
| May-13 | |
| May-06 | |
| Apr-29 | |
| Apr-15 |
