InspireMD Beats On A Narrower Loss, But TCAR Approval Arrives As Cash Thins And Margins Collapse
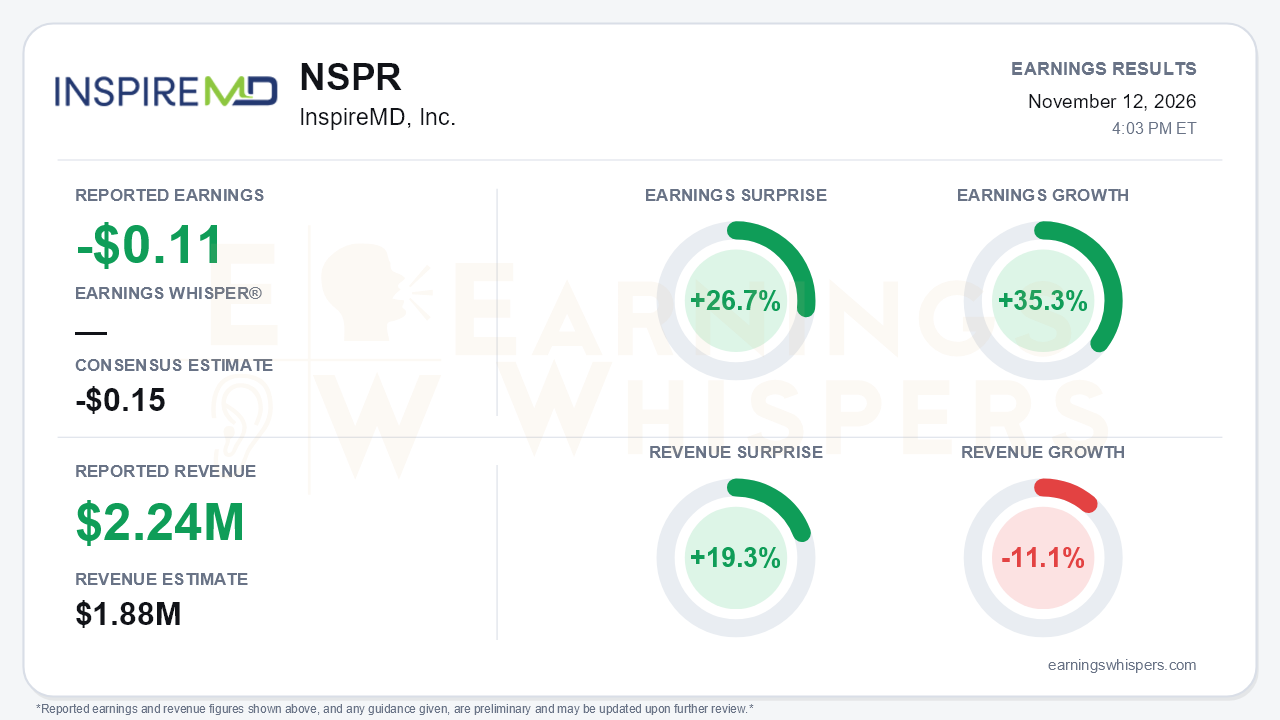
InspireMD's third quarter was a weak financial quarter attached to a strong regulatory one. The company reported a loss of $0.11 per share, beating the -$0.15 consensus by 26.7% and improving 35.3% from a year ago. Revenue of $2.24 million topped the $1.88 million consensus by 19.3% but still fell 11.1% year over year. The GAAP release shows a net loss of $9.8 million, or $0.12 per share, versus $12.7 million, or $0.17, a year earlier. The more important news came in the release headline: FDA approval of CGuard Prime for transcarotid arterial revascularization (TCAR), which returns the platform to the U.S. market. That is the central tension. The approval gives InspireMD a real U.S. growth path, but it lands just as cash runs low, margins collapse and the company turns to dilutive financing.
The quality of the beat deserves scrutiny. The revenue surprise reflects a low bar more than a recovery. U.S. sales fell to just $32,000 from $497,000 after the May recall of the CGuard Prime for CAS delivery system. International revenue grew 9% to $2.2 million, but the call showed a clear slowdown: international growth decelerated from 48% in Q1 to 21% in Q2 and 9% in Q3. Gross margin fell to 10.7% from 34.2% a year ago. Management attributed the drop to the recall and to an international mix shifting toward lower-priced countries. That second factor is not recall-related, so it may not reverse when U.S. sales resume.
The narrower loss came from the cost line, not the top line. Operating expenses fell to $10.2 million from $13.9 million a year earlier and from $13.7 million in Q2, helped by a roughly 20% workforce reduction. Q3 also included $1.07 million of restructuring charges. However, the call disclosed that opex was flattered by a $1.8 million one-time stock-compensation reversal. Excluding that reversal, the cost base was closer to $12 million than $10 million, so part of the EPS beat should not be extrapolated.
Management's tone shifted from defensive recall management in Q1 and Q2 to commercial execution, and the pipeline gives that shift some substance:
- CGuard Prime for TCAR is shipping immediately under existing hospital approvals, which management called a "warm start."
- A redesigned CAS delivery system is slated for a PMA supplement in December, with a potential relaunch in the first half of 2027.
- A proprietary micropuncture kit is planned for early 2027.
- The SwitchGuard CGUARDIANS III timeline is unchanged.
The size of the opportunity varies by source. The release cites more than 35,000 additional annual procedures, while the call framed it as roughly 40,000. Either way, management expects the U.S. addressable market to roughly double. Some timelines have slipped, however. Approval of the original CGuard for CAS was once expected in Q3 and now hinges on FDA feedback by year-end. The withdrawn FY2026 revenue guidance of $13 million to $15 million was not replaced, leaving investors without a quantitative read on the TCAR ramp.
Financing is the most immediate risk. Cash fell to $19.2 million from $30.4 million at the end of Q2 and $54.2 million at year-end 2025. That implies Q3 burn of more than $11 million, which is unsustainable against current revenue. The release carries going-concern language. Management announced an underwritten equity offering, and the TCAR approval triggered a 20-day exercise window for amended Series J/K warrants worth up to $10 million in net proceeds. Bears have legitimate ammunition here: the approval de-risks the story, but shareholders will pay for the launch through dilution.
Investor sentiment improved substantially ahead of the report, rising from -0.43 to -0.07. It is now close to neutral rather than negative. The stock's path has been volatile. Shares opened at $0.85 after the August report, peaked at $1.02 that day, then fell to a 52-week low of $0.43 on October 21. They rebounded 88% to $0.80 heading into this release, which is still 5.9% below the post-August open and nearly 23% below the $1.04 200-day moving average. The Earnings Whispers sequential-growth and AVWAP trend readings have turned positive. Even so, the stock remains well below longer-term levels, and the pending offering could weigh on the rebound.
The bottom line is that InspireMD delivered a headline beat on low expectations and cost cuts partly flattered by a one-time reversal. Meanwhile, revenue declined, gross margin fell to about 11% and international growth kept slowing. The TCAR approval genuinely changes the long-term setup by reopening the U.S. market. The near-term story, though, now depends on execution and financing: how quickly U.S. sales ramp, whether margins recover as U.S. mix returns, and how much dilution it takes to get there.
Read our earnings preview for InspireMD, Inc.: https://www.earningswhispers.com/article/NSPR/22890
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 14 hours | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-11 | |
| Nov-04 | |
| Oct-29 | |
| Sep-21 | |
| Sep-04 | |
| Sep-03 | |
| Aug-17 | |
| Aug-17 | |
| Aug-10 | |
| Aug-07 |
