Legacy Education Misses As Growth Stalls And Margins Compress, While A Record Student Base And Expansion Pipeline Keep The Story Alive
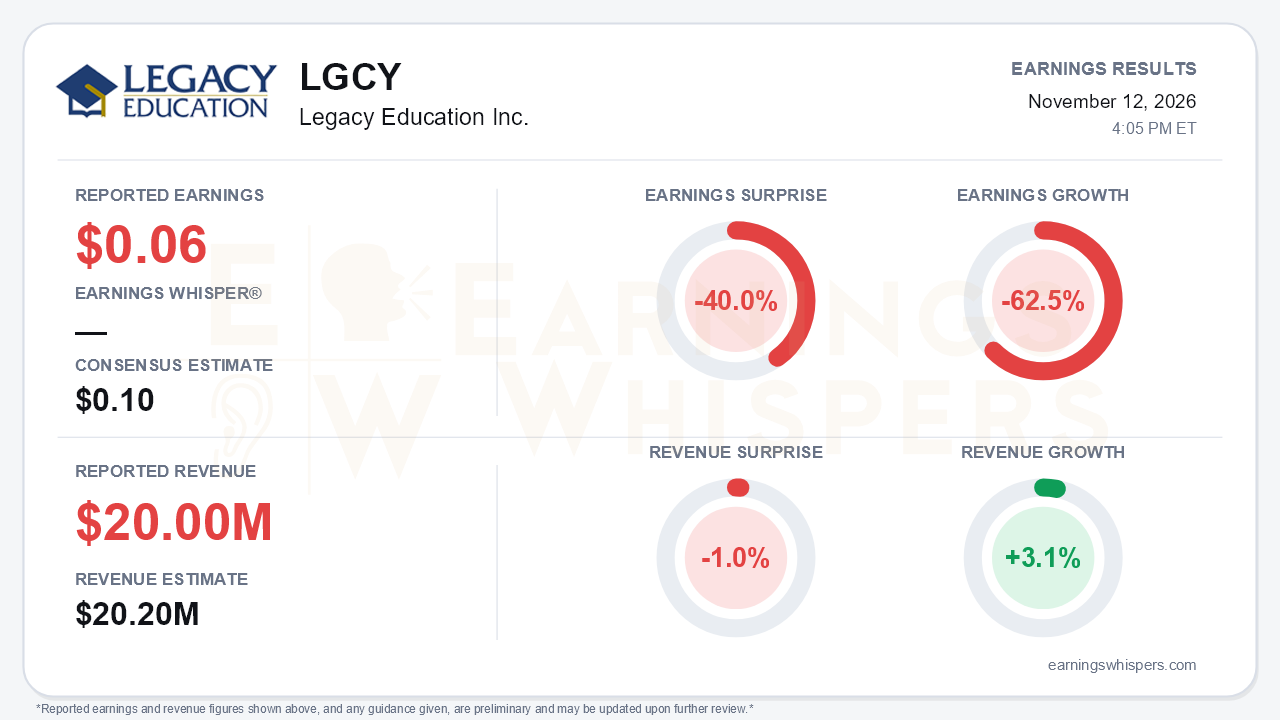
Legacy Education (NYSE American: LGCY) opened fiscal 2027 with a clear miss. It earned $0.06 per share against a $0.10 consensus, a 40.0% shortfall, and earnings fell 62.5% from a year ago. Revenue of $20.0 million came in 1.0% below the $20.2 million estimate and grew just 3.1%. That growth rate is the more important number. It continues a steep deceleration, from 40.7% in fiscal Q2 2026 to 15% in Q3, 12% in Q4 and now low single digits. The central tension is that Legacy is serving more students than ever while the growth engine that produces new students is sputtering. Meanwhile, costs are being added ahead of revenue that has yet to show up.
The quality of the miss deserves a fair reading. GAAP results included an unbudgeted $687,500 estimated legal settlement, which the company says was resolved in October. Excluding it, EPS would have been about $0.10, in line with consensus, and operating income about $1.6 million. Even on that basis, operating income was down sharply from $2.7 million a year ago. The underlying margin erosion is real:
- Educational services expense rose 13.0% and climbed to 58.4% of revenue from 53.3%. Personnel costs added $0.5 million and rent and occupancy another $0.5 million, including Phase 2 of the Wildomar lease.
- Permit delays meant the company paid occupancy costs on Wildomar space it could not yet use.
- Adjusted EBITDA margin fell to 10.4% from 15.9% a year ago and 15.5% last quarter.
That compression sits awkwardly against last quarter's CFO remark that margins would continue to increase, mostly in the second half. Operating cash flow swung to negative $0.9 million from positive $1.1 million, and cash slipped to $21.7 million from $22.7 million. The balance sheet remains clean, with minimal debt.
The call laid bare the enrollment pipeline problem:
- Total starts fell 9.9% to 1,006, the third straight quarterly decline.
- Title IV starts dropped 5.6%. Management argued they would have risen 5.5% if 105 MRI and cardiac sonography starts had not slipped into fiscal Q2, and it said those starts are now complete.
- Vocational nursing remains a sore spot, running 264 starts below original plans over three quarters. Management cited tighter admission standards and employers building in-house nursing pipelines.
The offset is a mix shift toward allied health. Starts in ultrasound, sterile processing and surgical technology nearly doubled to 338 from 172. The ending population hit a record 3,684, up 5.4% year over year and 9.1% sequentially. Vocational nursing attrition has improved 42% over 18 months, and NCLEX-PN first-time pass rates reached 88.5% in the quarter. Still, revenue growth trailing population growth suggests the record headcount is not yet translating fully into tuition dollars.
The forward catalysts are tangible:
- **Contra Costa:** The Department of Education approved the change of ownership with a provisional program participation agreement through September 2029. It came with no letter of credit and no growth restrictions, a meaningful de-risking. Contra Costa also secured approvals for Cardiac Sonography AAS, MRI AAS and Veterinary Assistant programs, slated for the second half of the fiscal year.
- **Houston:** The first campus outside California has a signed lease, with regulatory visits completed and approvals expected by the end of November. The opening is targeted before calendar year-end, with roughly 300 starts by July 1.
- **M&A:** An acquisition target is now in deep due diligence.
Bears have legitimate ammunition on execution. The prior goal of announcing a deal within fiscal 2026 was missed, and management declined to commit to a definitive agreement by December 31. Federal student aid policy remains an overhang.
The market had already priced in a good deal of disappointment. Shares closed at $8.60 on the eve of the report. That is 7.0% below the open following the prior release and 24.4% beneath the 200-day moving average of $11.37. The stock sat just 2.1% above its inter-earnings low of $8.42, set the same day, and 18.8% below its October 13 high of $10.59. Price and AVWAP trend readings are both negative. Investor sentiment, however, improved meaningfully from -0.45 to -0.23 heading into the print. It remains negative, but expectations had become less hostile. A miss of this kind tests that thaw rather than rewarding it.
The bottom line is that Legacy's quarter was weaker than even the settlement-adjusted figures suggest. Growth has slowed to a crawl, starts are shrinking and margins are moving the wrong way despite earlier promises of expansion. The bull case now rests almost entirely on future events: Houston opening on schedule, the new Contra Costa programs filling seats, the shifted MRI starts lifting fiscal Q2, and a long-promised acquisition finally materializing. The regulatory wins make that path credible, but investors will need to see starts turn positive and margins stabilize before the record student count earns much benefit of the doubt.
Read our earnings preview for Legacy Education Inc.: https://www.earningswhispers.com/article/LGCY/22929
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-04 | |
| Nov-03 | |
| Sep-25 | |
| Sep-24 | |
| Sep-24 | |
| Sep-24 | |
| Sep-15 | |
| Sep-10 | |
| Jun-16 | |
| May-15 | |
| May-14 | |
| May-13 | |
| May-05 |
