StoneX Faces Fading Volatility Test As Street Braces For Another Earnings Step Down
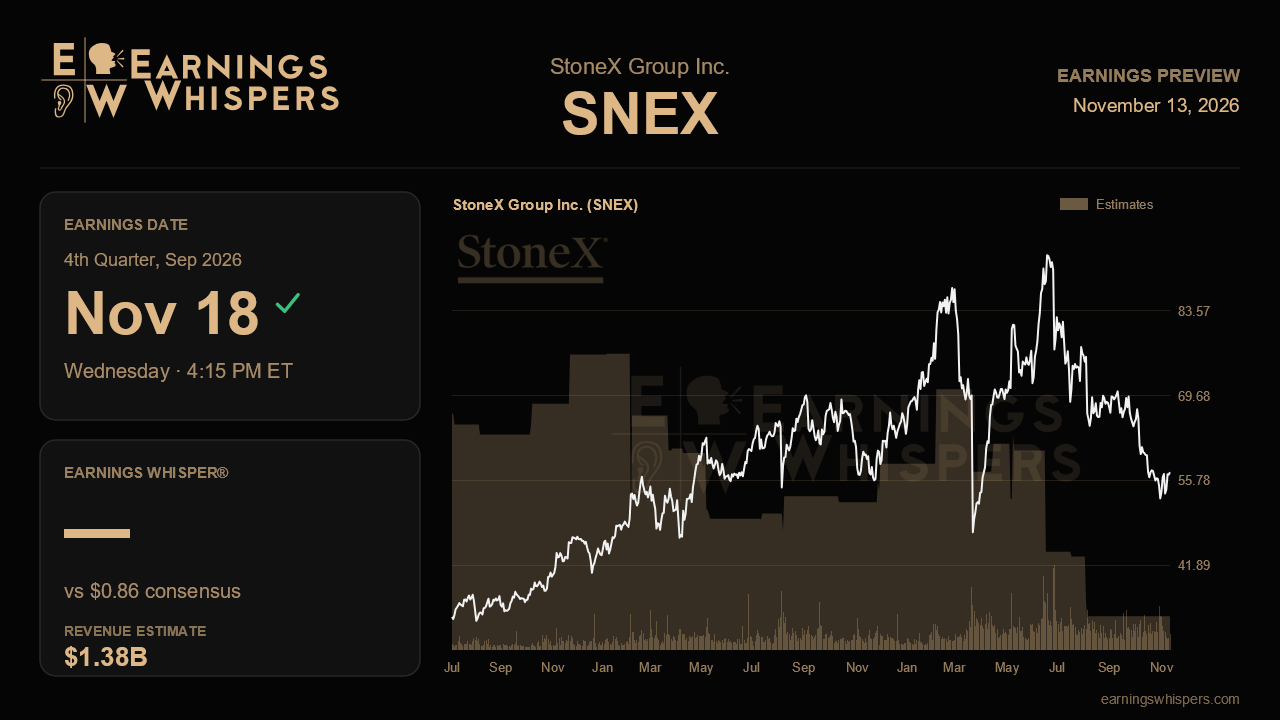
StoneX enters its fiscal fourth-quarter report with a question that the past year of exceptional results has largely deferred: how much of the company's earnings power survives once the market turbulence that fueled it calms down? Last quarter offered the first real answer, and it was mixed. Earnings per share nearly halved from the record second quarter, total net operating revenues slipped 1% sequentially, and management leaned on the phrase that results were strong in spite of moderating volatility. The September quarter, due after the close on November 18, will show whether that moderation has stabilized or kept eroding.
The Street is bracing for further softening. Consensus calls for EPS of $0.86, below the $1.00 reported last quarter and roughly 45% under the $1.57 earned a year ago. Revenue consensus sits at $1.38 billion, which produces an alarming headline decline of nearly 96% year over year. That figure should not be read as a collapse in the business. StoneX's reported total revenue, which was $40.19 billion last quarter, includes large physical commodity sales, and the consensus figure almost certainly reflects a different and far narrower revenue measure. The meaningful signal is in the EPS estimate, which implies a genuine contraction. Management did not issue formal quarterly guidance, instead reaffirming its 15% return-on-equity target and its $50 million cost-synergy goal from the RJO acquisition, neither of which was raised.
Those synergies are the cleanest place to test management's credibility. The run-rate climbed to roughly $37 million to $38 million exiting the third quarter from about $32 million a quarter earlier, with the full target now expected by the end of the first quarter of fiscal 2027. With the complex U.S. futures commission merchant consolidation completed, this report should show continued progress toward that figure and some early evidence of the cross-selling that management deliberately declined to quantify. Revenue synergies that remain vague for too long would weaken one of the key arguments for why earnings can hold up as volatility fades.
The other supports for the bull case are recurring income and payments. Net interest and fee income on client balances recovered to $111.9 million last quarter, and the company expanded its interest rate swap book to $2.55 billion at an average 3.51% to cushion against falling rates. Holding that line would confirm that the earnings base is sturdier than trading volumes suggest. Payments came close to a record quarter, with average daily volume up 20%, though the rate per million keeps sliding as high-volume, low-value flow scales. Volume growth needs to keep outrunning that pricing erosion. Global Prime, spotlighted last quarter with more than $16 billion in client balances, is a longer-term story, but continued balance growth would help.
The pressure point remains self-directed retail, where segment income fell 36% year over year last quarter on a 27% drop in FX and CFD volume. Another sharp decline would confirm that the precious-metals and volatility tailwinds have fully reversed; stabilization would suggest the worst of the normalization is behind the company.
The market has already rendered a harsh verdict. Shares have fallen about 15% since the last report, trailing the S&P 500 by more than 13 percentage points, and at $57.11 they sit well below the 200-day moving average near $71 and closer to the post-earnings low of $52.26 than the high of $71.46. Sentiment has also grown more bearish than heading into last quarter. That leaves a lowered bar. If synergies, interest income and payments demonstrate that StoneX can earn through calmer markets, the existing narrative of a structurally larger franchise stays intact. If retail weakness spreads and core income slips, investors may conclude that the record quarters were the exception rather than the new baseline.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-13 | |
| Nov-12 | |
| Nov-11 | |
| Oct-15 | |
| Oct-13 |
Why StoneX Initiated SoFi Stock At Buy Amid The Fintech's 2026 Retreat
SNEX
Investor's Business Daily
|
| Oct-02 | |
| Oct-01 | |
| Sep-30 | |
| Sep-10 | |
| Sep-09 | |
| Sep-02 | |
| Sep-01 | |
| Aug-27 | |
| Aug-24 | |
| Aug-19 |
