Nu Holdings Matches Consensus But Misses The Whisper As Record Profit Meets Slowing Loan Growth And Rising Late-Stage Delinquencies
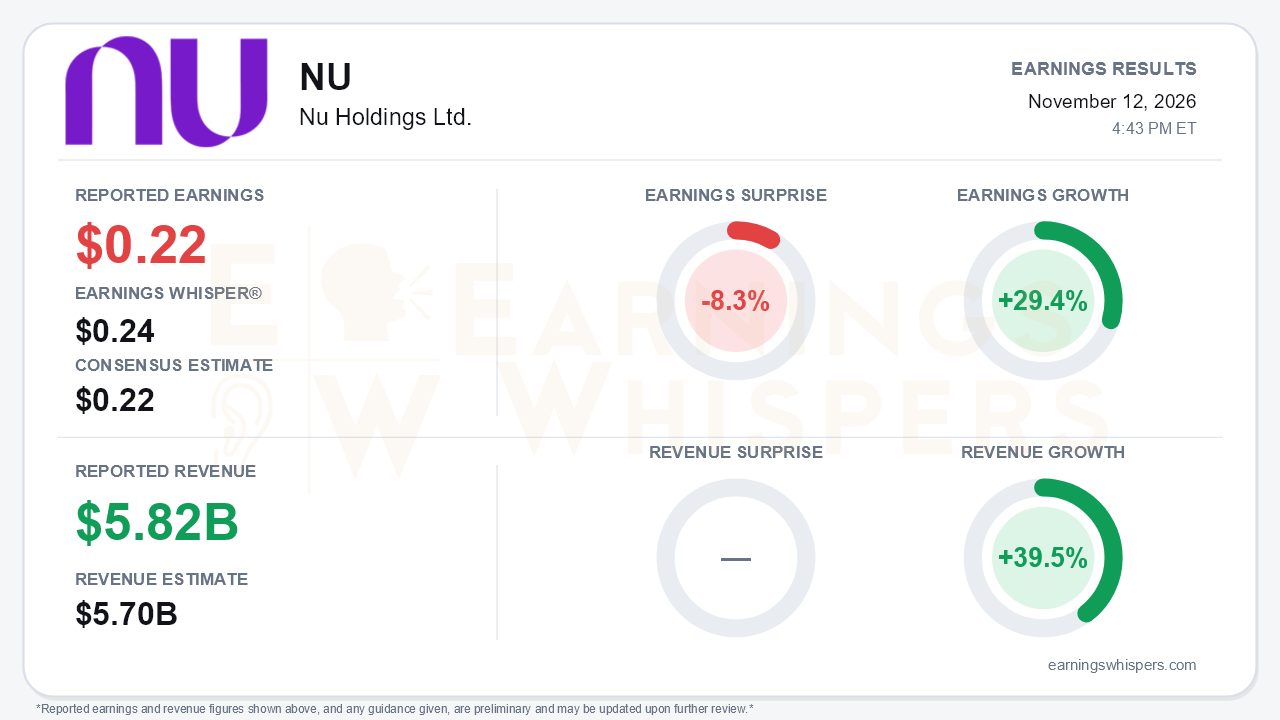
Nu Holdings delivered a record quarter that still fell short of what the most optimistic investors wanted. Earnings of $0.22 per share matched the $0.22 consensus but missed the $0.24 Earnings Whisper number by 8.3%. Revenue of $5.82 billion beat the $5.70 billion consensus by 2.1%. Earnings grew 29.4% year over year and revenue grew 39.5%. That is a strong growth profile for a bank earning a 32% ROE, but the earnings line is decelerating. Nu's own FX-neutral net income growth slowed to 31% from 49% in the second quarter. That is the central tension: the franchise keeps getting bigger and more efficient, yet the profit and credit trends that drive the multiple are cooling at the margin.
The quality of the quarter is better than the whisper miss suggests, but it is not clean. Nu reported record net income of $1.1 billion and record gross revenue of $6.3 billion, up 37% FX-neutral. That revenue figure is a broader company measure than the normalized $5.82 billion used for the comparison with expectations. Gross profit rose 35% to $2.6 billion, and credit, fees and float all grew. The miss against the whisper reflects in part a one-time charge on receivables from payment institutions placed under extrajudicial liquidation. Management put the total non-recurring net income hit at roughly $53 million. That charge cut 63 basis points from risk-adjusted NIM, so reported risk-adjusted NIM slipped to 12.1% from 12.4%. Excluding non-recurring items, it rose to 12.7% from 11.9%. That is far above the roughly 10.5% level management had signaled on the first-quarter call, and management called fourth-quarter risk-adjusted NIM "fairly sustainable." Efficiency improved to 19.3% from 19.5% in Q2 and 20.3% a year ago. Nu lowered its full-year efficiency-ratio target to 19%-19.5% from about 20%, which is an improvement because a lower ratio is better.
Beneath the headline, bears have legitimate ammunition. Credit-portfolio growth slowed for a second straight quarter, from 40% in Q1 to 37% in Q2 and 33% in Q3. The portfolio still grew 6% sequentially to $41.6 billion. The 90+ day NPL ratio climbed to 7.3% from 6.9% in Q2 and 6.5% in Q1. Measured against interest-earning balances, it rose to 12.1% from 11.6%, and coverage slipped to 234% from 244%. Management attributes the rise to portfolio mix and deliberate risk expansion. There is some support for that view: early-stage delinquency on interest-earning balances improved to 8.0% from 8.2%. Even so, rising late-stage NPLs alongside decelerating loan growth is not a combination investors usually reward. Brazil's central bank has also introduced macroprudential measures aimed at household over-indebtedness.
Operationally, the engagement story strengthened. Nu added 3.7 million customers to reach 143 million, and ARPAC rose to about $18 from $15 four quarters ago. Brazil's activity rate hit a record 86.3% for the seventh consecutive quarterly increase. Unsecured personal-loan originations reached a record R$22.1 billion, up 28%. Management's view of private payroll lending moved from cautious earlier in the year to "very comfortable." Colombia was the standout: customers rose 62%, the credit portfolio grew 80%, and Nu became the country's largest card issuer by cardholders. Mexico was more mixed. Nu added 870,000 customers in its first quarter as a bank, and new digital-payments legislation is a tailwind. However, Mexican deposits fell further to $5.3 billion from $5.7 billion.
The forward catalysts center on expansion. Nu US launched September 10 and Nu Global went live October 15. Management says their combined drag stays within the committed envelope of up to 100 basis points on efficiency in each of 2026 and 2027. The company's tone has shifted from an "investment year" framing toward global scaling, and a first Investor Day is set for December 8. Investors should also expect several headwinds:
- a sequential rise in the efficiency ratio in Q4;
- seasonal cost-of-risk pressure in Q1;
- an effective tax rate guided to the low-to-mid 20s in 2027, up from 19.2%;
- no 2027 guidance yet on loan growth or risk-adjusted NIM.
The market has been far less forgiving than the fundamentals imply. Shares have fallen 24.8% since opening at $15.74 after the August report, to $11.83. That leaves the stock about 16.8% below its 200-day moving average of $14.22. Earnings Whispers price and AVWAP trend readings are both negative. Investor sentiment moved further into negative territory, from -0.33 to -0.45. The stock therefore entered the report with skepticism already elevated, and the whisper miss and credit data gave that skepticism fresh material rather than dispelling it.
The bottom line is that Nu's quarter was fundamentally sturdier than the 8.3% whisper miss suggests. Recurring risk-adjusted NIM, efficiency, customer engagement and Colombia all improved, and the one-time charge explains part of the shortfall. Still, slowing loan growth, rising 90+ delinquencies, regulatory pressure in Brazil and a higher future tax rate argue that peak growth rates are behind it. With sentiment souring and shares well below trend, the December Investor Day and any 2027 framework now carry outsized weight in resetting the narrative.
Read our earnings preview for Nu Holdings Ltd.: https://www.earningswhispers.com/article/NU/22937
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 7 hours |
Revolut well-positioned to scale globally without damaging core markets: GlobalData
NU +6.85%
Retail Banker International
|
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-04 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 |
Lula Staged an Unexpected Comeback in Brazil's Presidential Elections. Its Markets Are Plunging.
NU -16.95%
International Business Times
|
| Oct-26 |
