Gemini Beats On The Bottom Line, But Revenue Reversal Turns The Story Into Cost Cuts Alone
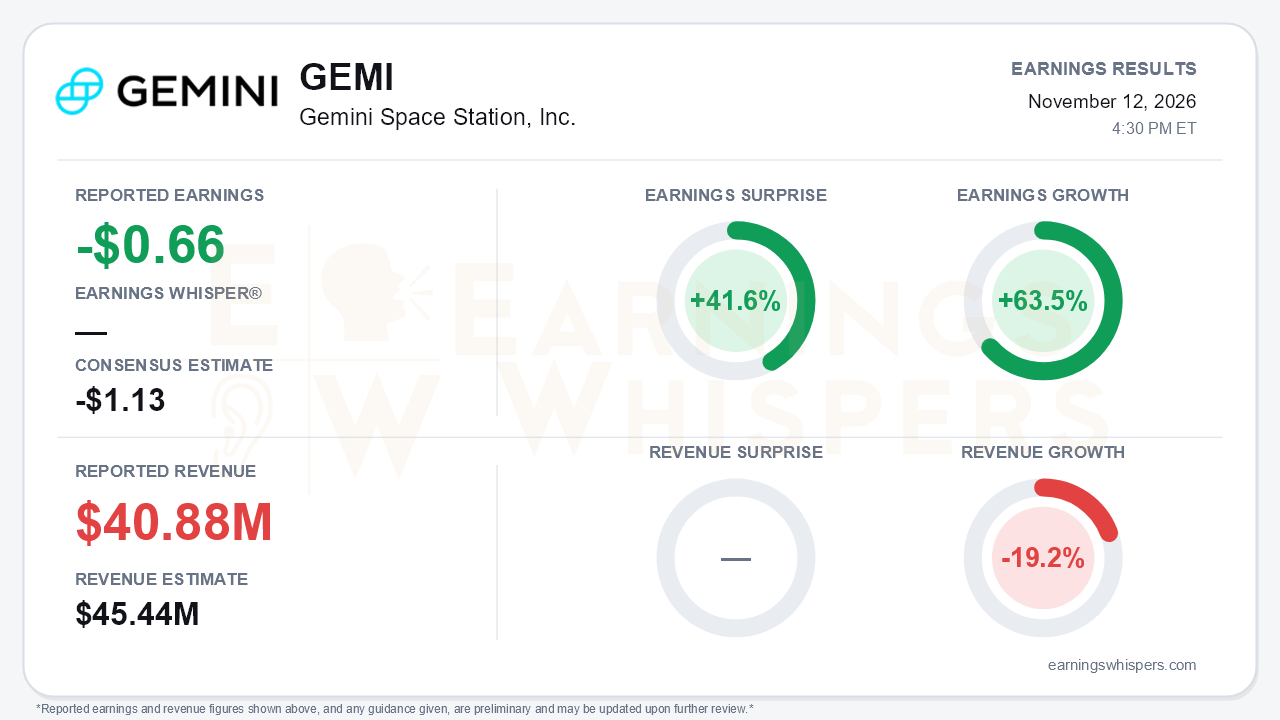
Gemini Space Station delivered the kind of quarter where the earnings beat and the business trajectory point in opposite directions. On Earnings Whispers' normalized basis, the company lost $0.66 per share, well ahead of the -$1.13 consensus for a 41.6% positive surprise, and earnings improved 63.5% year over year. The press release reports a GAAP net loss of $0.46 per share, and investors should note that gap against the normalized figure. Either way, the loss narrowed sharply. Revenue told a different story. At $40.88 million, it missed the $45.44 million consensus by 10.0% and fell 19.2% from a year ago. That is a stark reversal from the +42% and +37% year-over-year growth posted in the first and second quarters. That is the central tension: Gemini is shrinking its losses faster than expected, but it is doing so while the top line moves backward.
The quality of the beat deserves scrutiny. Total operating expenses fell for a third straight quarter to $119.9 million, down 30% from a year ago. Cash compensation excluding stock-based pay dropped 15% sequentially after the February reduction in force. Sales and marketing collapsed 75% year over year. Adjusted operating loss narrowed to $39.0 million from $49.3 million in Q2, its fourth consecutive improvement. Yet GAAP operating loss actually widened slightly to $79.0 million from $76.9 million, as lower revenue and a $12.4 million jump in stock-based compensation offset the cost savings. The dramatic improvement in adjusted EBITDA, a $11.6 million loss versus $74.0 million in Q2, leaned heavily on a $50.8 million favorable swing in crypto asset and related-party loan marks. Net loss nearly halved sequentially for the same reason. Much of the bottom-line improvement came from market prices rather than operations.
Beneath the headline, the revenue mix is thinning. Exchange revenue fell 47% year over year to $13.4 million as trading volume dropped to $4.5 billion from $16.4 billion. Sequentially there was a modest rebound: volume rose 18% and exchange revenue rose 7%, driven by institutional Zcash activity and the newly operating affiliated market maker. However, roughly 26% of spot volume ran through that affiliate, which lowers consolidated fee revenue per dollar traded. OTC revenue fell 64% sequentially. Advisory fees dropped to $0.6 million from $2.7 million as a warrant arrangement rolled off. Credit card revenue, the prior growth engine, slipped 4% sequentially to $15.5 million, and receivables declined. On the call, management described card growth as constrained by funding capacity and capital.
The tone of the call shifted as much as the numbers. Last quarter management talked about having never had a better mousetrap and framed prediction markets as the largest near-term growth opportunity. This quarter's language was 'clear-eyed,' results that 'don't yet reflect' the strategy, and an acknowledgment that some investments may need to change. Prediction revenue grew 52% sequentially, but only to about $0.8 million, and management flagged state rulings against sports contracts as a regulatory risk. Marketing guidance was cut to 7-10% of revenue from 10-15%, effectively conceding that the planned second-half customer acquisition ramp did not happen. Retail activity and new-trader acquisition remain weak, and monthly transacting users slipped to 577,000. Timelines for perpetuals and the FCM were not reiterated, and an interim CFO remains in place.
There are credible offsetting catalysts. The non-binding Apex Fintech letter of intent would make Gemini's regulated venue the exclusive outlet for crypto event contracts distributed to Apex brokerage customers. Talks with other brokerages and FCMs are ongoing, and Gemini's own clearinghouse now clears every event contract. The Galaxy credit facility was expanded by $35 million after quarter-end, and cash edged up to $194.1 million from Q2. Card credit is improving at the provision line, which fell to $9.2 million from $16.1 million. Note the delinquency figures cited differ by definition: non-fraud 30-plus-day delinquency ticked up to 3.4% from 3.3%, while the broader measure including fraud-related accounts fell to 6.0% from 9.4%. Charge-offs rose to $11.5 million as fraud-linked accounts were accelerated. Management also said it is evaluating partnerships and less capital-intensive models and will share 2027 priorities next quarter.
The market has been treating the stock harshly. Shares fell 32.8% from the $3.90 open after the August report to $2.62 and sit 46.6% below the 200-day moving average. The AVWAP trend remains negative. Investor sentiment, already negative, weakened further from -0.23 to -0.32. That is a meaningful but not dramatic deterioration, and it suggests expectations were low but not yet capitulatory.
The bottom line is that Gemini beat on earnings by cutting harder and benefiting from crypto marks, not by growing. Revenue has swung from strong growth to contraction, and the card and prediction-market engines are constrained by capital and regulation. Management's tone has turned noticeably more cautious. The Apex deal and the upcoming 2027 framework offer a path forward, but until revenue stabilizes, bears have legitimate ammunition, and the earnings surprise does less to repair the setup than the headline implies.
Read our earnings preview for Gemini Space Station, Inc.: https://www.earningswhispers.com/article/GEMI/22919
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-14 | |
| Nov-13 | |
| Nov-13 | |
| Nov-13 | |
| Nov-13 | |
| Nov-13 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-04 | |
| Oct-31 | |
| Oct-20 | |
| Oct-20 |
