Stantec Beats As North American Growth Accelerates And Margin Targets Rise, But Recovery-Aided Margins Temper The Quality
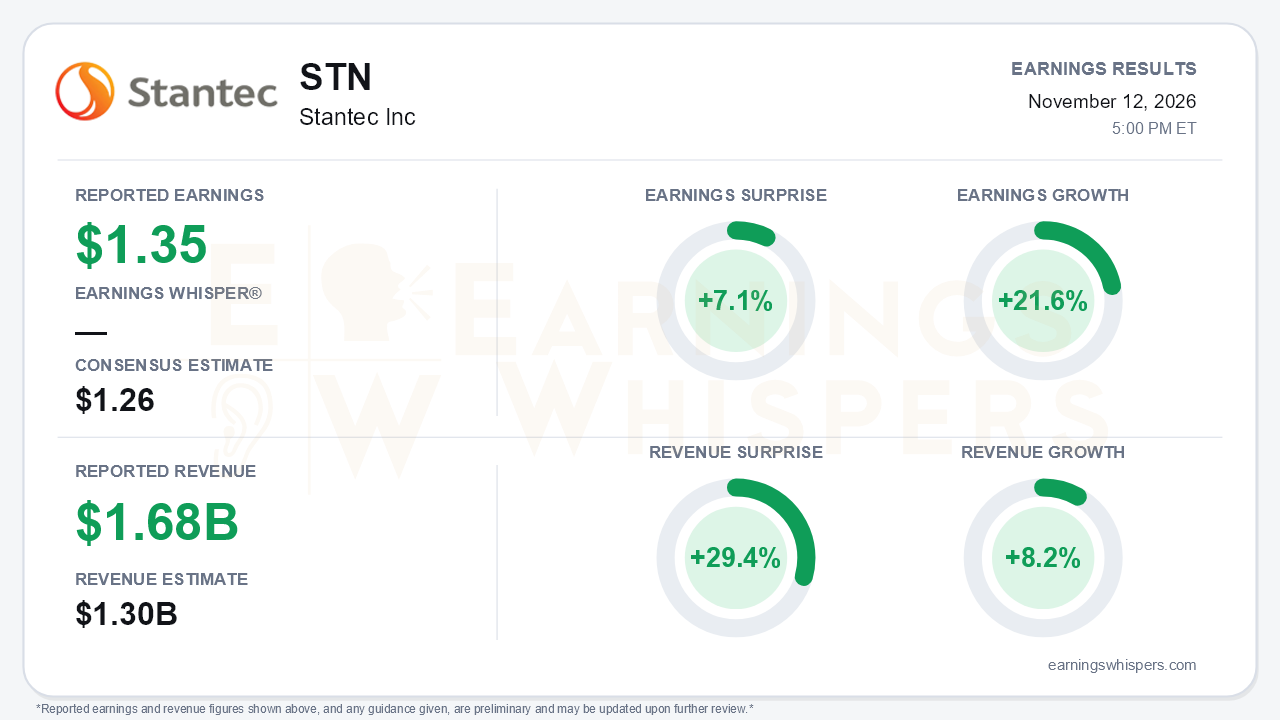
Stantec delivered its strongest quarter of the year. Third-quarter earnings of $1.35 per share beat the $1.26 consensus by 7.1% and grew 21.6% from a year earlier. Revenue of $1.682 billion grew 8.2%. The central takeaway is acceleration. Organic net revenue growth reached 5.3%, up from roughly 3.7% in the second quarter and 3.6% in the first. In the company's own Canadian-dollar reporting, adjusted EPS rose 23.5% to C$1.89, faster than the 18.4% and 14.7% gains of the prior two quarters. Management raised its margin and EPS targets for a second straight quarter. The reported 29.4% revenue surprise should be read with some caution, though. Stantec reports in Canadian dollars and headlines net revenue of C$1.9 billion alongside larger gross revenue, so the comparison may reflect differing revenue bases rather than a blowout of that size.
The quality of the beat is good but not pristine. Project margin improved 60 basis points to 55.0%. Administrative and marketing expense fell 60 basis points as a share of net revenue, which lifted adjusted EBITDA margin 120 basis points to a record 20.2%. However, the CFO acknowledged that outsized project recoveries inflated project margin by roughly 50 basis points. He guided to a normalized 54% to 54.5% and signaled more moderate margin expansion in 2027. The GAAP-to-adjusted gap is reasonable: diluted EPS rose 21.2% to C$1.60. Adjusted results exclude acquisition amortization, integration costs, and C$5.6 million after tax in accelerated incentive costs tied to the CEO's retirement. Cash generation was a clear improvement. Operating cash flow of C$392 million rose C$76 million year over year, which eased the working-capital concerns left by a weak first half.
The more durable story sits beneath the margin line. The North American recovery management had promised arrived:
- US organic growth reached 4.9%, after being flat in the second quarter, as first-half project delays largely resolved.
- Canada improved to 4.1% from 2.4%.
- Organic backlog growth climbed to about 10%, compared with 7% in the second quarter, 5.4% in the first, and 3.6% at the end of 2025.
- Canadian organic backlog jumped 18.4%.
- Total backlog reached C$9.2 billion, roughly 13 months of work.
That backlog trajectory matters more than the quarter's margin print because it underpins revenue visibility into 2027. The soft spot is the Global segment, where organic growth slowed to 7.5% from roughly 13% in the second quarter. Management expects reacceleration in the fourth quarter.
On guidance, the 'in-line' characterization and the 'raised' framing are both accurate, which explains why the update reads modestly. Stantec narrowed its 2026 net revenue growth range to 9% to 11%, leaving the 10% midpoint unchanged. It raised the profitability targets:
- Adjusted EBITDA margin moved to 18.3% to 18.5% from 17.8% to 18.3%.
- Adjusted EPS growth moved to 17% to 19% from 15% to 18%.
- The adjusted net income margin target moved to at least 9.8%.
The upside is coming from execution and cost discipline rather than a higher top-line outlook.
Catalysts are building. New CEO Susan Reisbord used her first call to point to Canada's pipeline of 150-plus major projects, many of which are already on Stantec's radar, and to improving US funding access. The December 8 Investor Day will lay out a 2027–2029 plan. The buyback program was expanded to 5% of shares, and the company has repurchased C$350 million year to date with leverage at only 1.2x. Bears still have legitimate ammunition, however:
- Claims provisions rose to about C$260 million on alleged design deficiencies, which management says are insured.
- The company disclosed a small historical backlog restatement it describes as immaterial.
- Federal coastal funding is slow, and timing of US surface-transportation reauthorization is uncertain.
- Canada faces potential wage inflation if large projects ramp simultaneously.
- Large acquisitions remain absent despite being a stated priority.
The market setup is more complicated than the surprise implies. Investor sentiment was already negative heading into the report, and it weakened further from -0.13 to -0.26. Investors appear focused on margin normalization and the slower expansion signaled for 2027 rather than on the raised targets. Shares are up only 2.4% since the open following the August report and sit about 4.7% below their 200-day moving average of $78.80. The stock has not been rewarded for a year of steadily improving results. Price trend readings are neutral, while the AVWAP trend is positive, suggesting buyers have at least been holding recent levels.
The bottom line is that Stantec's quarter showed real acceleration where it matters most: North American organic growth, organic backlog, and cash flow. Raised profitability targets reinforce a credible execution story under new leadership. The caveats are equally real. Third-quarter margins were flattered by recoveries, Global growth cooled, and management has already tempered 2027 margin expectations. With sentiment souring and shares below their long-term average, the December Investor Day is the next test of whether the backlog momentum can outweigh tougher margin comparisons.
Read our earnings preview for Stantec Inc: https://www.earningswhispers.com/article/STN/22947
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| Nov-12 | |
| Nov-12 | |
| Nov-04 | |
| Oct-21 | |
| Sep-21 | |
| Aug-18 | |
| Aug-13 | |
| Aug-12 | |
| Aug-12 | |
| Jul-30 | |
| Jul-09 | |
| Jun-17 | |
| May-26 | |
| May-14 |
